
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Unity (U) Stock Looks Cheap Based On Future Cash Flow
Unity Software has climbed back into focus after a run of positive returns and fresh product news, which puts a spotlight on a basic question for investors. Is the current share price, and the story around it, adequately backed by the cash the business is expected to generate over time?
- Over the past 5 years the stock has fallen 67%, which makes the current rebound an important test of what Unity's long term cash flow profile can reasonably support.
- Day one support for Meta's upcoming VR glasses and the associated 24% revenue increase tied to advertising solutions can influence how quickly Unity turns developer interest into sustained cash generation.
- What if you looked at Unity Software through its sales instead? See why Unity Software's 9.9x P/S tells a different valuation story.
The issue now is whether the cash flows implied by Unity Software's Discounted Cash Flow (DCF) intrinsic value estimate line up with where the shares trade today.
If you want more context around Unity Software's rebound and VR exposure, it can help to line it up against other 91 AI infrastructure stocks.
Does Unity Software Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash Unity Software could return to shareholders over time and discounts it back to today. On this view, the group is coming from a base of roughly $519.1 million in free cash flow over the last twelve months, with analyst and model projections pointing to growing annual cash flows that move into the low single digit billions of dollars over the next decade.
The DCF output suggests these projected cash streams imply an intrinsic value that sits substantially above the current share price of $45.44. Because support for Meta VR Glasses has given the stock a short term boost on the back of stronger advertising revenue, the remaining gap between price and cash flow based value looks more about questions on how durable those cash flows are than about a lack of near term excitement. Find out what Unity Software could be worth using our Discounted Cash Flow (DCF) estimate.
The Unity Software Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St act as the missing link between Unity Software's current valuation puzzle and the assumptions baked into the share price. They spell out what would need to happen to growth, margins and earnings for the stock to be worth meaningfully more or less than it is today on the Community page. Each one turns Unity Software's implied fair value into a clear, testable story about the business so you can see how that thesis holds up over time.
Unity Software has divided the community, with one group seeing meaningful upside and another arguing the stock already bakes in the good news.
Bull case: 8% undervalued
"Unity is rapidly growing its strategic, subscription-based Create business, especially with double-digit growth and high customer adoption rates…"
Discover why this Narrative puts Unity Software at 8% undervalued.
Bear case: 9% overvalued
"The accelerating adoption of no-code and low-code platforms for interactive content creation is likely to diminish demand for Unity's sophisticated engine over time…"
Explore why this Narrative puts Unity Software at 9% overvalued.
One more Unity Software factor that could matter just as much as the cash flows
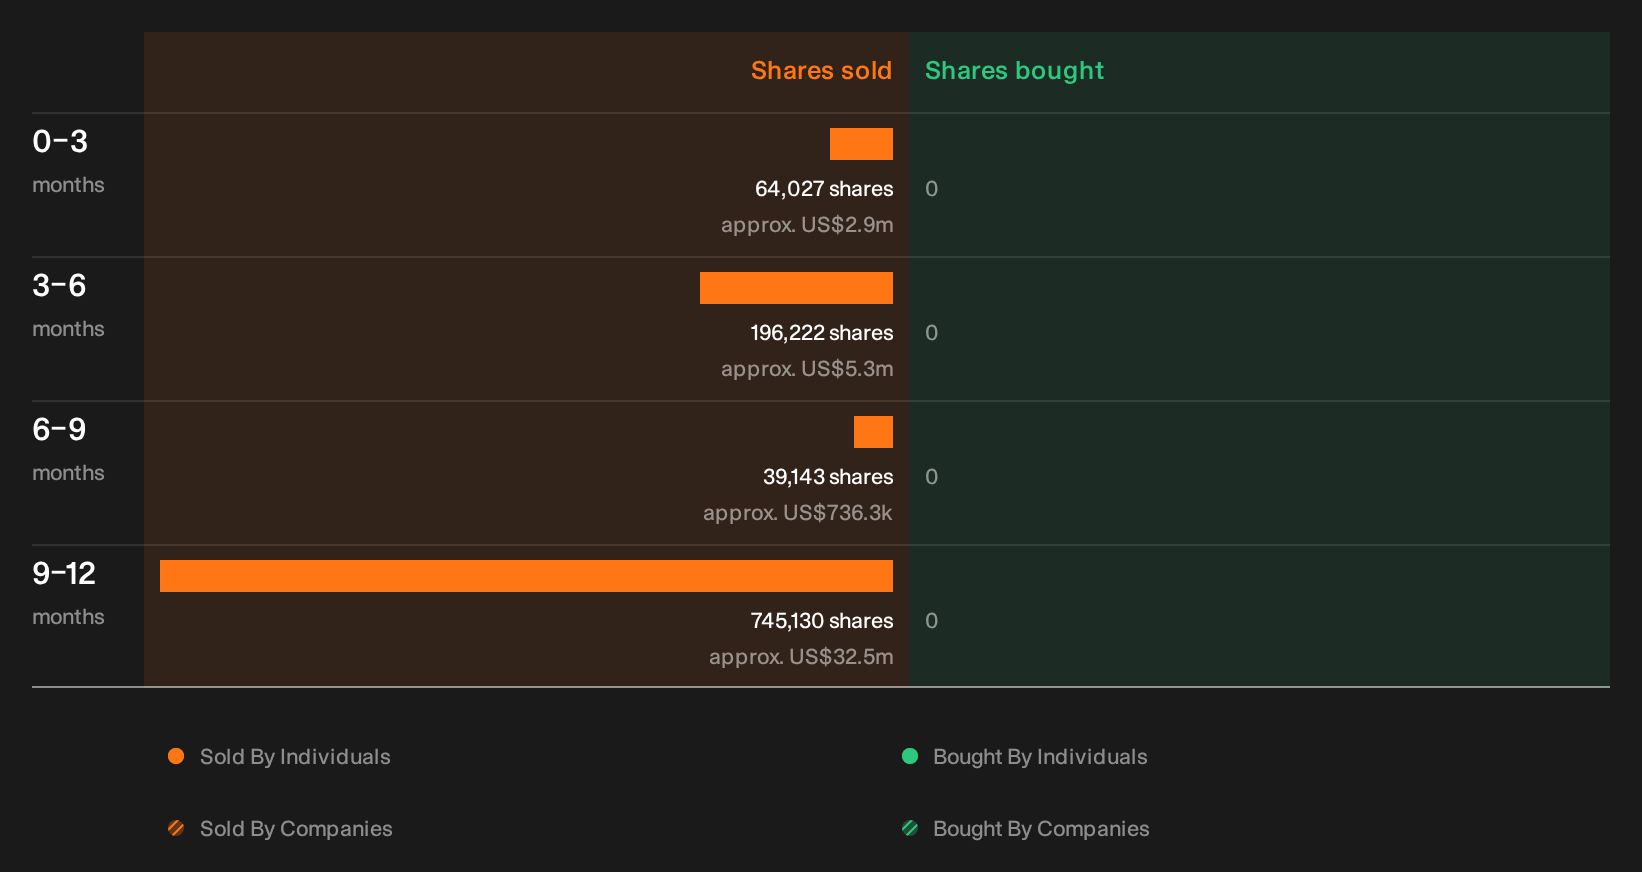
Valuation tells only part of the Unity Software story, because recent insider transactions have been flagged by our checks and the individuals involved, the sizes and what they might signal are still for you to assess. See the recent insider selling flagged for Unity Software.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com