
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Foresight Group Holdings And 2 British Value Stocks To Watch
UK government borrowing costs recently touched a 19 year high, putting pressure on companies that rely heavily on debt and optimistic growth stories. Cash rich British businesses with solid incoming cash streams suddenly look more interesting, especially when their share prices sit below estimates of fair value. This article highlights three undervalued UK stocks where discounted cash flow analysis suggests the market may be underpricing their long term earning power.
The three stocks below are a sample of what rises to the top when focusing on discounted cash flow value. The full screen surfaced 26 more companies with equally compelling stories that are not covered here. To identify and analyze those opportunities in detail, head straight to the Undervalued Stocks Based On Cash Flows screener.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings is an infrastructure and private equity manager that leans heavily on renewable energy assets to generate long term cash flows.
Operations: The Real Assets division contributes about £114.8 million of revenue and Private Equity adds £50.1 million, with most income earned in the United Kingdom.
Market Cap: £496 million
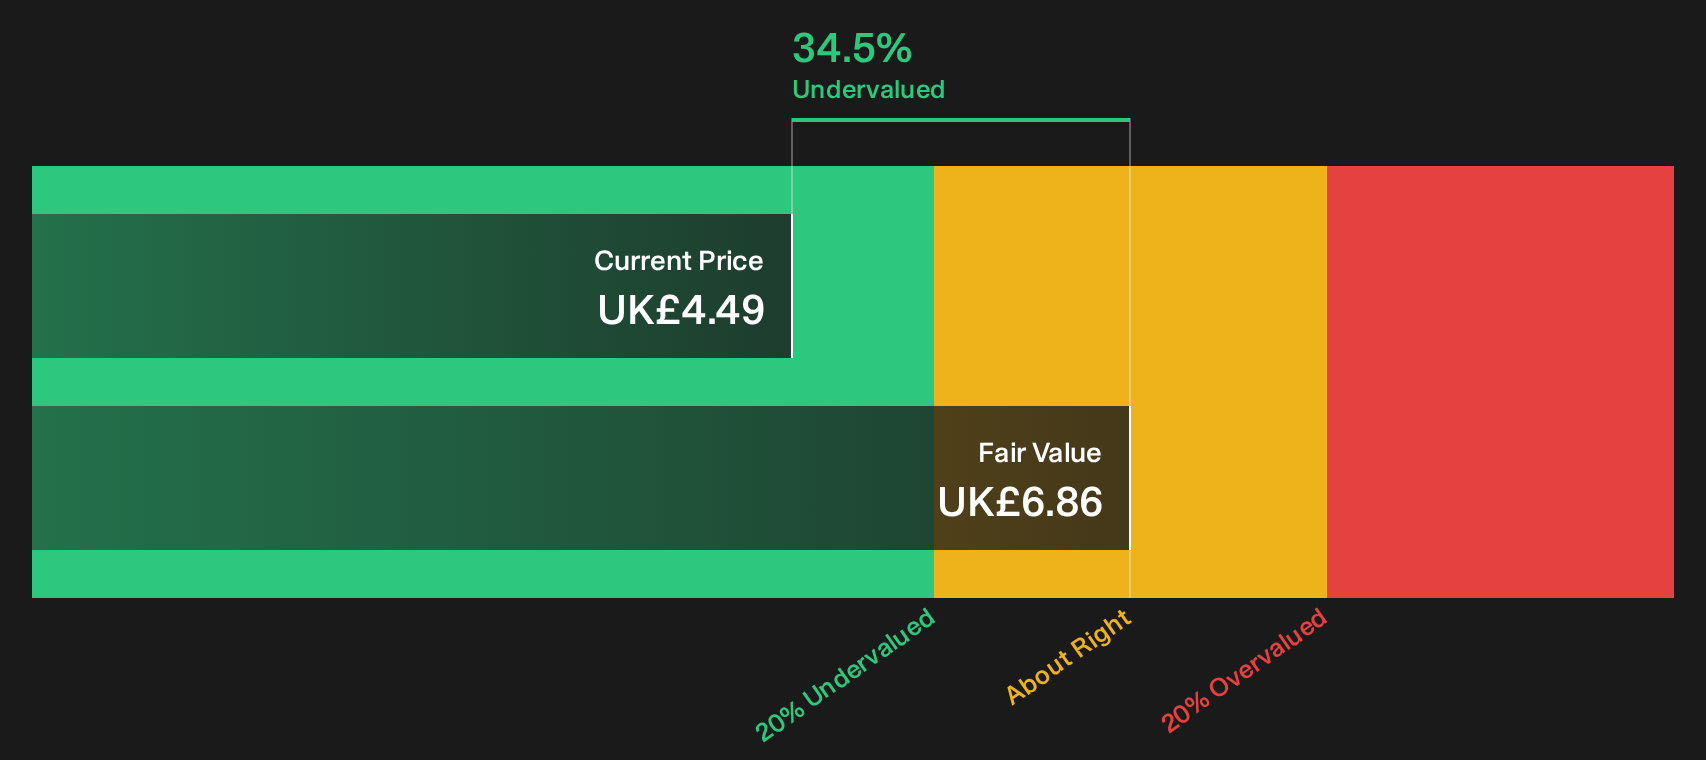
For investors drawn to the Undervalued Stocks Based On Cash Flows theme, Foresight Group Holdings offers a clear link between renewable infrastructure assets and long dated cash streams that are relatively visible, which naturally feeds into discounted cash flow style valuation work.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is expected to deliver compounding EPS growth and may support higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What really matters for Foresight Group Holdings now is how one emerging pressure shapes the balance between future profitability and cash flow resilience.
That trade off is exactly what the full narrative for Foresight Group Holdings unpacks in detail, highlighting where cash flow resilience, fee growth and capital return could be quietly accelerating.
Smiths News (LSE:SNWS)
Overview: Smiths News runs newspaper and magazine distribution plus wider logistics and field services that generate steady cash flows for valuation.
Operations: Smiths News, including DMD, produces about £1.0b of revenue, almost entirely from customers across the United Kingdom.
Market Cap: £178 million
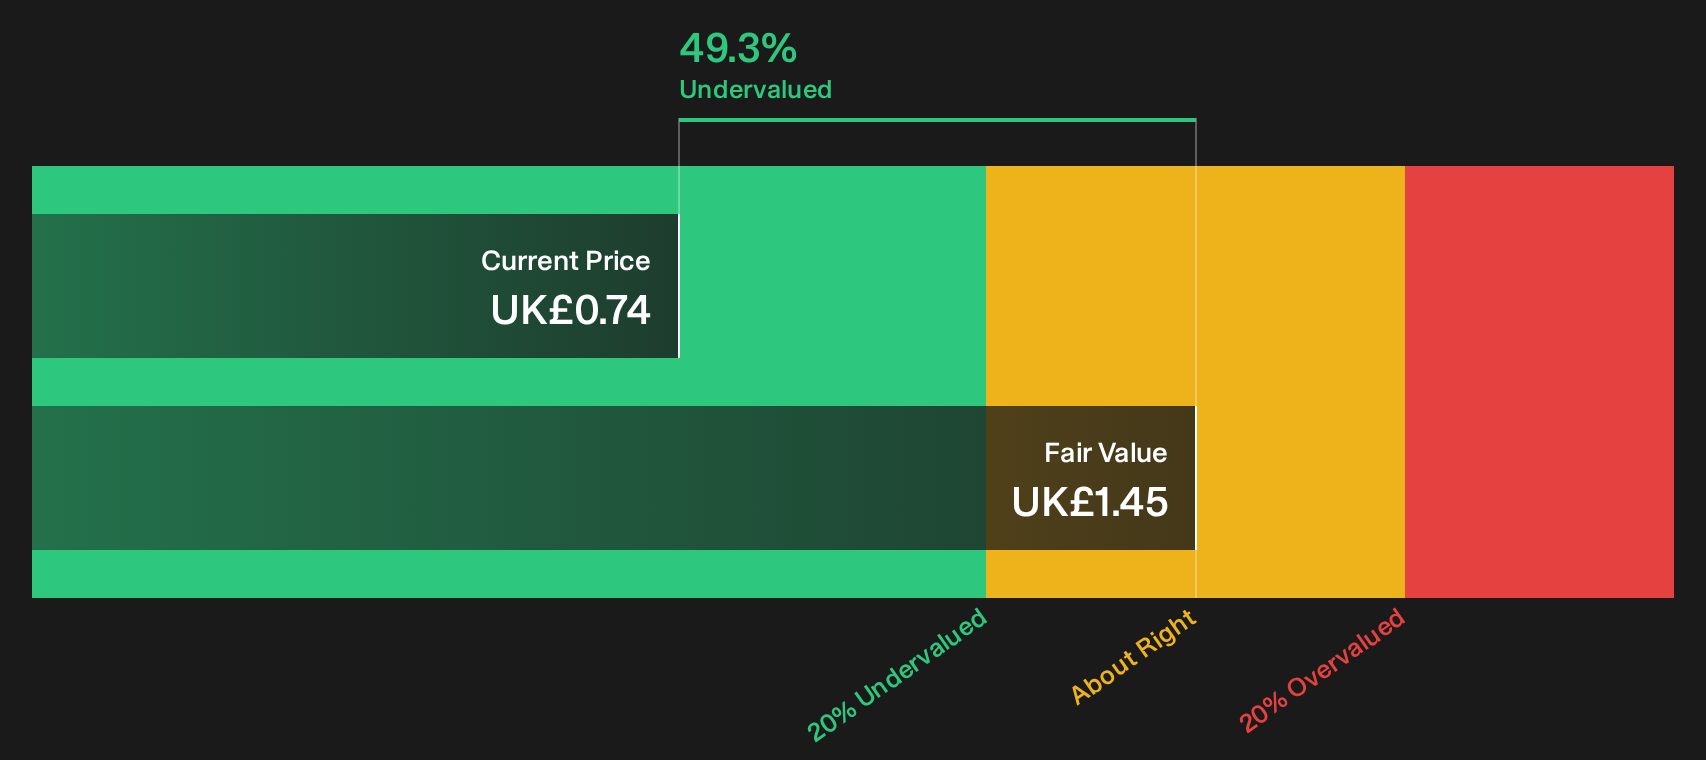
Smiths News lines up clearly with the Undervalued Stocks Based On Cash Flows theme, combining high-quality earnings, a low 6.6x P/E and a 49.3% discount to estimated fair value, supported by long-term distribution contracts where changes in assumptions about future volumes or pricing could affect the perceived reliability of those cash flows.
Those shifting assumptions make the list of solid balance sheet and fundamentals (9 results) a useful next stop for seeing where Smiths News sits against peers on resilience and valuation risk.
BAE Systems (LSE:BA.)
Overview: BAE Systems provides defense, aerospace and security solutions, supplying advanced electronics, platforms and support services to governments and allies worldwide.
Operations: Electronic Systems generates £7.8b of revenue, Air £7.7b, Maritime £6.7b and Platforms & Services £5.3b, reflecting a broad defense-focused mix.
Market Cap: £51.6b
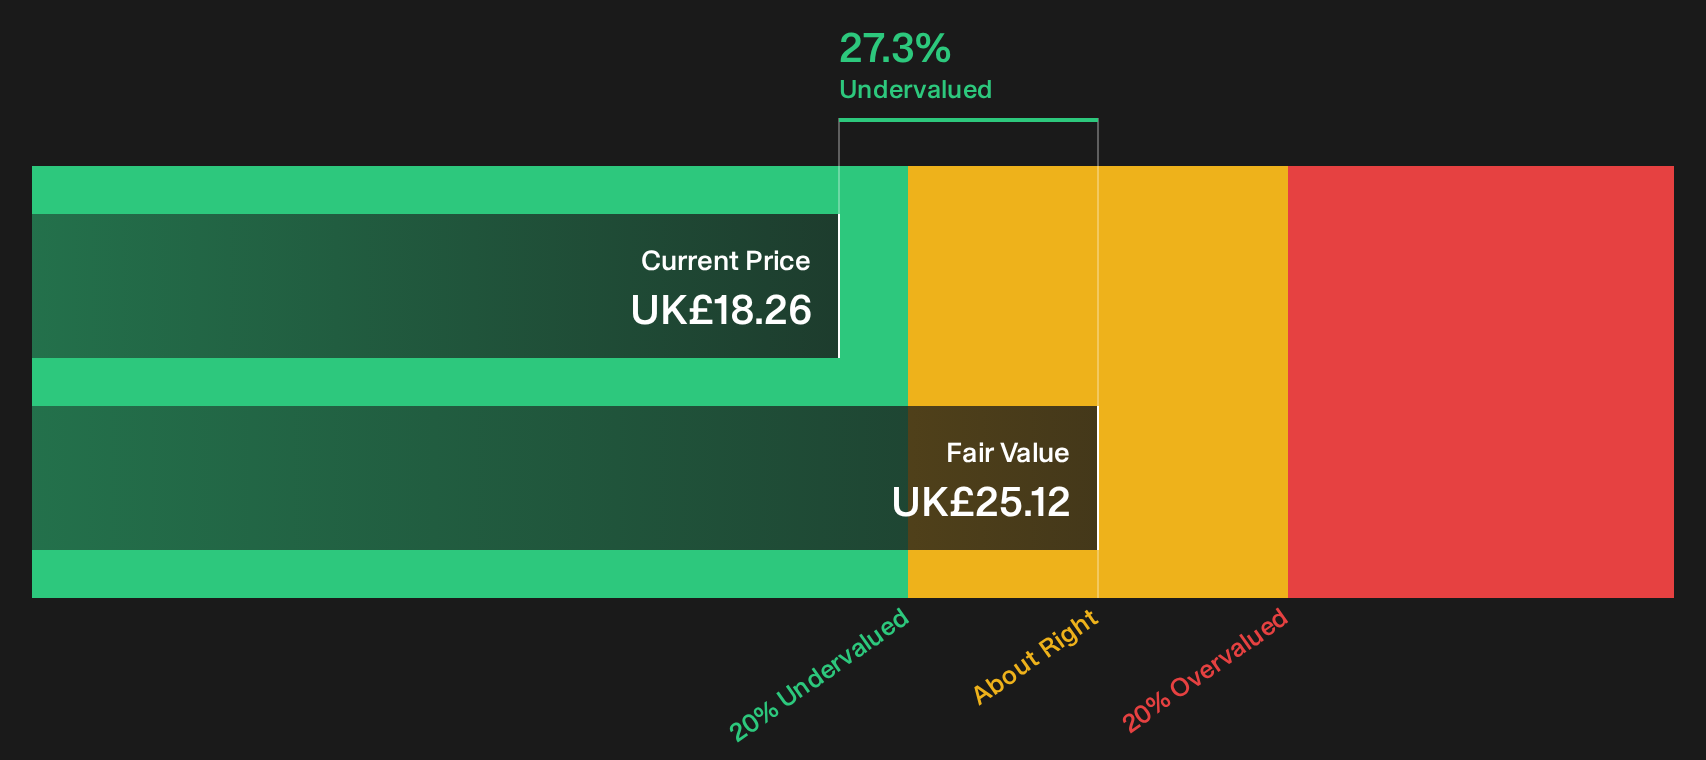
BAE Systems matters for this cash flow focused screen because its long-lived defense programs convert order backlog into contractual payments that are unusually visible years ahead.
"The company's order backlog has surged to £75 billion, with a pipeline of new opportunities partly fueled by higher defense spending commitments across NATO, the US, UK, Europe, and Indo-Pacific, providing visibility on future revenues and supporting topline performance over an extended period."
What happens to that visibility if a single assumption about future defense budgets or program timing shifts even slightly off the current track?
If that single budget assumption feels pivotal, the full narrative for BAE Systems shows how BAE Systems’ cash flows could accelerate or stall as orders shift around the backlog.
Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Once momentum builds, prices can be flying before most investors even look. Scan under the radar for now, before the crowd catches up and consider acting early if it aligns with your objectives.
- Target reliable income potential while inflation and rates shift by reviewing a curated pool of 4 dividend fortresses that aim to keep cash returns front and center.
- Track structural shifts in payments and digital assets by scanning 20 cryptocurrency and blockchain stocks positioned around blockchain rails before sentiment shifts and valuations adjust.
- Spot early movers in automation trends by reviewing 88 robotics and automation stocks that could benefit if industrial spending momentum gathers pace while attention is still elsewhere.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com