
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
American Water Works Company (AWK) Sets New Guidance Date, Is The Premium Still Justified?
Upcoming guidance puts American Water Works Company in focus
American Water Works Company (AWK) has set a date for its next update. Management plans to release third quarter 2026 results, 2027 standalone earnings guidance, and new long term financial targets on October 28.
The latest share price of American Water Works Company is $127.38, following a 1-month share price return that fell 9.47%. This extends a year-to-date decline of 2.26%, while the 5-year total shareholder return is also down 16.24%. This suggests recent momentum has been fading, even as longer-running investors still see a 3-year total shareholder return of 12.12%.
Scan the wider water and utilities space for other regulated players with similar earnings visibility profiles using our hand picked 31 resilient stocks with low risk scores alongside American Water Works Company ahead of its guidance update.
American Water Works Company still runs a critical, regulated utility network, yet the recent share price slide raises a simple question. Are you now paying a fair price for that resilience, or still a premium?
Most Popular Narrative: 10% Undervalued
On the most widely followed narrative, American Water Works Company screens as slightly below fair value, with a narrative fair value of $141.45 against the latest close at $127.38. This puts the focus squarely on how the long term plan is executed.
Heightened regulatory and societal focus on water quality and infrastructure modernization now aligns with a roughly US$48b capital plan over 10 years and US$1.8b already deployed in the first half of 2026. This supports rate base expansion that can flow through to revenue and earnings over time.
See why 34 investors see American Water Works Company as 10% undervalued.
Result: Fair Value of $141.45 (UNDERVALUED)
Still, the American Water Works Company story can unravel if that US$48b capital plan fails to earn through the regulated asset base, or if merger integration drags margins.
Find out about the key risks to this American Water Works Company narrative.
Another View: American Water Works Company Through Earnings Multiples
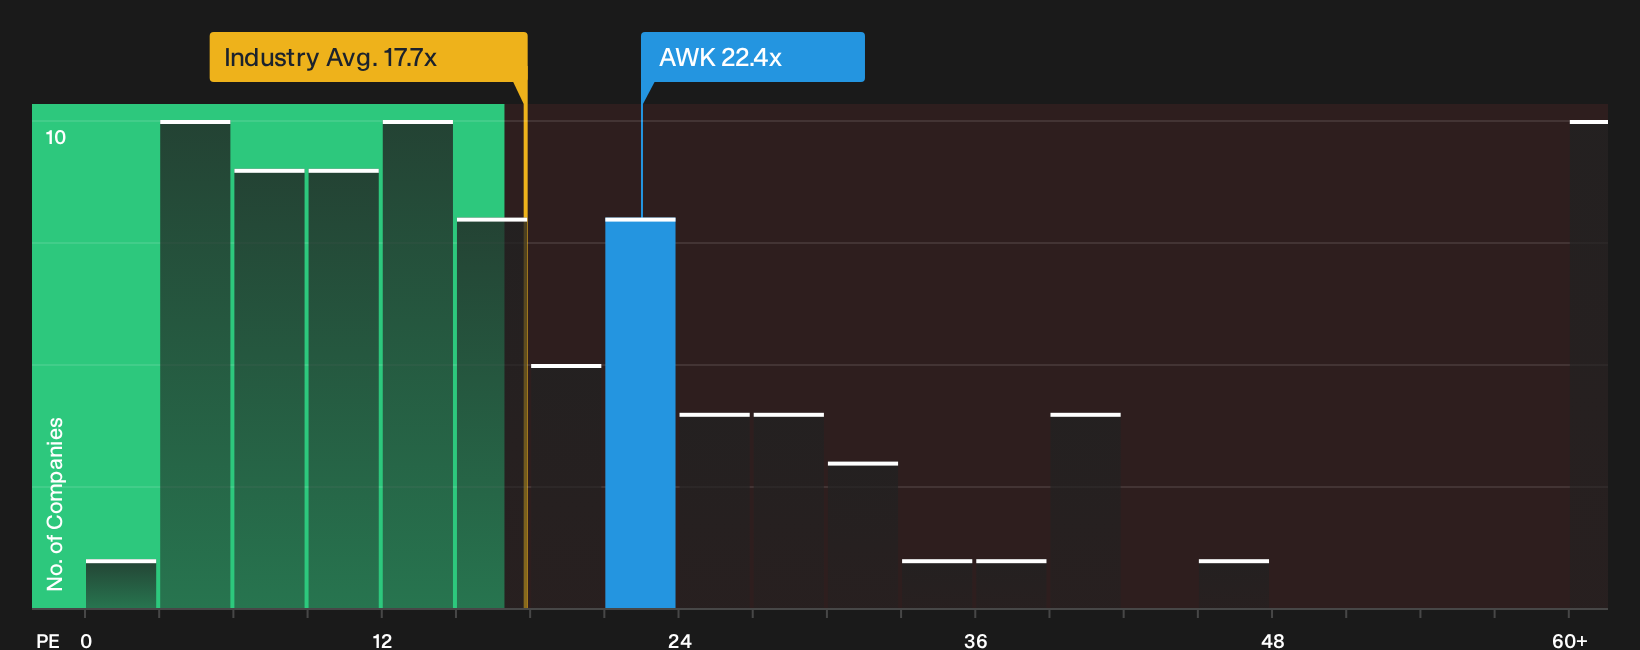
Analyst narratives frame American Water Works Company as modestly undervalued on long term fair value, yet the market is already paying a rich P/E of 22.4x. That is above both the global water utilities group at 17.7x and the peer average at 21.5x, and even above a fair ratio of 20.8x that the market could move toward.
This kind of premium can reflect confidence in earnings quality and the capital plan, but it also raises valuation risk if sentiment cools or growth underwhelms, since the share price would have more room to reset toward that fair ratio. Which story do you think investors are really pricing into American Water Works Company today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around American Water Works Company is mixed right now, with clear potential on one side and real concerns on the other, so move fast and pressure test the narrative against the underlying data yourself. To see both the upside and the caution flags in one place, review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond American Water Works Company?
Do not stop with American Water Works Company alone when there are other clear, data driven ideas waiting in the Simply Wall St Screener for you.
- Target potential value opportunities by reviewing the 29 high quality undervalued stocks that share resilient fundamentals and disciplined capital allocation.
- Lock in income-focused ideas by scanning the 8 dividend fortresses that feature substantial yields backed by underlying business strength.
- Prioritize financial strength first by working through the list of solid balance sheet and fundamentals (25 results) that keep debt in check and cash flow in focus.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com