
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Metro (HMSE:B4B0), Why Is It Back In The Spotlight?
Metro (HMSE:B4B0) is back in focus after METRO Srbija named Eduardo Lopez-Puertas as its new CEO, while former chief Nadir Kadji moves to lead METRO Turkey, highlighting internal leadership shifts across the wholesale group.
Metro’s share price sits at €7.22, and a strong year to date share price return of 26.22% alongside a 1 year total shareholder return of 32.48% points to momentum that recent leadership changes in Serbia and Turkey could either reinforce or test as investors reassess execution risk across the group.
Scan how leadership-sensitive wholesalers like Metro compare with other hand-picked value and quality opportunities using the 186 high quality undervalued stocks screen.
Bulls point to Metro’s deep wholesale footprint, value score of 4, and large €33.1b revenue base. Bears flag the recent loss and leadership changes. As you weigh valuation next, which side does the current pricing really support?
Preferred Price-to-Sales Multiple of 0.1x: Is it justified?
Valuation screens suggest Metro looks inexpensive, with the shares at €7.22 and the stock flagged as good value on a P/S ratio of 0.1x compared with both its peer group and the wider European consumer retailing space.
The P/S multiple compares the current market value of Metro to its annual sales, which for this wholesaler total €33.1b across Germany, West Europe, Eastern Europe and Asia. For a business where profits are currently negative and earnings based metrics are less informative, a revenue anchored yardstick like P/S often becomes the cleaner reference point for investors.
On Simply Wall St’s checks, Metro is described as good value on this preferred multiple when stacked against direct peers on a 0.2x average. That gap is even starker versus the broader European consumer retailing industry on 0.4x. This signals the market is valuing each euro of Metro’s turnover at a meaningful discount to competitors despite its size and experienced leadership team.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Sales of 0.1x (UNDERVALUED)
Still, Metro carries clear pressure points, including the recent loss of €264m and leadership shifts that could unsettle execution across its €33.1b wholesale network.
Find out about the key risks to this Metro narrative.
Another View on Metro’s Value
The low P/S ratio points one way, but the SWS DCF model tells a different story. On that framework, Metro at €7.22 trades below an estimated future cash flow value of €37.36 per share, which also suggests undervaluation. If both methods agree, what risk are investors really being paid for?
Look into how the SWS DCF model arrives at its fair value.
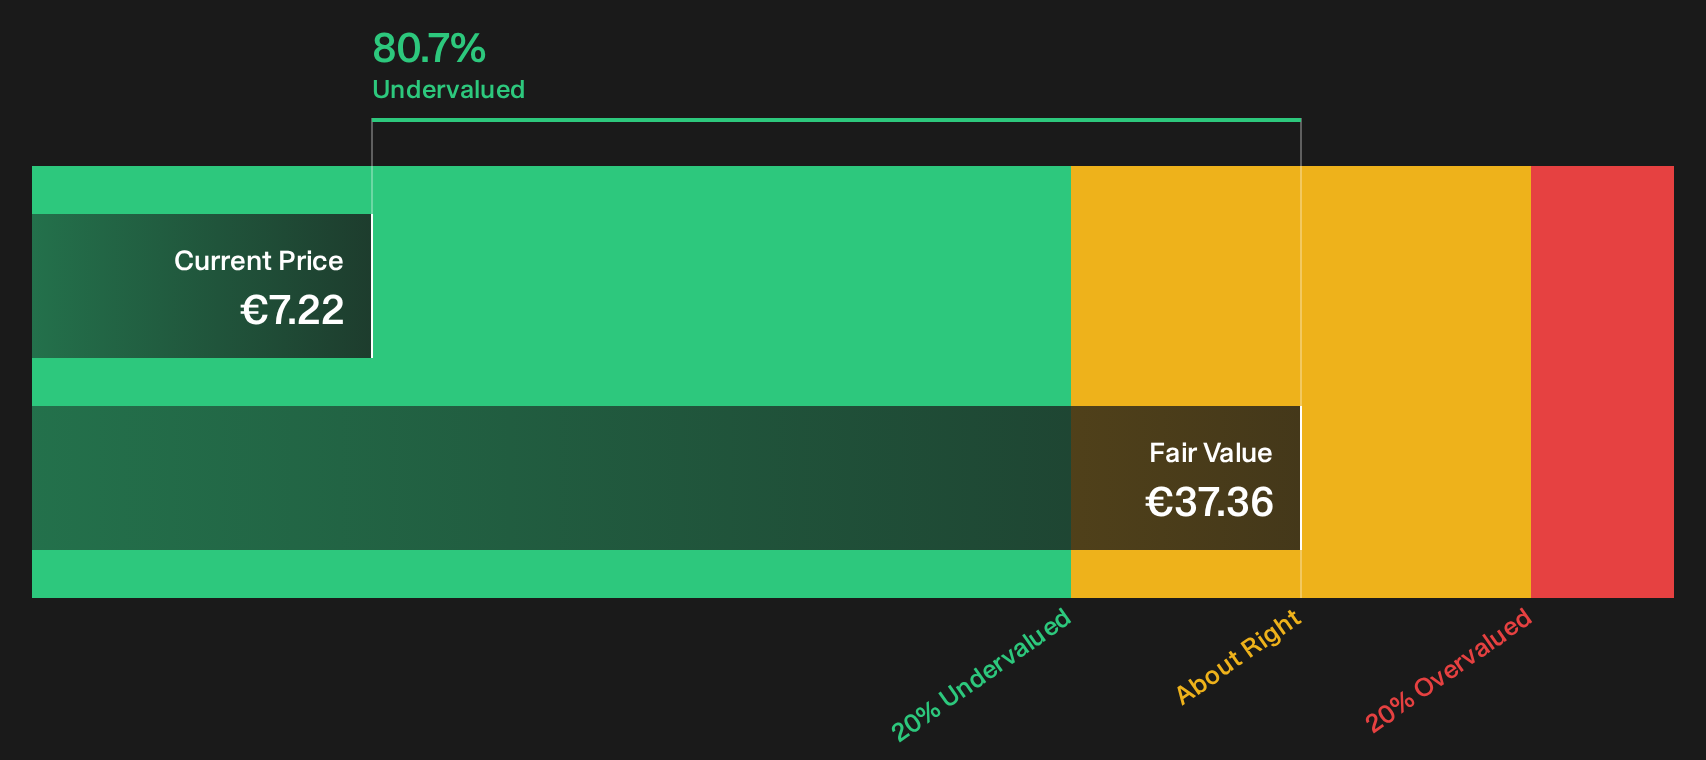
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Metro for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 186 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Unsure about Metro’s story so far and how the risk and reward trade-off really looks for you personally? Act promptly by reviewing the same facts, considering your time horizon and risk tolerance, and then grounding your view in the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Metro?
If Metro has raised fresh questions about value and risk, broaden your watchlist now so you are not relying on a single story.
- Spot potential bargains early by scanning companies that trade below what their quality suggests using the 186 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (207 results) so you can focus on businesses with stronger financial footing.
- Hunt for fresh opportunities by checking a 618 high quality undiscovered gems that surfaces quality stocks fewer investors are watching.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com