
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Universal Technical Institute (UTI) Cuts 2026 Outlook, Is The Stock Now Undervalued?
Universal Technical Institute (UTI) reported 7% year-over-year Q3 revenue growth and an 11% increase in new student starts, while reducing its fiscal 2026 outlook following softer high school enrollments and a shift toward shorter skilled trades programs.
Universal Technical Institute’s share price has been under pressure, with a 90 day share price return that declined 59.18% and a 1 year total shareholder return that fell 34.72%, even though the 3 year total shareholder return is still up more than 2x. This suggests recent guidance cuts have weighed on sentiment despite earlier gains.
Compare how Universal Technical Institute stacks up against other education and training providers facing challenges by exploring our hand picked 20 high quality undiscovered gems that the market may be overlooking.
Universal Technical Institute now trades at a steep discount to analyst targets after that sharp guidance reset. Is this genuine mispricing, or a fair warning label on a business facing tougher enrollment trends?
Most Popular Narrative: 49% Undervalued
Analysts following Universal Technical Institute see a wide gap between their fair value estimate of about $38.83 and the last close at $19.89, framing the pullback as a valuation reset rather than a simple trend break.
Strategic investments in campus expansion, new program rollouts (notably in HVAC, aviation, and allied health), and digitization efforts are expected to support top-line expansion. At the same time, the consolidation of core systems should facilitate operating efficiencies and drive long-term margin improvement beyond the near-term investment cycle. Strong engagement with employers and policymakers highlights UTI's central role in national workforce upskilling. Deeper industry partnerships and enhanced job placement services are likely to improve student outcomes, which can further bolster brand value, retention, and pricing power, with potential positive effects on both revenue and profitability.
See why 2 investors see Universal Technical Institute as 49% undervalued.
Result: Fair Value of $38.83 (UNDERVALUED)
Still, the Universal Technical Institute story can break if high school enrollment disruption lingers or if heavy campus expansion fails to translate into matching student demand.
Find out about the key risks to this Universal Technical Institute narrative.
Another View on Universal Technical Institute’s Valuation
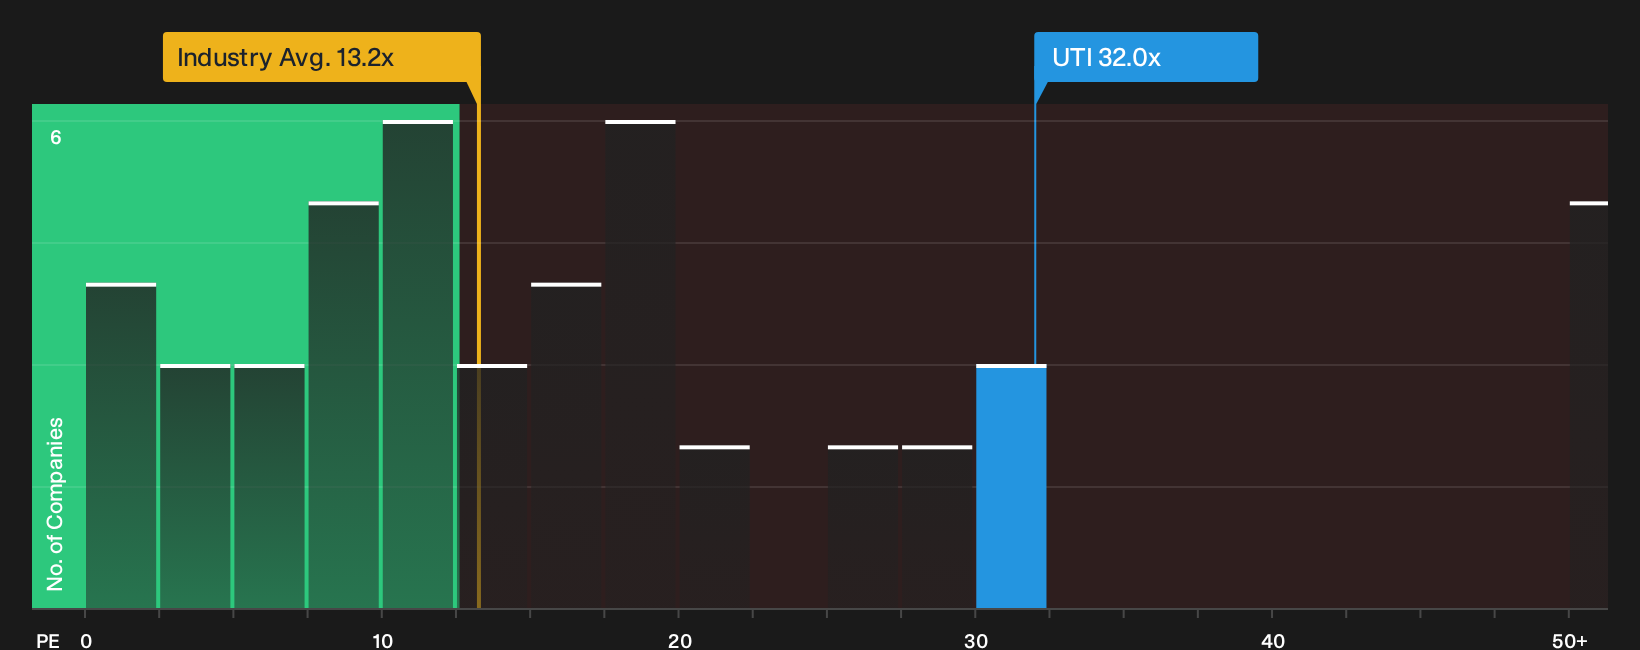
Universal Technical Institute might look cheap against the $38.83 analyst fair value, yet the current P/E of about 32x tells a different story. It sits well above the US Consumer Services sector on 13x and above peers at 17.3x, while the fair ratio points nearer 26.2x. Is the discount to targets enough to offset that richer multiple risk for you?
For a closer look at how this pricing gap could close over time, and what that might mean for upside or downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Universal Technical Institute is mixed, with both pressure points and bright spots in the story. Consider acting while information is fresh and weigh the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Universal Technical Institute?
If Universal Technical Institute has your attention, do not stop there. Broader opportunities across sectors can help you stress test your thinking and sharpen your next move.
- Target dependable cash generators by reviewing our list of solid balance sheet and fundamentals (25 results) that combine healthier finances with resilient fundamentals.
- Hunt for potential mispricings by scanning the 29 high quality undervalued stocks that currently line up with stronger quality markers.
- Prioritize stability and income potential by checking the 8 dividend fortresses built around higher yields and firmer payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com