
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ATI (ATI) Lifts Guidance Following Backlog And Margin Strength With Valuation In Focus
ATI Inc. (ATI) has moved into focus after management raised guidance on adjusted EBITDA, earnings, and free cash flow. The company cited robust aerospace and defense demand, a record backlog, and wider margins as factors supporting that outlook.
Recent trading around ATI reflects that tension between strong fundamentals and a cooling share price. The stock is down about 10% over the past month based on its 30 day share price return, yet year to date the share price return is close to 59% and the 1 year total shareholder return of about 125% points to strong momentum that has rewarded investors willing to look through short term swings.
Scan for other ATI style momentum and guidance stories by reviewing our hand picked list of 29 high quality undervalued stocks with supportive fundamentals.
ATI’s guidance hike and backlog strength point to a business that looks firmer, even as a 10% pullback hints at cooler sentiment. Which of those is driving the current valuation setup?
Most Popular Narrative: 27% Undervalued
ATI closed at $189.19, while the most followed narrative pegs fair value near $259.89, so the current pullback sits against a backdrop of higher long term earnings and margin assumptions.
Discrete investments in advanced alloys production, process automation, and supply chain partnerships are already yielding step changes in manufacturing efficiency and output, evidenced by expanding High Performance Materials & Components margins (to >24%) and stronger incremental margin capture, accelerating EBITDA and free cash flow conversion. Accelerating demand for advanced alloys in energy transition sectors, most notably commercial nuclear and gas turbines, combined with ATI's investment-led capacity expansions and unique high-value product mix, diversify the revenue base, capitalize on decarbonization trends, and improve cash generation through higher-margin growth outside core aerospace.
See why 18 investors see ATI as 27% undervalued.
Result: Fair Value of $259.89 (UNDERVALUED)
Still, ATI’s reliance on a few large aerospace customers, along with ongoing heavy capital spending, could quickly challenge that 27% undervalued narrative if conditions change.
Find out about the key risks to this ATI narrative.
Another View: ATI Looks Expensive On Earnings
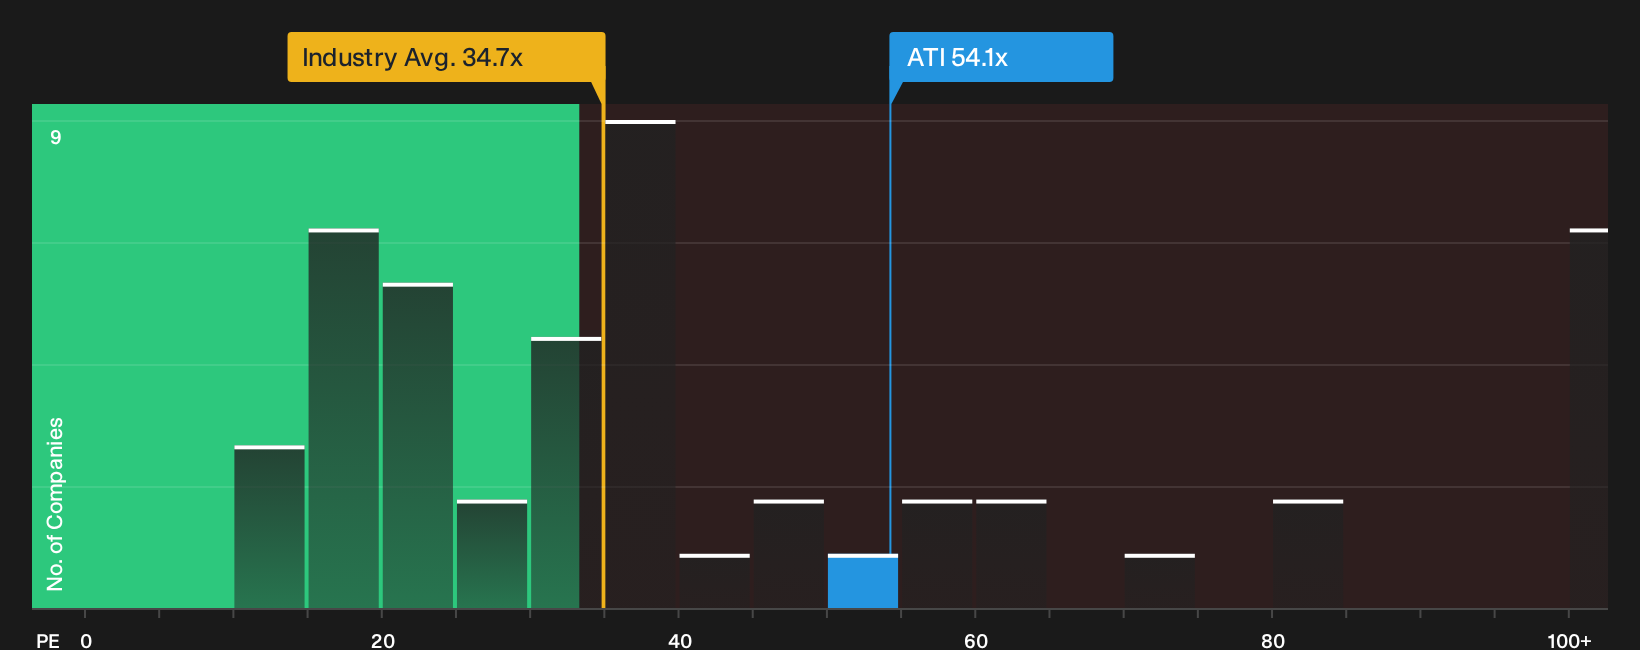
ATI might screen as undervalued on the popular fair value narrative, yet the plain P/E picture tells a different story. The stock trades on a 54.1x P/E, while the industry comes in at 34.7x and the fair ratio points to 31.1x. That gap suggests valuation risk if expectations slip even slightly. Which signal do you treat as your anchor?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on ATI after all of that. Use the same data investors are debating today, then weigh both sides through the 3 key rewards and 1 important warning sign.
Looking for more ATI style investment ideas?
Do not stop with ATI. Put the same curiosity to work across the market and let fresh watchlist ideas come to you instead of chasing headlines.
- Target resilient compounding by scanning a 31 resilient stocks with low risk scores that filters for businesses with steadier profiles and lower risk scores.
- Hunt for mispriced quality using the 20 high quality undiscovered gems that highlights companies with strong fundamentals the market may be overlooking.
- Strengthen your core holdings through a list of solid balance sheet and fundamentals (25 results) that focuses on financially sound businesses built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com