
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
PROCEPT BioRobotics (PRCT) Faces Lawsuit Questions As Undervalued Narrative Holds
The latest focus on PROCEPT BioRobotics (PRCT) stems from a fresh securities lawsuit tied to alleged discounting practices and coincides with the appointment of cardiac surgeon Dr. Michael Mack as an independent director.
For context, PROCEPT BioRobotics shares trade at US$17.91 after a sharp 30 day share price return decline of 21.31%, contributing to a year to date share price return fall of 41.77% and a 1 year total shareholder return decline of 48.46% as investors react to the lawsuit headlines and boardroom changes while reassessing longer term risks and potential.
Contrast PROCEPT BioRobotics' legal and governance stress test with other potential opportunities by scanning our hand picked 31 resilient stocks with low risk scores, which aim to keep business risk scores in check.
After a steep reset that leaves PROCEPT BioRobotics at US$17.91 and facing both a lawsuit and fresh oversight, are investors now paying for past optimism, or still getting meaningful upside on today’s valuation?
Most Popular Narrative: 70% Undervalued
Against PROCEPT BioRobotics' last close at $17.91, the most followed narrative on Simply Wall St anchors fair value closer to $60, which frames the recent selloff as far more severe than that valuation story suggests.
I have been an investor in PRCT since before IPO. The wild fluctuations in share price recently make no sense. The sell side analyst who chased the share price up to highs in 2024 (when the price was way too frothy) are doing the same thing now by revising the share price lower and lower, when clearly the company is still doing a great job. The recent downgrade by Leerink, citing PAE as a possible headwind for PRCT growth, is in direct opposition to what Larry Wood (CEO) stated at the last earnings call. To quote Larry Wood, “I don’t think PAE is a headwind for us at all. I think PAE is a big red herring. It’s a procedure that really does not get performed in any volume in Europe. And the reason it doesn’t get performed is because it doesn’t get paid for because it’s not a very good procedure.” So if you believe Larry Wood, then the company has been grossly oversold and looks very very cheap down here. If PRCT hit the Q2 numbers watch all the sheep suddenly revise their target prices back up again. I think fair value is still up at $47. PRCT had a reassessment of how to report handpiece sales versus procedures and therefore there was a shortfall on revenue. Clearly they could have stuck with the old model and revenue would have been better. Larry is doing a great job of making reporting a direct reflection of procedures being done. If the numbers are delivered, watch this thing fly.
See why 6 investors see PROCEPT BioRobotics as 70% undervalued.
Result: Fair Value of $60 (UNDERVALUED)
Still, two things could puncture that 70% undervalued story quickly: the outcome of the new lawsuit and any hit to PROCEPT BioRobotics' urology demand narrative.
Find out about the key risks to this PROCEPT BioRobotics narrative.
Another View On PROCEPT BioRobotics' Valuation
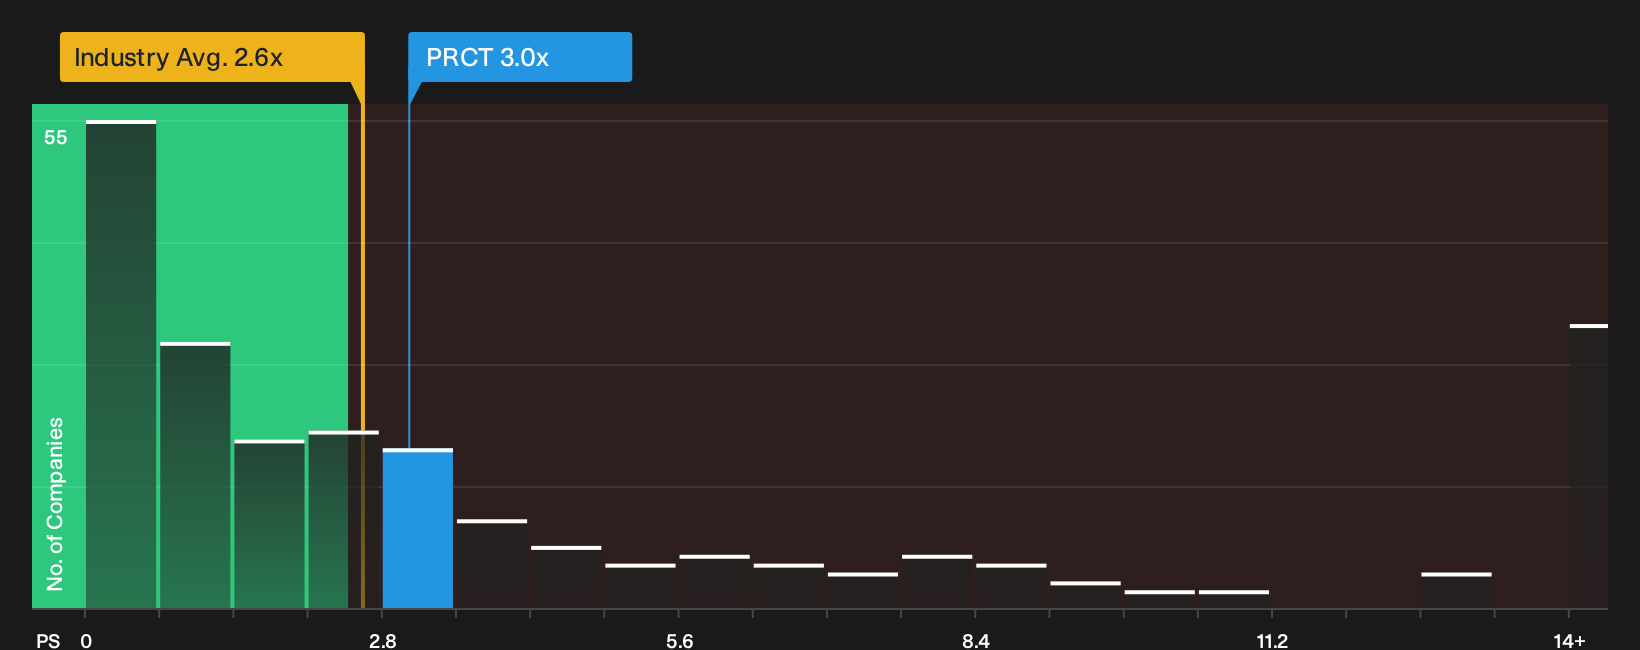
That $60 fair value narrative paints PROCEPT BioRobotics as deeply undervalued. A different lens tells a cooler story. On a P/S of roughly 3x, the stock trades above the US Medical Equipment industry at 2.6x but around its own fair ratio of 3x, which points to limited valuation cushion if sentiment sours.
Investors weighing that premium against industry peers might ask whether the story here is mispricing or simply higher expectations baked into the current tag, and what would really need to change for that gap to widen.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading this mix of concern and optimism around PROCEPT BioRobotics, you should move quickly, scrutinise the full data set yourself, then weigh the 1 key reward and 1 important warning sign.
Looking For More Investment Ideas Beyond PROCEPT BioRobotics?
If PROCEPT BioRobotics has you rethinking risk, use this moment to widen your watchlist with a few focused stock idea sets built around clear filters.
- Target stability first by scanning a list of solid balance sheet and fundamentals (25 results) to help you focus on businesses with stronger financial footing than the broader market.
- Hunt for mispriced opportunities through the 29 high quality undervalued stocks and see which companies trade on numbers that look disconnected from their fundamentals.
- Build a cash flow stream by reviewing the 8 dividend fortresses and identify income ideas that could complement higher risk growth positions in your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com