
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Intuitive Surgical Stock Could Change Following Barclays Coverage
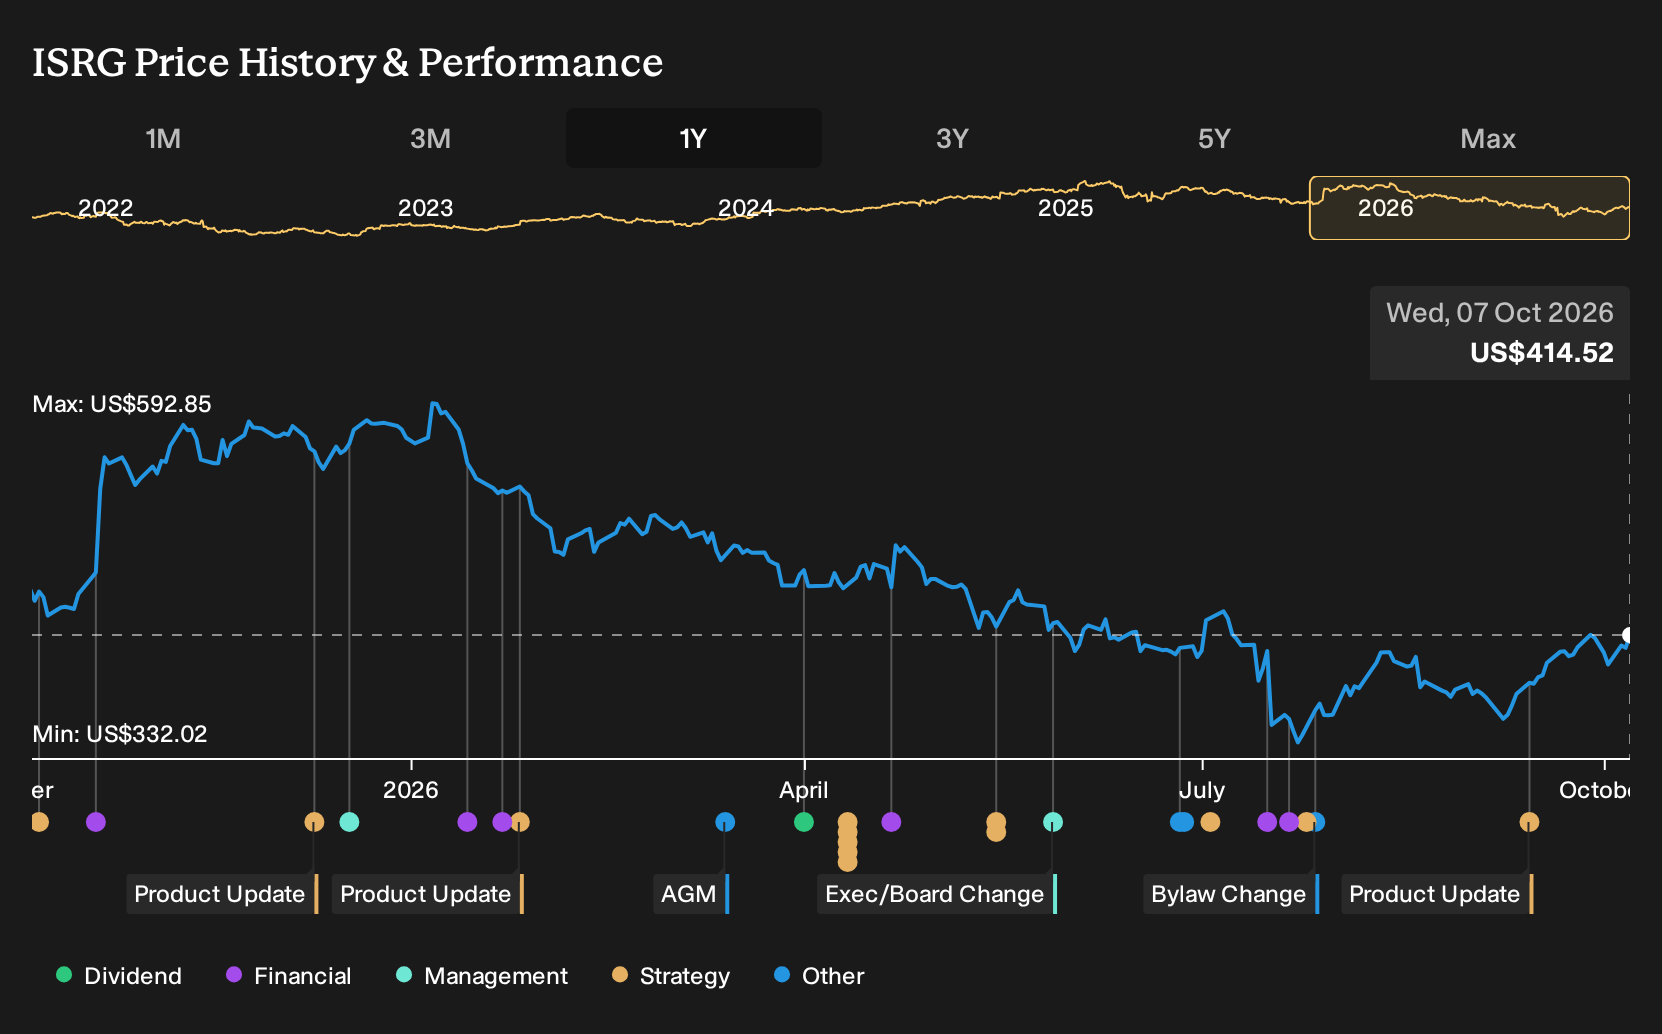
- Intuitive Surgical is back in focus after Barclays initiated coverage, and investors are looking ahead to the October 20 earnings update on procedures, systems and margins.
- The real swing factor is how Intuitive Surgical defends its high margin robotic surgery franchise as Johnson & Johnson’s newly authorized OTTAVA platform enters the market.
- We will explore how Intuitive Surgical's investment narrative holds up as Barclays coverage intersects with scrutiny of its competitive moat.
Scan how Intuitive Surgical stacks up against other potential robotics beneficiaries by reviewing our hand picked 88 robotics and automation stocks in one place.
Intuitive Surgical Investment Narrative Recap
To be a shareholder in Intuitive Surgical, you need to believe that robotic assisted procedures keep compounding on its installed base and that hospitals lean into da Vinci and Ion usage rather than slowing capital decisions. The key near term catalyst is the October 20 earnings report, where investors are focused on procedure trends, utilization and any commentary on pricing.
The biggest current risk sits with competition and pricing pressure, especially as Johnson & Johnson rolls out OTTAVA and hospital budgets stay tight in regions like China and parts of Europe. Recent commentary from Jim Cramer on valuation does not change the operating story, though it keeps attention on how much investors are willing to pay for that growth.
The most relevant recent datapoint is Intuitive Surgical’s Q2 2026 update that showed 16% worldwide procedure growth and rising usage outside the US to 38% of da Vinci volume. That kind of throughput is what supports recurring instruments, accessories and service revenue, which matters more than any single quarter of system placements.
Set against the October 20 earnings catalyst and Barclays’ fresh coverage, that procedure momentum is what investors are weighing against Johnson & Johnson’s OTTAVA launch and Cramer’s valuation concerns. If utilization on da Vinci and Ion remains healthy, the business has more room to fund R&D and cost per procedure efforts, even if pricing pressure or slower system decisions start to show up.
What The Current Consensus Implies For Intuitive Surgical
Analysts sketch out a fairly specific roadmap for Intuitive Surgical over the next few years, even if individual forecasts differ at the edges. Revenue is modeled to rise by 11.9% per year for three years, while profit margins are expected to shift from 28.4% today to 30.7% over the same stretch. On that framework, consensus points to earnings moving from US$3.1b today to about US$4.8b by 2029, with the more cautious end of the range closer to US$4.2b.
Intuitive Surgical's narrative projects US$15.5b revenue and US$4.8b earnings by 2029. This is based on an 11.9% yearly revenue growth assumption and an earnings increase of roughly US$1.7b from current earnings of US$3.1b.
Those numbers also carry an embedded view on what investors might be willing to pay for the stock. The current P/E multiple of 44.3x would need to ease to 43.5x on the 2029 earnings estimate to match the analyst price targets. This still sits well above the cited 24.8x P/E for the broader US medical equipment group and highlights how much of Intuitive Surgical's story is tied to the durability of its margin profile and recurring revenue stream rather than any single quarter of system sales.
Uncover why Intuitive Surgical's fair value indicates a 15% potential upside to its current price, a discount that could narrow relatively quickly.
Exploring Other Perspectives
For a very different angle, focus on the bullish catalyst around Intuitive Surgical’s da Vinci 5 and digital tools rather than competition risk. The most optimistic analysts were penciling in revenue of about US$17.4b and earnings of US$5.1b by 2029, with a 53.7x P/E. These views were set before the recent Cramer comments and OTTAVA headlines, so you should expect opinions and possibly forecasts to shift as fresh information lands, and explore more than one version of the story before deciding how you feel about the stock.
Explore 8 other Intuitive Surgical fair value estimates, including one that suggests there could be as much as 52% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Intuitive Surgical research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Intuitive Surgical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intuitive Surgical's overall financial health at a glance.
Looking For More Investment Ideas Beyond Intuitive Surgical?
Once you have a clear view on Intuitive Surgical, it can help to compare the story against other opportunities that match your risk tolerance and income goals. The Simply Wall St Screener is a quick way to line up different types of stocks side by side and see how their fundamentals stack up.
- If capital preservation is your priority, start with resilient companies that screen well on stability and business quality through the 31 resilient stocks with low risk scores.
- For investors hunting for value, compare Intuitive Surgical's profile with a broader 29 high quality undervalued stocks that pair strong fundamentals with more modest pricing.
- If balance sheet strength matters most, focus on businesses that combine lower leverage with solid cash generation using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com