
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Howmet Aerospace (HWM) Dropped, What Is Driving Attention Now?
Howmet Aerospace (HWM) heads into its 29 October 2026 earnings release with investor attention rising, as optimism around future profits meets a share price that has recently pulled back and a valuation premium to peers.
Over the past few months, momentum in Howmet Aerospace has cooled, with the share price down 14.1% over 30 days and 18.6% over 90 days, even as the year to date share price return is positive and the 5 year total shareholder return is very large. Recent weakness appears tied to investors reassessing risk around a premium valuation ahead of the October earnings update. Longer term holders have still seen substantial wealth creation, reflected in that multi year total shareholder return profile.
Scan Howmet Aerospace alongside a hand-picked 29 high quality undervalued stocks that also carry strong balance sheets and positive earnings sentiment ahead of their next reports.
The pullback in Howmet Aerospace could hint at doubts creeping in about the business, or it could simply reflect sentiment cooling after a strong multi year run. That tension is where valuation work really matters.
Most Popular Narrative: 33% Undervalued
Compared with Howmet Aerospace's last close of $222.75, the most followed narrative pegs fair value at about $331.50. This frames the recent pullback as a valuation gap rather than a broken story.
Major capacity expansions in high margin engine products and industrial gas turbines are moving into a heavier CapEx phase, with spending expected to exceed US$500m in 2026 and step up further in 2027. This is supported by long term customer agreements and can add to revenue and EBITDA as new plants and large casting furnaces come online.
See why 85 investors see Howmet Aerospace as 33% undervalued.
Result: Fair Value of $331.50 (UNDERVALUED)
Still, this storyline can crack if heavy CapEx fails to convert into strong cash returns, or if turbine and aftermarket demand proves less durable than analysts assume.
Find out about the key risks to this Howmet Aerospace narrative.
Another View: Howmet Aerospace Through The P/E Lens
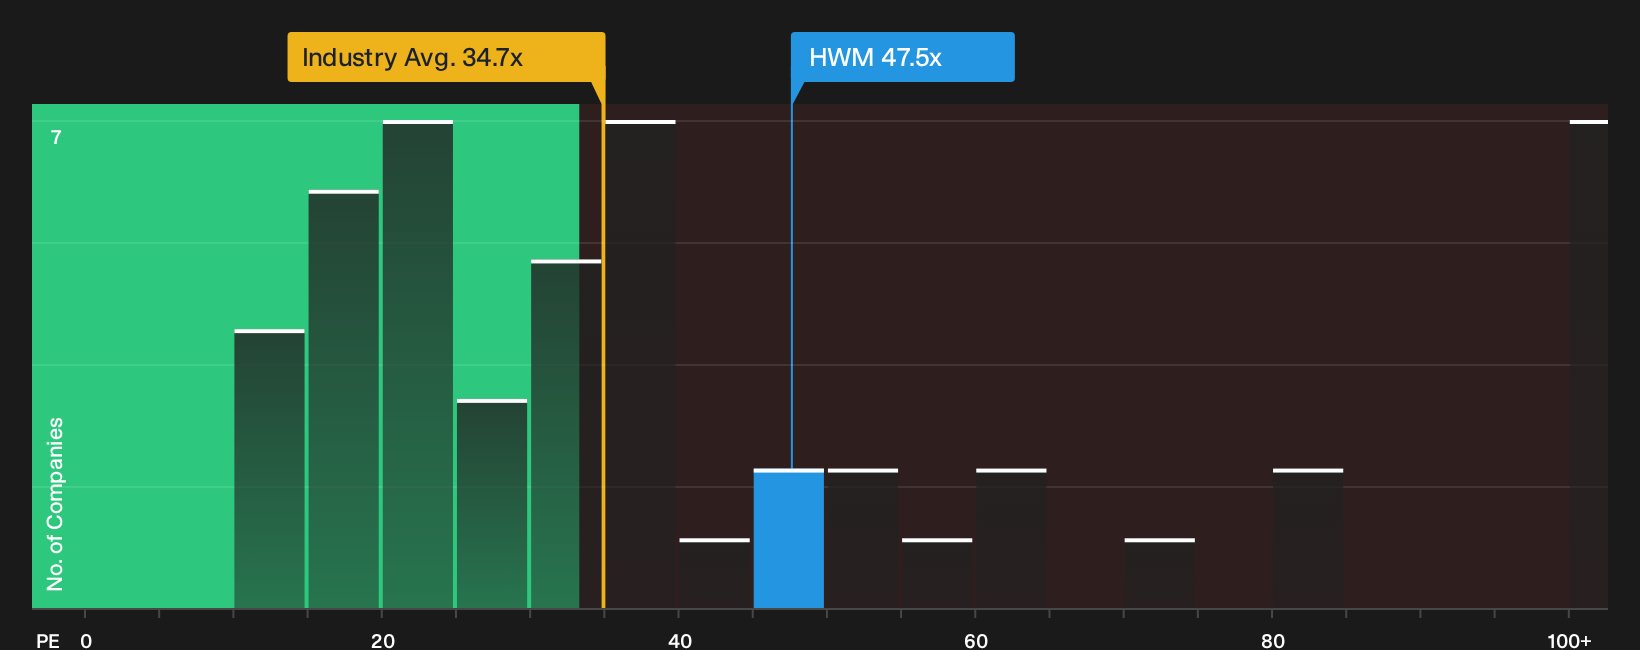
The story changes once you step away from fair value models and look at what the market is already paying for Howmet Aerospace. The shares trade on a P/E of 47.5x, which is significantly higher than the estimated fair ratio of 32.7x and well above both the peer average at 21.2x and the wider US Aerospace & Defense group at 34.7x. That gap points to a rich valuation that could amplify any disappointment in future execution. The key question is whether earnings quality and growth are sufficient to justify maintaining this premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on whether Howmet Aerospace is priced for perfection or still misjudged. Act while the data is fresh and weigh both sides with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Howmet Aerospace?
If you stop here, you only see part of the opportunity set. Use this pullback in Howmet Aerospace as a prompt to widen your watchlist and pressure test new ideas.
- Target stability first and scan a 31 resilient stocks with low risk scores that aims to hold up when markets turn choppy.
- Hunt for quality at a discount by reviewing a focused 20 high quality undiscovered gems with solid fundamentals that are not widely followed yet.
- Build staying power into your portfolio by checking a curated 8 dividend fortresses that combines higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com