
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Teradyne (TER) Fully Priced After New AI Test Launches?
Teradyne has ridden a powerful swing in enthusiasm around AI hardware testing and automation, and with the share price now reflecting that optimism in a big way, the live question is whether the current valuation can be backed up by its earnings power.
- Over the past 3 years, Teradyne has delivered a 318.1% return, which puts a lot of pressure on the profit stream to justify where the stock now trades.
- Recent moves to invest in Bright Machines and launch new AI focused test platforms such as Titan HP and Magnum E2 can influence how investors think about future profitability, capital intensity and the timing of cash flows.
- The analysts covering Teradyne have run their own numbers. See what analysts think Teradyne's shares could be worth.
The issue now is whether Teradyne's current share price can be supported by its earnings when viewed against the Fair Ratio benchmark.
If you are weighing Teradyne against other ways to play AI infrastructure hardware and testing, it can help to compare it with a wider set of 91 AI infrastructure stocks.
Is Teradyne Getting Expensive on Earnings?
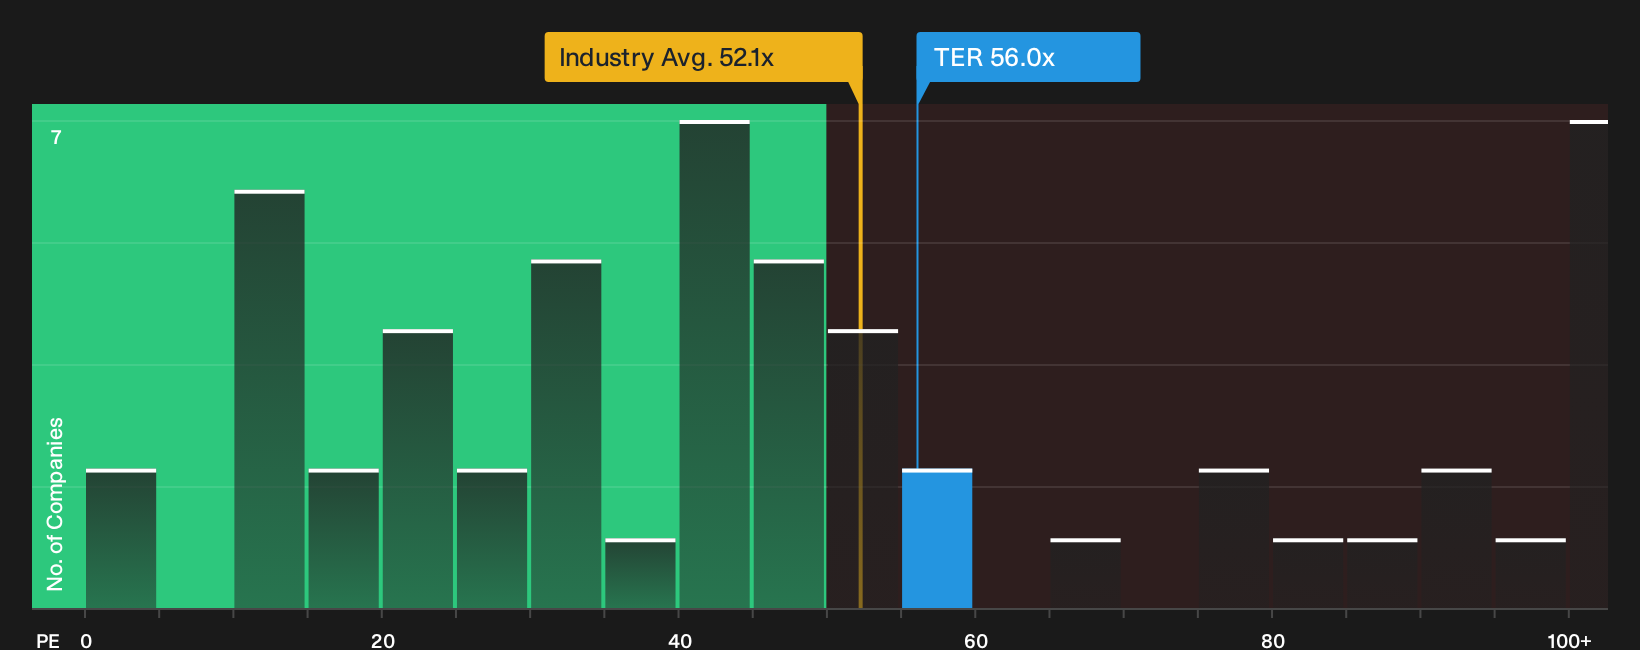
The P/E ratio fits Teradyne because investors are mainly paying for its earnings from test equipment and automation rather than asset backing. On this lens, Teradyne trades on a P/E of 56.0x, which is very close to the 56.2x average for its peer group and above the broader semiconductor sector on 52.1x. That places the stock at the higher end of the industry range, but not at an extreme premium to directly comparable companies.
The Fair Ratio model, which adjusts the P/E you might expect for Teradyne based on its margins, growth profile, size and risk, points to a lower multiple than the current 56.0x. Because the Titan HP and Magnum E2 launches have sharpened investor focus on AI related demand, the market is giving Teradyne a valuation that screens overvalued on this earnings yardstick. For anyone weighing an entry point, the key question is whether the current P/E fully reflects those AI hardware testing opportunities or stretches beyond what the projected earnings stream can comfortably support. Explore the numbers behind Teradyne's P/E valuation.
The Teradyne Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Teradyne pick up where the valuation puzzle leaves off. They spell out the future earnings, margin profile and growth pattern that would need to play out for Teradyne's current share price to look materially higher or lower. While a single ratio gives one number, Narratives set out the underlying path that number relies on so you can see whether reality is tracking the story over time on the Community page.
Bulls and bears on Teradyne are looking at the same AI heavy story and drawing very different conclusions about what is already priced in.
Bull case: 8% undervalued
"Teradyne continues to tie more than 60% of its revenue to AI-focused data center demand, with record Q2 2026 revenue of about US$1.33b…"
Discover why this Narrative puts Teradyne at 8% undervalued.
Bear case: 18% overvalued
"Although Teradyne is highly exposed to AI driven data center investment with more than 60% of Q2 2026 revenue tied to AI, the recent view that compute orders are front loaded…"
Explore why this Narrative puts Teradyne at 18% overvalued.
Teradyne’s price story is only complete once insider moves are on your radar
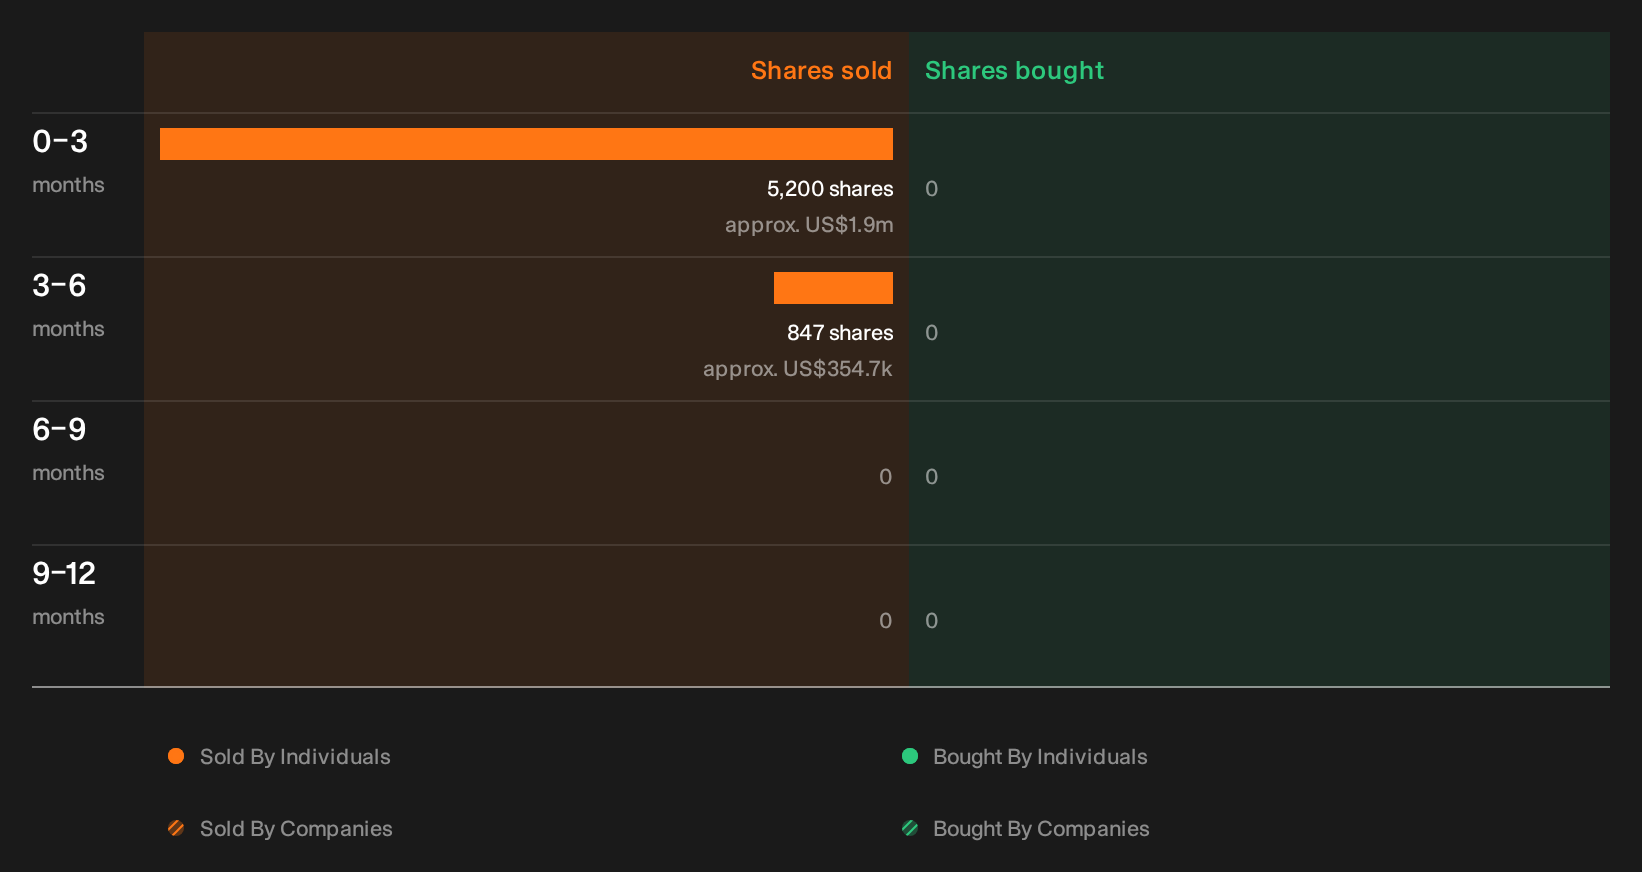
There is one more piece of the Teradyne puzzle that matters for many investors, which is who on the inside has been selling, how much, and what that activity might signal. See the recent insider selling flagged for Teradyne.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com