
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Oklo (OKLO) Rides Data Center Nuclear Focus, Is It 54% Undervalued?
Google's 20 year nuclear power deal with Constellation has pushed data center energy security into the spotlight, and Oklo (OKLO) is suddenly back on investor radar as a potential next generation supplier.
Oklo has become a focal point in this data center power story, yet the recent trading record shows how volatile sentiment remains. The share price is down 10.78% over the past 30 days and 52.67% year to date, alongside a 72.68% decline in 1-year total shareholder return, even after a very large 3-year total shareholder return gain of more than 2.5x. This signals that long term believers are sitting on notable profits while shorter term momentum is still fading.
Scan beyond Oklo and the Google deal by reviewing nuclear-focused peers in the 16 nuclear energy infrastructure stocks that could also be positioned for data center power demand.
Oklo now trades well below its recent highs, even as data center nuclear stays in focus. Is that slide mostly about the early stage business profile, or has sentiment simply swung too far and distorted valuation?
Most Popular Narrative: 54% Undervalued
On the most followed narrative, Oklo screens as deeply discounted, with a fair value estimate of $80.55 against the last close at $36.82, which raises an obvious question about what story the market is pricing in.
Oklo is another modular / small nuclear reactor maker, calling them Aurora Powerhouses. But it is not trying to sell reactors; it is trying to sell long-term electricity contracts while maintaining ownership of the plants. We are talking recurring, predictable revenue, not just selling equipment. AI data centers are also relevant here, which is considered a significant tailwind.
See why 60 investors see Oklo as 54% undervalued.
Result: Fair Value of $80.55 (UNDERVALUED)
Still, this bullish Oklo story can break if regulatory approvals stall again or if those long term AI power deals take much longer to translate into real revenue.
Find out about the key risks to this Oklo narrative.
Another View: Oklo Through A Simpler Market Lens
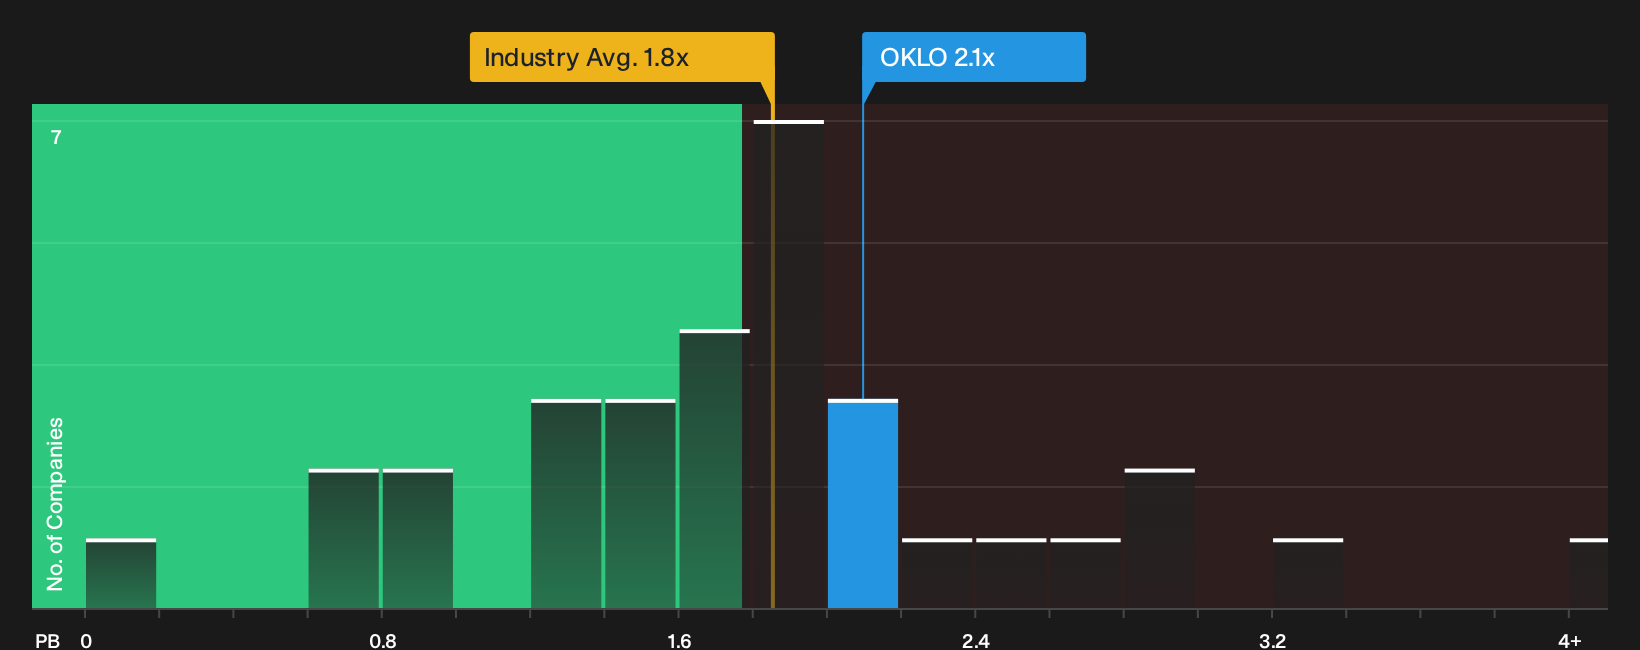
There is a very different message when you look at Oklo through a basic market multiple instead of a narrative fair value of $80.55. On P/B, Oklo trades at 2.1x, which screens as more expensive than both the US Electric Utilities industry and its peer average at 1.8x.
That higher P/B means investors are already paying a premium to the sector for a business that is still unprofitable, has only about $1.21 million of revenue, and is forecast to remain loss making over the next 3 years. If the market eventually leans back toward peer style pricing, that may limit the upside for the bullish story.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed views about the Oklo setup after all this. Act quickly to evaluate both the bullish and cautious perspectives against the underlying data by reviewing the 1 key reward and 6 important warning signs.
Looking for more investment ideas beyond Oklo?
Do not stop your research with Oklo. Broaden your watchlist now with other focused ideas that could sharpen your decisions and help you spot mispriced opportunities early.
- Target potential upside in quality companies that look mispriced by screening for 29 high quality undervalued stocks before the crowd catches on.
- Strengthen your income toolkit by reviewing rock solid payers in the 8 dividend fortresses that might fit a long term payout focus.
- Prioritise resilience by filtering for 31 resilient stocks with low risk scores so you are not caught off guard when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com