
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Did Tempus AI (TEM) Move Today?
Tempus AI (TEM) has been back in focus after two quick-fire updates, fresh 510(k) clearance for its ECG-MR heart tool and management’s decision to lift 2026 revenue guidance.
The two FDA and guidance catalysts affected a share price that had already moved higher over recent months, with Tempus AI posting a 90 day share price return of 14.39% and a 30 day gain of 8.87%. However, the 1 year total shareholder return is still down 31.86%, which points to momentum rebuilding from a low base rather than a long running rally.
Spot potential echoes of Tempus AI’s momentum shift by scanning the hand-picked 35 profitable AI stocks that aren't just burning cash, which already pair AI ambition with tangible earnings power.Tempus AI now appears to be a stronger operator with fresh products, new collaborations and raised guidance, yet the shares trade only fractionally below analyst targets. Is that renewed optimism already fully reflected in the price?
Most Popular Narrative: 7% Undervalued
Tempus AI closed at $70.35 against a widely followed fair value estimate of about $75.68, which frames the recent rally as only a partial catch up in the eyes of the most followed thesis.
This data moat is what makes the business interesting.
Tempus has accumulated tens of millions of de-identified patient records and hundreds of petabytes of clinical and molecular data, assets that would take competitors years and enormous investment to replicate.
See why 30 investors see Tempus AI as 7% undervalued.
Result: Fair Value of $75.68 (UNDERVALUED)
Still, the Tempus AI story can break if high expectations for its data flywheel fade, or if ongoing losses and debt pressures weigh more heavily on sentiment.
Find out about the key risks to this Tempus AI narrative.
Another View On Tempus AI’s Valuation
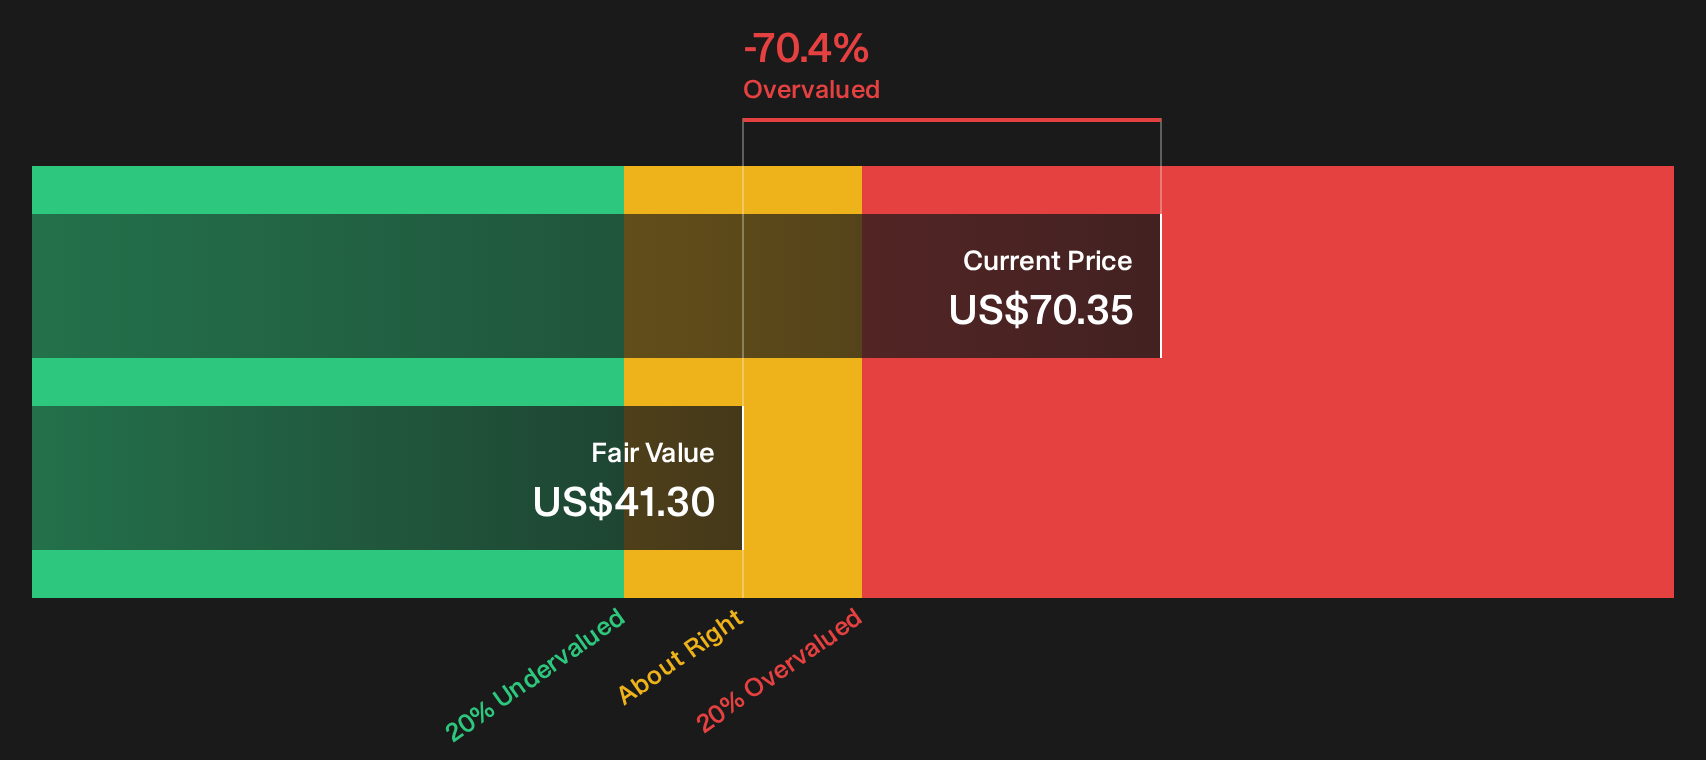
The future cash flow view paints a very different picture. Our DCF model estimates Tempus AI’s future cash flow value at about $41.30 per share, which implies the current $70.35 price screens as overvalued rather than 7% undervalued. Which story do you lean toward when the numbers disagree?
For investors who want to see how those cash flow assumptions are built and stress tested in detail, it is worth reviewing how the SWS DCF approach treats growth, margins and discount rates across different scenarios, then weighing that against personal expectations for Tempus AI’s business trajectory. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment on Tempus AI is clearly split, which is exactly why it helps to move quickly, inspect the underlying data for yourself, and let the mix of concerns and bright spots inform your own stance using the 1 key reward and 2 important warning signs.
Want more investment ideas beyond Tempus AI?
If Tempus AI sharpened your thinking, do not stop here. Cast the net wider and test your thesis against fresh opportunities across sectors and styles.
- Explore potential mispricings by scanning companies that combine quality fundamentals with their current valuations using the 29 high quality undervalued stocks.
- Build a steadier income base by reviewing established payers in the 8 dividend fortresses and see which payouts align with your risk comfort.
- Consider your downside protection by filtering for resilient businesses through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com