
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Shanghai Electric Group (SEHK:2727) Slides Further, Is The Valuation Gap A Warning Or An Opportunity?
Recent share performance and business scale
Shanghai Electric Group (SEHK:2727) has drawn fresh attention after a period of weaker share performance, with the stock down 3% over the past week and 9% over the past month.
The decline extends to the past 3 months and past year, where the share price has fallen 14.5% and 49.9% respectively, while year to date the stock is down 32.3%.
This weaker pricing sits against a large operating base, with revenue of CN¥135.7b across energy equipment, industrial machinery, and integrated services, and net income of CN¥1.4b.
Across those moves, Shanghai Electric Group has delivered weak short term share price momentum but a positive longer term total shareholder return over three and five years. Recent declines around the HK$2.795 level point to fading near term enthusiasm, which can reflect investors reassessing both growth prospects and risk around such a large capital equipment and services business.
Compare Shanghai Electric Group’s recent slide with other large capital equipment players by scanning the hand picked 43 power grid technology and infrastructure stocks that are shaping tomorrow’s grid infrastructure.
Shanghai Electric Group now trades well below both analyst targets and some intrinsic value estimates, after a sharp slide from around HK$2.80. Where might a fair range sit between those two reference points?
Price-to-earnings of 27.4x: Is it justified?
Shanghai Electric Group trades on a P/E of 27.4x at a last close of HK$2.795, which points to a richer valuation than many peers despite the weaker share performance.
The P/E ratio compares the current share price with earnings per share and effectively tells you how much investors are willing to pay for each unit of profit. For a large capital equipment and services group like Shanghai Electric Group, this ratio often reflects expectations around contract stability, project execution and how reliably earnings can be turned into cash.
There are a few cross currents here. Earnings for Shanghai Electric Group have grown 67.7% over the past year and margins have improved from 0.7% to 1%, and its earnings growth over the past year is higher than the 22.3% figure for the Hong Kong Electrical industry. At the same time, forecasts point to annual profit growth of 9.7% and revenue growth of 3.8%, which are both below the broader Hong Kong market forecasts, while Return on Equity sits at 3.4% and is expected to remain low.
The market is putting a far higher price on those earnings than on sector peers, with Shanghai Electric Group on 27.4x P/E compared with the Hong Kong Electrical industry average of 11.7x. It also trades well above an estimated fair P/E of 10.6x, a level the market could move towards if enthusiasm around the current earnings pace cools.
Explore the SWS fair ratio for Shanghai Electric Group.
Result: Price-to-earnings of 27.4x (OVERVALUED)
Still, Shanghai Electric Group faces pressure if profit growth stalls or project risks rise, which could quickly challenge support for a 27.4x P/E ratio.
Find out about the key risks to this Shanghai Electric Group narrative.
Another view on Shanghai Electric Group’s value
The P/E picture paints Shanghai Electric Group as expensive, yet the SWS DCF model points the other way. At around HK$2.80, the shares sit below an estimated future cash flow value of roughly HK$3.80, which frames the stock as undervalued on that lens. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
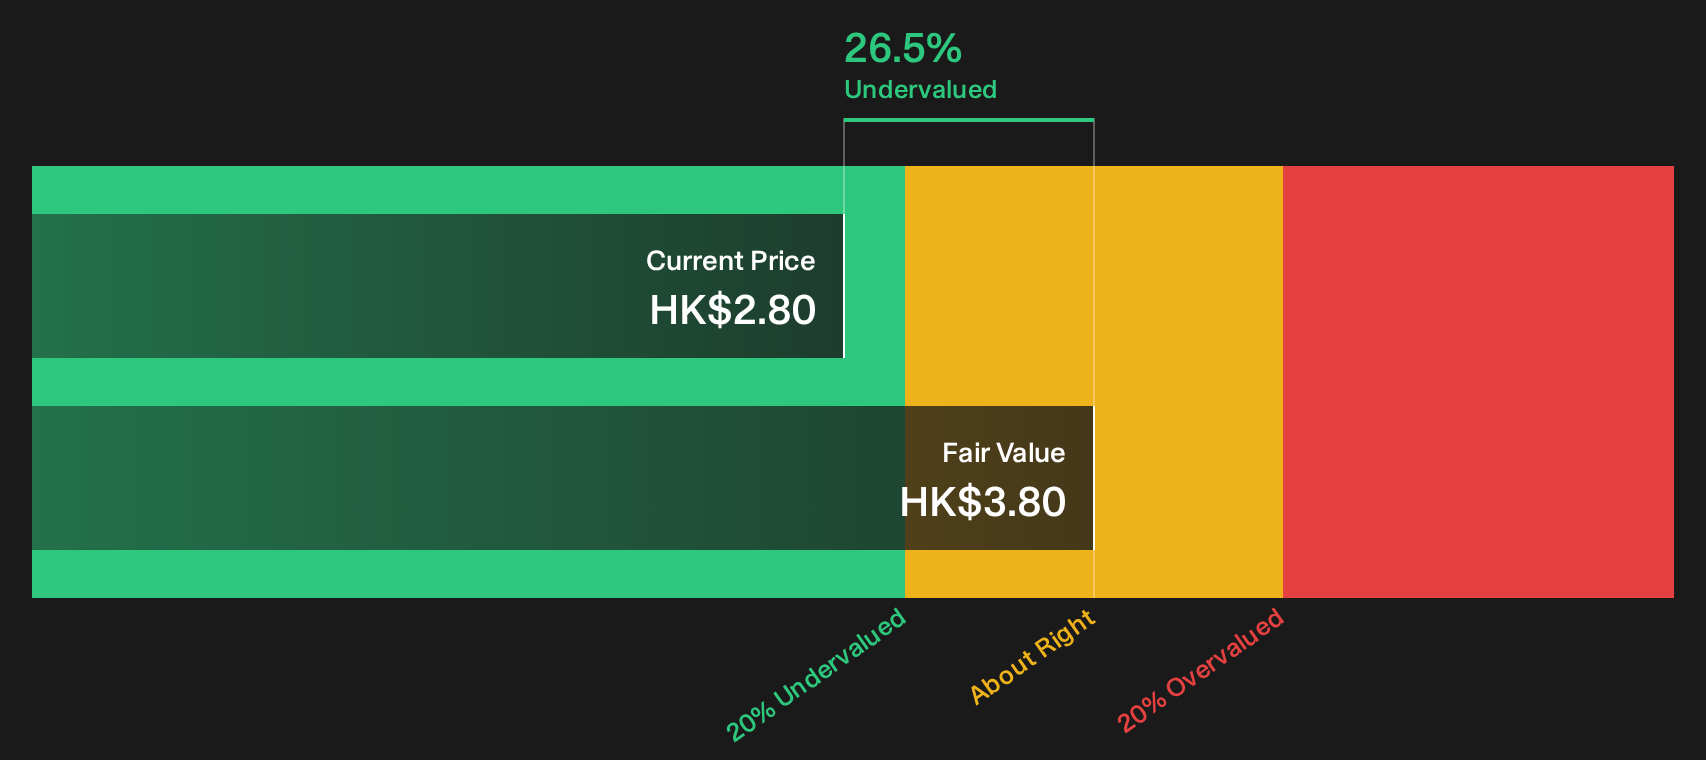
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shanghai Electric Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 185 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the mixed tone around Shanghai Electric Group matches your own read of the numbers and risks? Act quickly, review the full upside case, and weigh those signals against the 3 key rewards.
Looking for more Shanghai Electric Group sized ideas?
Do not stop with Shanghai Electric Group. Use the same disciplined lens across fresh opportunities so you keep your watchlist stocked instead of reacting late.
- Target potential mispricings by scanning a focused set of under-the-radar value candidates through the 185 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by filtering for companies on the 225 resilient stocks with low risk scores.
- Hunt for tomorrow's quiet overachievers by reviewing the carefully curated 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com