
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
GAAP Profit Might Change The Case For Investing In Tuya Stock (TUYA)
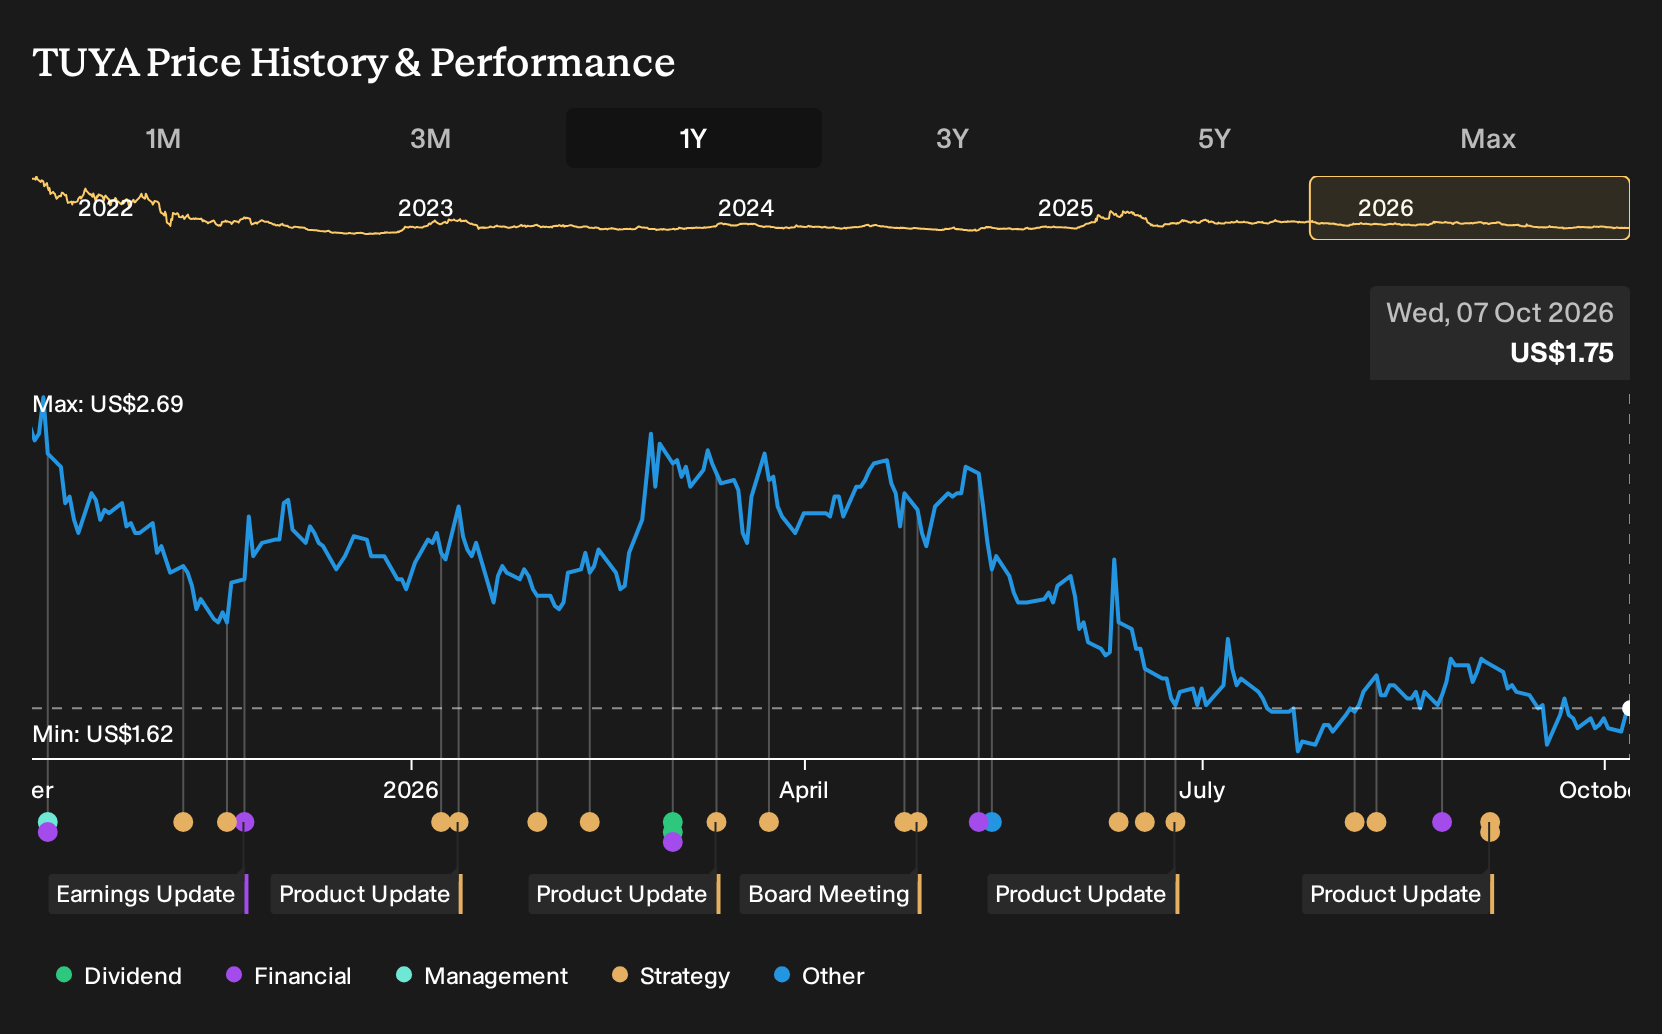
- Tuya recently reported that operating margin for the twelve months to Q2 2026 reached 8.4%, compared with 3.6% a year earlier, and that FY 2025 GAAP results showed a net profit of US$58 million as the business leaned on its cloud agnostic SaaS platform for smart devices.
- The move toward software subscriptions positions Tuya less as a hardware dependent IoT player and more as a recurring revenue SaaS platform, which can influence how investors evaluate its earnings quality and sensitivity to hardware cycles.
- This article now examines how Tuya's move to GAAP profitability through SaaS subscriptions could reshape the existing investment narrative.
Scan beyond Tuya's shift to SaaS and see how other recurring revenue platforms with strong fundamentals stack up in our hand picked 20 high quality undiscovered gems.
Tuya Investment Narrative Recap
To own Tuya, you need to believe the SaaS pivot can keep tightening operating discipline while the IoT device market stays healthy enough to feed its cloud platform. The recent move to an 8.4% operating margin and GAAP net profit of US$58 million suggests the model now supports self funded growth. The key near term catalyst remains execution in higher margin software, not hardware volume swings.
The biggest risk still sits in Tuya's exposure to cost sensitive device categories and global trade friction, which can hit customer budgets and slow new deployments. Profitability does not remove that pressure. It gives the company more cushion if tariffs, supply chain complexity or hyperscaler competition weigh on new contracts.
The headline announcement that Tuya reached GAAP profitability in FY 2025, with US$58 million of net income and an 8.4% trailing twelve month operating margin to Q2 2026, ties directly into the SaaS story investors have been watching. It confirms that the recurring software mix is now meaningful enough to support positive earnings, not only adjusted metrics.
For catalysts, that matters because a profitable, cloud agnostic platform can lean harder into AI features and value added services without relying solely on external capital. The same update also sharpens the risk picture. Any slowdown in international IoT rollouts, or tougher pricing as hyperscalers push competing platforms, would now show up against a higher margin base and could test how durable Tuya's new earnings profile is.
What The Tuya Forecasts Are Really Asking You To Believe
Tuya's narrative projects US$466.4 million revenue and US$92.7 million earnings by 2029. That implies 12.4% yearly revenue growth and an earnings increase of about US$30 million from US$62.6 million today.
Uncover why Tuya's fair value indicates a 95% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate, more optimistic Tuya story leans heavily on AI companion hardware as the real swing factor. Those bullish analysts were already penciling in about US$524.1 million of revenue and US$112.7 million of earnings by 2029, compared with US$466.4 million and US$92.7 million in the baseline set, before this profitability news even landed. You can treat this fresh margin update as a chance to compare those pre news assumptions with your own and explore how both narratives might evolve from here.
Explore 4 other Tuya fair value estimates, including one that suggests as much as 182% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tuya research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Tuya. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tuya's overall financial health at a glance.
Looking For More Tuya Investment Ideas?
If Tuya's SaaS turn has you rethinking how recurring revenue shapes risk and reward, it can help to line it up against other businesses with different income profiles and balance sheets. Use the Simply Wall St Screener to compare Tuya with a wider field so you can stress test your thesis against companies at different stages of profitability, leverage, and income stability.
- For investors who want potential mispricings with fundamentals to back them up, start with a curated set of 29 high quality undervalued stocks that pair quality metrics with discounted prices.
- If capital preservation sits high on your list, focus on steadier profiles through a 31 resilient stocks with low risk scores that filters for resilient balance sheets and lower risk scores.
- When you care most about financial strength backing every earnings line, compare Tuya with a list of solid balance sheet and fundamentals (25 results) and see which companies look built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com