
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AMD Stock Isn’t Undervalued, but Wall Street May Be Underestimating a Key Opportunity
More good news for the Advanced Micro Devices (AMD) bulls—BNP Paribas analyst Karl Ackerman just boosted the firm's price target by 60% to $960. According to Ackerman, the reason for the increase is the growing demand for CPUs as AI workloads continue to grow.
What is worth mentioning here is that, despite the price target increase, Ackerman kept his “Neutral” rating. Given that AMD moves away from being a pure chip designer, the introduction of the Helios AI platform, the ROCm software ecosystem improvement, and the expansion of the list of key AI customers become crucial things for the company. However, given that the stock price is already close to its 52-week high amidst its impressive rally, the questions that arise for investors are the sustainability of future growth in the context of such valuation.
To my mind, the current valuation of the stock does not allow saying that it is undervalued. Undervalued, however, can be called the scope of AMD's AI opportunity. Investors concentrate much on AMD's competition with Nvidia (NVDA) in GPUs, while growing CPU opportunity can become the other source of the AI-driven growth.
About AMD Stock
Advanced Micro Devices, a California-based company, is engaged in designing high-performance CPUs, GPUs, adaptive computing products, and AI accelerators. Currently, the market capitalization is estimated at $1.06 trillion, and AMD stock sits at about $634, which is slightly lower compared to the 52-week high of $658.52 and 237% higher compared to the 52-week low of $188.22.
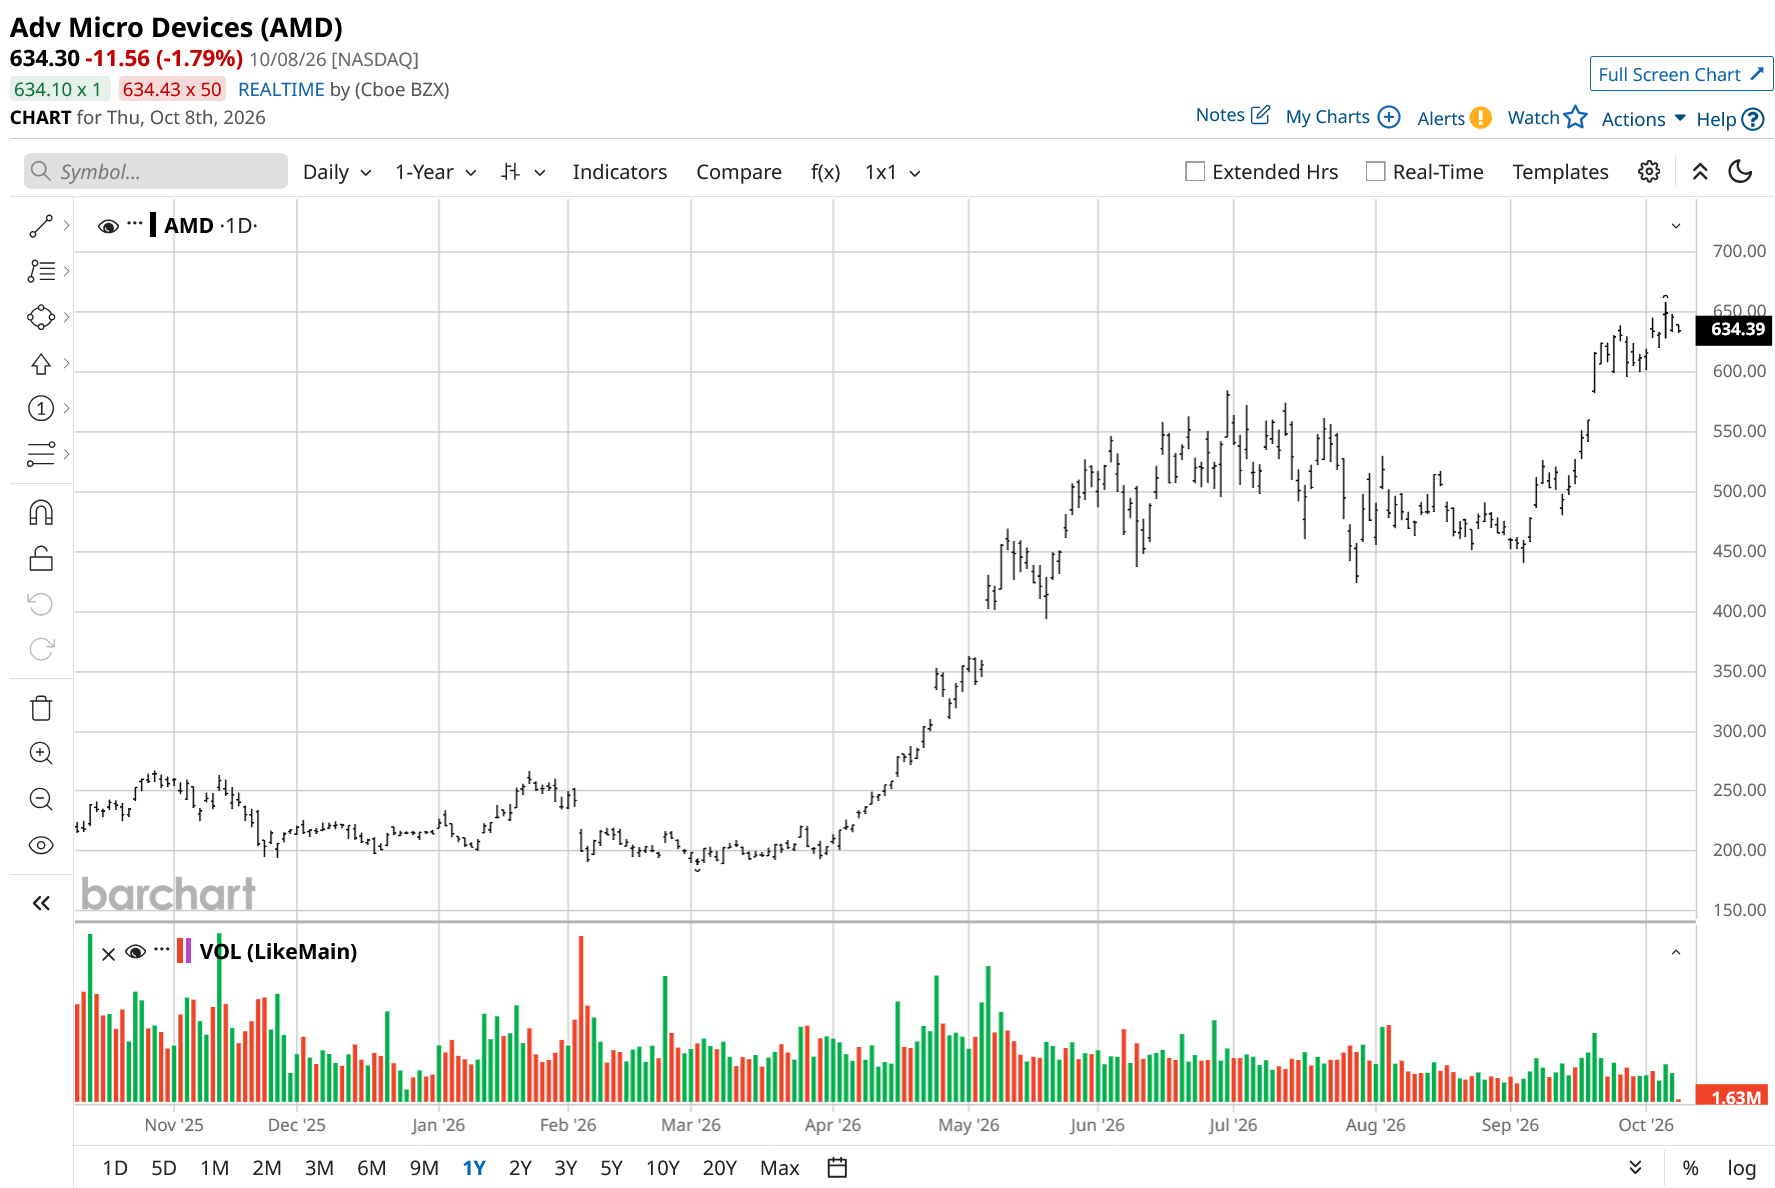
The growth of the stock is coupled with its high price-earnings multiple (P/E) amounting to 98.63x and even higher price-sales (P/S) ratio, at 29.77x. This high valuation leaves no room for error and clearly shows what market expectations are towards the growth of earnings of the company. Thus, AMD needs to show good results in terms of earnings' growth due to its growing AI opportunity to live up to expectations.
Thus, I would not say that the AMD stock is cheap at current levels. A forward P/E approaching 100x implies plenty of optimism. However, it does not mean that the underlying growth opportunity of the company is fully understood, especially in case the demand for AMD accelerators expands beyond GPUs.
AMD Reports Record Results for Q2
In Q2 of 2026, Advanced Micro Devices reported record results with revenue of $11.5 billion and year-over-year (YoY) growth of 50%. The company reported non-GAAP EPS at $1.66 and non-GAAP operating income of $3.1 billion. The biggest contribution here was done by the Data Center segment, which generated the bulk of the revenue. It accounted for 58% of the total company's revenue and more than doubled YoY.
For the second half of the year, AMD has several growth drivers going for it. Sales of EPYC CPUs continue to accelerate, sales of Instinct accelerators scale, and the Helios platform ramps up. Moreover, according to management of the company, sales of the Data Center segment should accelerate in the second half of 2026.
It appears that the increased optimism of BNP Paribas is caused by all these factors. Ackerman expects AMD to take market share in the agentic CPU market that is expected to grow to $245 billion by 2030. In my opinion, here AMD may be underestimated. Most of the AI investment narrative focuses on GPUs; however, the growth of AI agents could increase the demand for AMD's CPUs. If the market evolves as BNP Paribas forecasts, AMD does not need to take GPU market share from Nvidia to get substantial AI-driven growth. Furthermore, Ackerman considers Helios to be a credible competitor to Nvidia's AI infrastructure based on 14 gigawatts of commitments.
However, the opportunities of the company are not limited by CPUs and GPUs only. ASICs and XPUs will account for 25% of the total accelerator market. The cooperation of AMD with Cerebras (CBRS) includes both the Helios platform and wafer-scale inference technology. Finally, the acquisition of Taalas will provide the company with some more engineering know-how and intellectual property for developing specialized low-latency AI silicon.
But most importantly, AMD already has multi-gigawatt relationships with OpenAI, Meta (META), and Anthropic. Based on the expectations of BNP Paribas, AMD will be able to capture 8% of the GPU market, which is worth over $1 trillion by 2030. This will become another growth driver of the company if done correctly.
What Do Analysts Expect for AMD Stock?
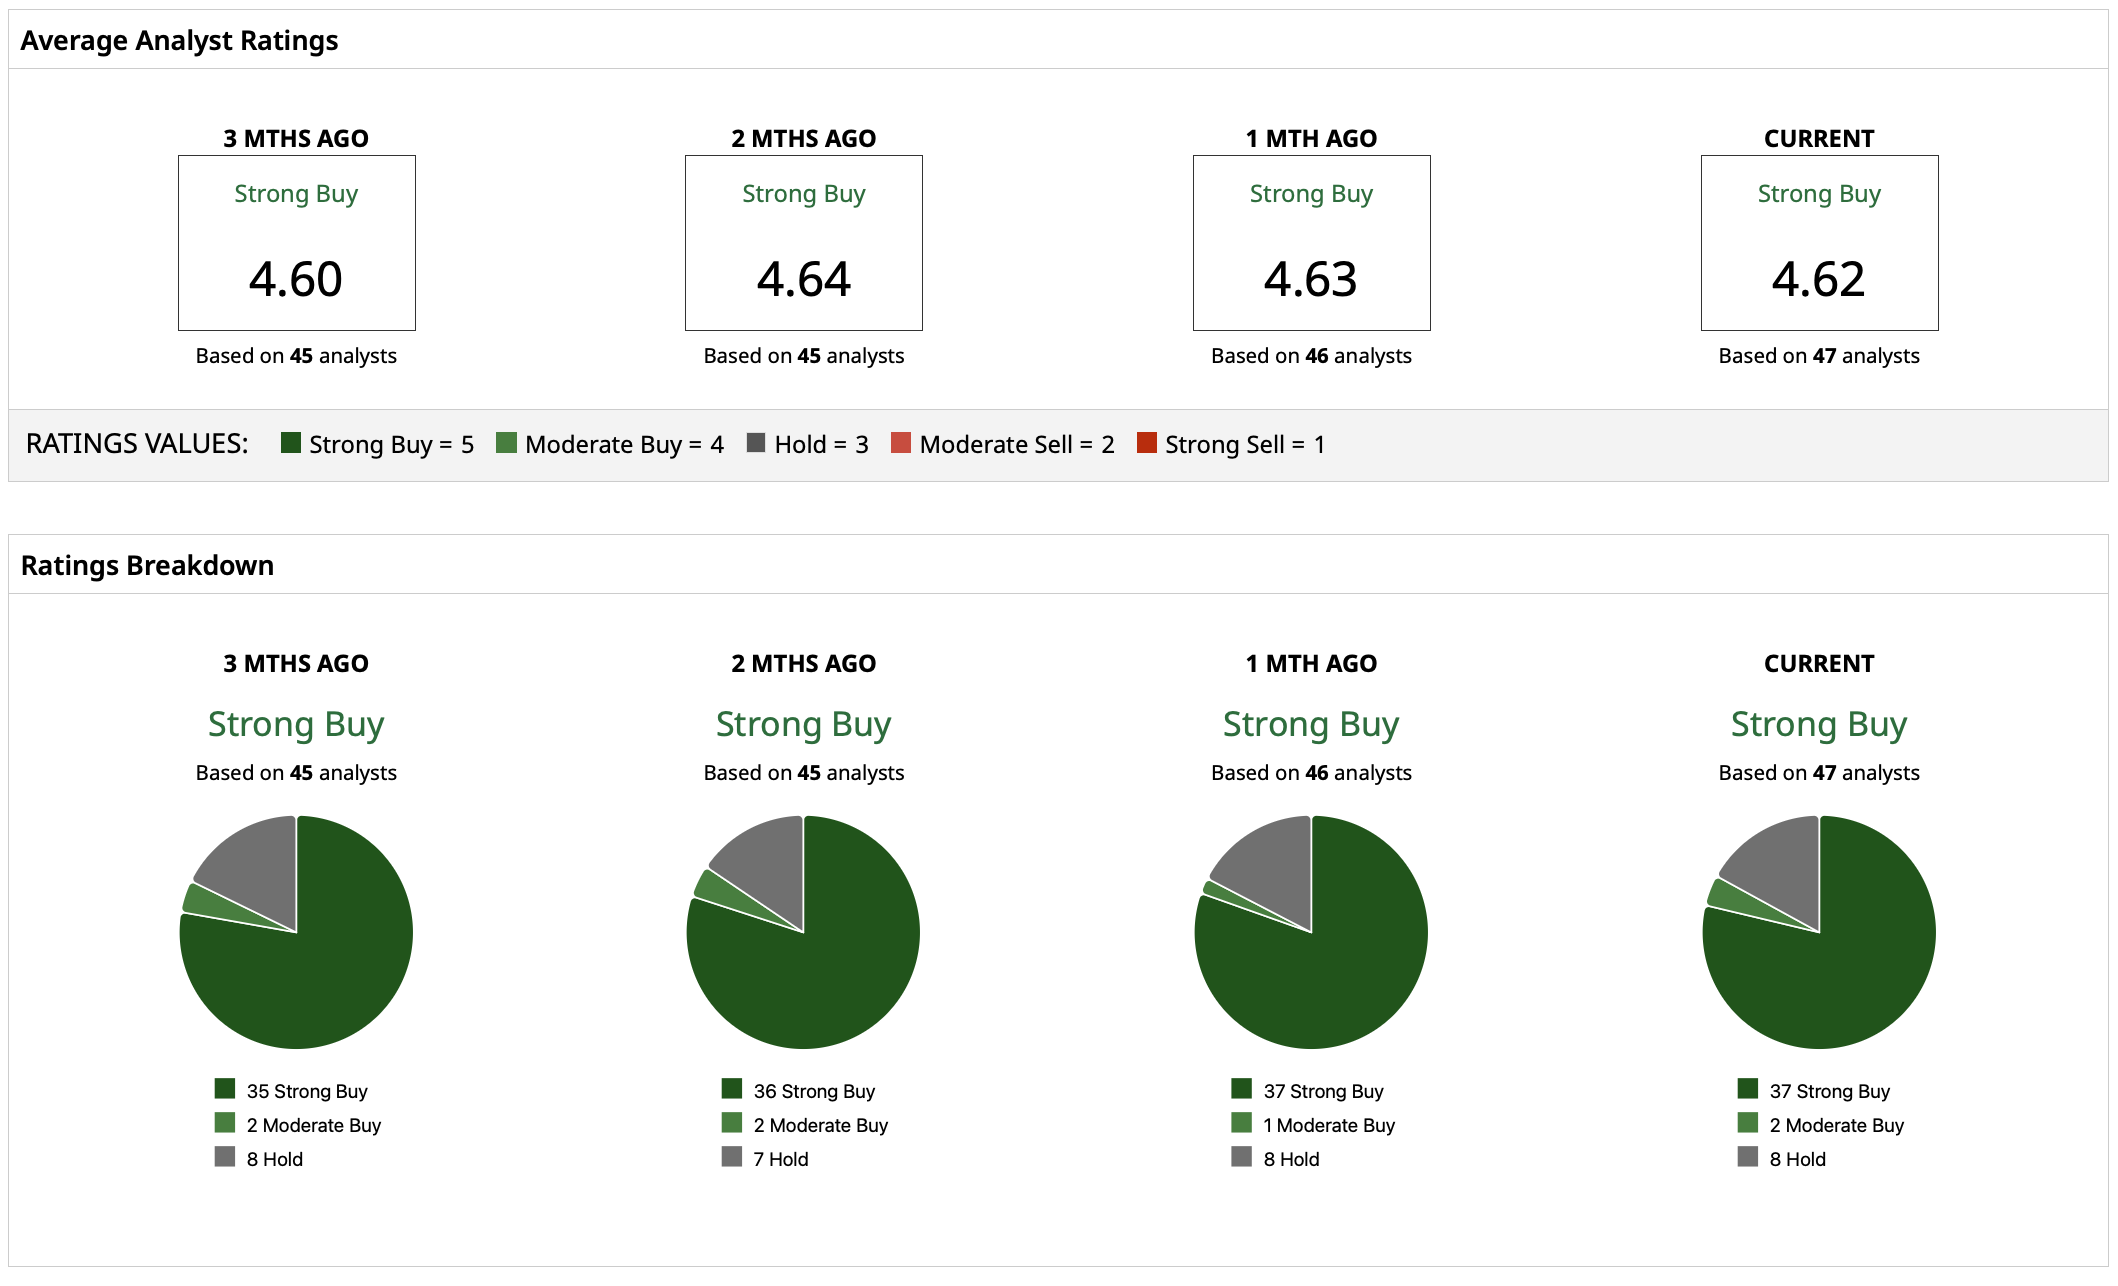
The expectations of analysts are rather high for AMD, assigning the “Strong Buy” rating consensus. However, given the fast appreciation of the stock, the gap between the current price and the consensus price target has decreased significantly. The mean price target of AMD stock is estimated at $652.86, the highest one being $1,250, and the lowest one being $430. Given the current price of $634.30, its mean target represents a potential upside of just 3%. On the other hand, BNP Paribas' target of $960 is more optimistic, implying the potential upside of 51%.
On the date of publication, Yiannis Zourmpanos had a position in: AMD . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.