
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Earnings Preview: What to Expect From Centene's Report
Centene Corporation (CNC), headquartered in Saint Louis, Missouri, operates as a healthcare enterprise that provides programs and services to under-insured and uninsured families, and commercial organizations. Valued at $32.1 billion by market cap, the company’s specialty services include medicaid and medicare health plans, treatment compliance, and nurse triage. The largest Medicaid managed care organization is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Tuesday, Oct. 27.
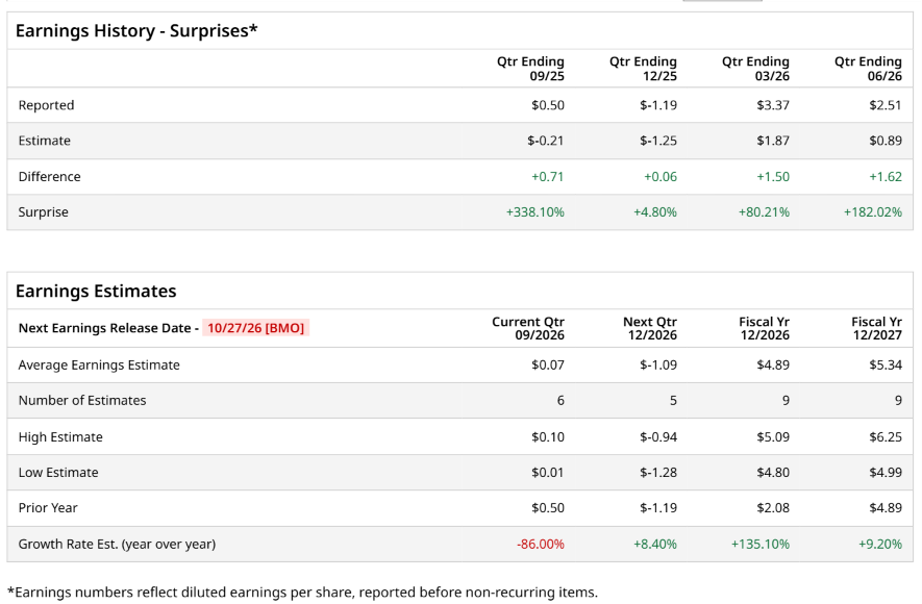
Ahead of the event, analysts expect Centene to report a profit of $0.07 per share on a diluted basis, down 86% from $0.50 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Centene to report EPS of $4.89, up 135.1% from $2.08 in fiscal 2025. Its EPS is expected to rise 9.2% year over year to $5.34 in fiscal 2027.
CNC stock has outperformed the S&P 500 Index’s ($SPX) 16.2% gains over the past 52 weeks, with shares up 69.2% during this period. Similarly, it outperformed the State Street Health Care Select Sector SPDR ETF’s (XLV) 17% returns over the same time frame.
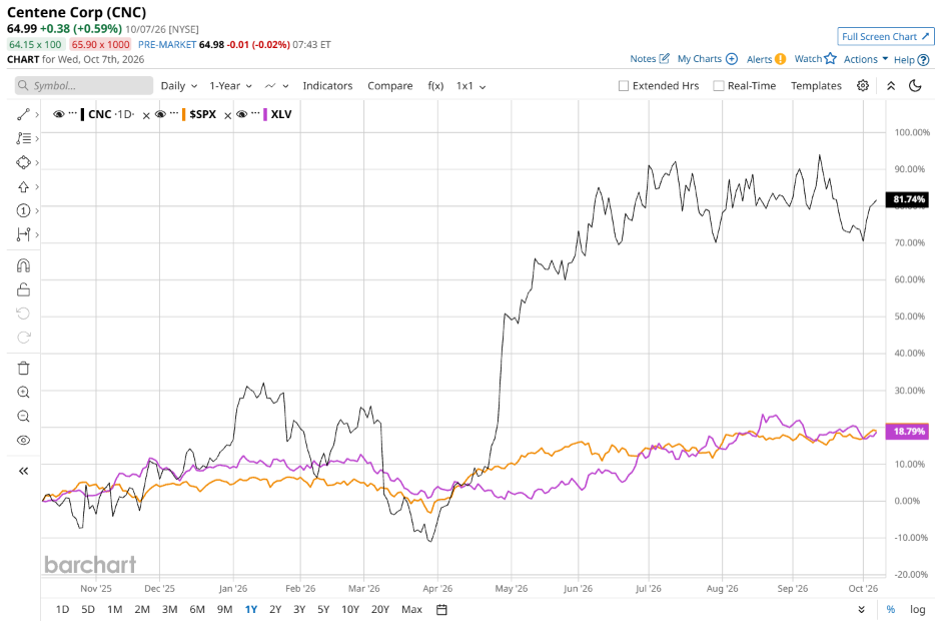
CNC’s solid performance was driven by operational streamlining, AI-driven efficiency gains, and strong execution in its core segments. The Marketplace business saw significant margin recovery due to lower medical costs and favorable risk adjustments among Silver tier members, while the Medicare segment remained stable through improved PDP margins and a strategic focus on dual-eligible populations. Despite raising its full-year guidance on these strong fundamentals, market sentiment was dampened by sharper-than-expected Medicaid membership losses caused by state eligibility tightening and upcoming federal OB3 verification rules. Moving forward, Centene’s sustained growth will rely on its ability to maintain strict cost discipline, expand AI integration, and navigate ongoing Medicaid attrition and regulatory headwinds.
Analysts’ consensus opinion on CNC stock is reasonably bullish, with a “Moderate Buy” rating overall. Out of 21 analysts covering the stock, eight advise a “Strong Buy” rating, 12 give a “Hold,” and one advocates a “Strong Sell.” CNC’s average analyst price target is $71.84, indicating a potential upside of 10.5% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.