
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Helios Technologies (HLIO) Cheap After Its Dividend Decision?
Helios Technologies (HLIO) drew fresh attention after its board affirmed a quarterly cash dividend of $0.12 per share, payable on October 26, 2026, to holders of roughly 33.0 million shares.
Despite the dividend decision, Helios Technologies’ share price has been choppy, with the stock down about 3% over the past day and roughly 14% over the past 90 days. It still shows a 26.6% year to date share price return and a 38% total shareholder return over the past year, which signals past momentum that has recently cooled as investors reassess both growth prospects and risk around the current US$69.24 level.
Scan how Helios Technologies compares with other industrial companies that pair dividends with recent share price swings by reviewing our curated list of list of solid balance sheet and fundamentals (25 results).
For Helios Technologies, this mix of a steady dividend and a volatile share price raises a simple issue. Are investors reacting to the underlying earnings power, or has sentiment just swung ahead of what the fundamentals support?
Most Popular Narrative: 27% Undervalued
Against the last close at $69.24, the most followed narrative for Helios Technologies pegs fair value near $94.67. This frames the recent pullback as a pricing gap rather than a simple loss of confidence.
Strong free cash flow, evidenced by record Q2 2026 operating cash flow of US$42 million and free cash flow of US$31 million, together with net debt-to-EBITDA at 1.4x, gives Helios Technologies room to increase capex, pursue acquisitions, and return more capital to shareholders. This can influence future EPS and support higher cash returns.
See why 5 investors see Helios Technologies as 27% undervalued.
Result: Fair Value of $94.67 (UNDERVALUED)
Still, the narrative around Helios Technologies could shift quickly if cyclical construction and recreational demand weakens again or if cost pressures pinch those greater than 20% EBITDA margins.
Find out about the key risks to this Helios Technologies narrative.
Another View On Helios Technologies’ Valuation
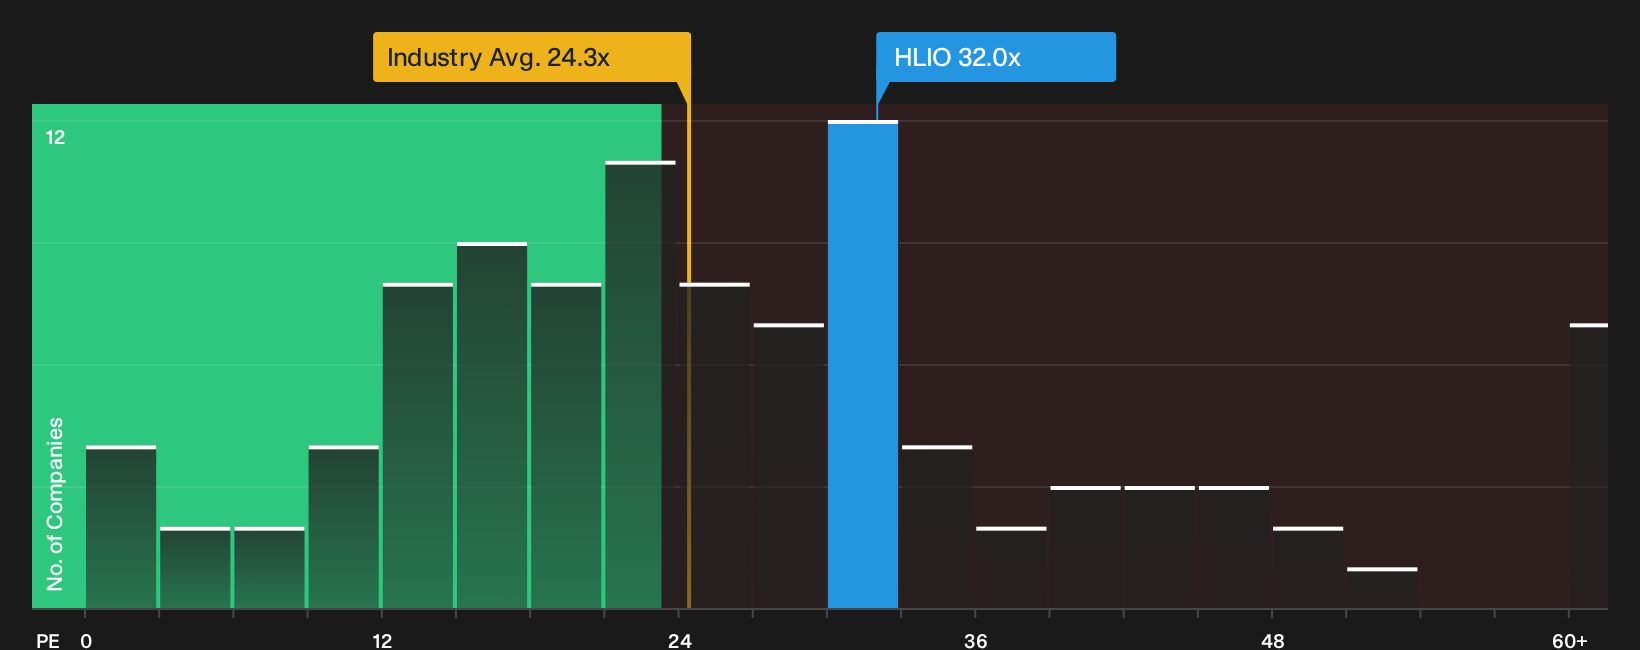
The analyst narrative sees Helios Technologies as undervalued against a $94.67 fair value, yet the current P/E near 32x tells a different story. That multiple sits above the US Machinery industry at 25x and the fair ratio of 21.2x, which points to less room for error if earnings disappoint. Which signal do you trust more right now?
For investors comparing these yardsticks, the gap between today’s valuation and that lower fair ratio highlights how quickly sentiment could shift if expectations change. It is worth stress testing the assumptions behind each model before leaning on one view as your anchor. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Helios Technologies so far. If you want to move quickly and form your own view, start by weighing its 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Helios Technologies?
If Helios Technologies has sharpened your focus, do not stop here. Fresh ideas often come from comparing it with other businesses that offer different risk and reward profiles.
- Target resilient cash generators by scanning companies with strong finances and durable fundamentals through our list of solid balance sheet and fundamentals (25 results).
- Spot potential mispriced opportunities by reviewing a curated set of compelling value candidates using the 29 high quality undervalued stocks.
- Build a steadier income stream by assessing companies that combine higher yields with robustness in their payouts via the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com