
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Brinker International (EAT) Could Be 29% Undervalued As Its Pullback Reshapes Value
Brinker International Stock Reaction
Brinker International (EAT) has been drawing fresh attention after a sharp pullback, with the share price down about 20% over the past month even as year to date returns remain positive.
The pullback follows a strong run. Brinker International’s year to date share price return is 22.3%, and its 1 year total shareholder return is 52.04%, contrasting with the recent 30 day share price decline of 19.51%.
Capitalize on Brinker International's sharp pullback by comparing it with a hand picked 29 high quality undervalued stocks that also pair solid fundamentals with potential mispricing.Brinker International has a recognizable restaurant portfolio and positive 1 year and year to date returns, yet the recent drop reshapes the entry point. Are investors paying a fair price for that resilience, or overcompensating for the setback?
Most Popular Narrative: 29% Undervalued
Brinker International's most followed narrative pegs fair value at $262.59 compared with the last close at $185.31. This implies investors are paying a discount that hinges on Chili's unit economics and value positioning holding up.
Brinker International is extending its menu work at Chili's, including upgrades in core items and beverages, on top of a higher earning restaurant model where AUVs have reached about $5 million and restaurant operating margin has widened by 660 basis points. This can support further revenue and earnings growth if traffic and mix benefits continue to scale.
See why 30 investors see Brinker International as 29% undervalued.
Result: Fair Value of $262.59 (UNDERVALUED)
Still, Brinker International’s narrative can be knocked off course if Chili’s value push fails to offset cost inflation, or if Maggiano’s ongoing traffic softness persists.
Find out about the key risks to this Brinker International narrative.
Another View: Brinker International Through Cash Flows
While the popular Brinker International narrative leans on a $262.59 fair value from analyst targets and implied P/E, the Simply Wall St DCF model lands lower at $168.67 per share. That points to the stock trading above the modelled future cash flows, which raises a simple question: Are you more comfortable trusting earnings multiples or cash generation assumptions?
Look into how the SWS DCF model arrives at its fair value.
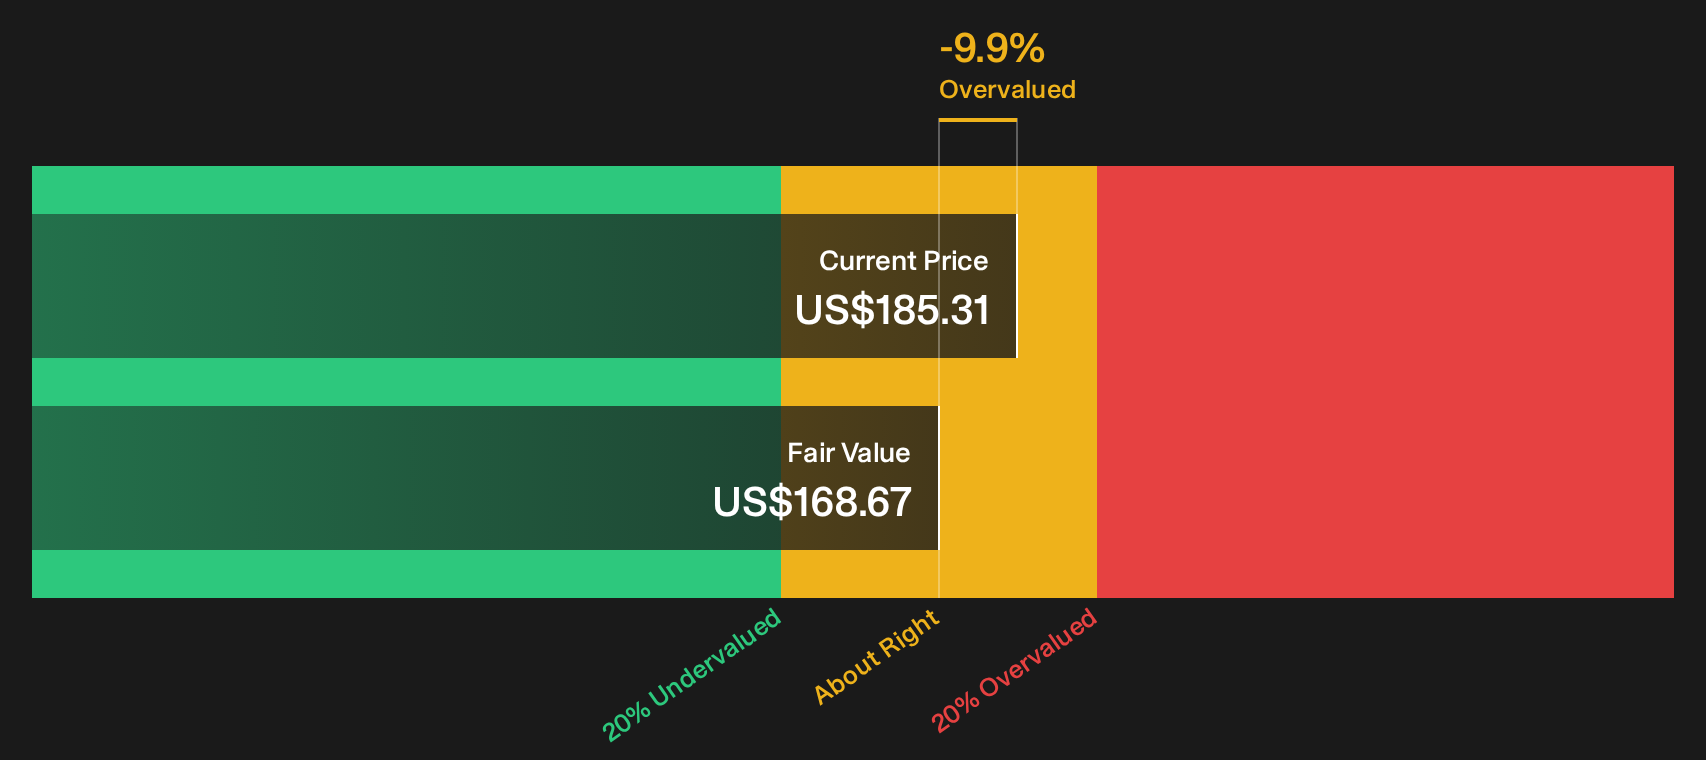
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Brinker International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Brinker International so far. If you want to move ahead of the next sentiment swing, compare the 5 key rewards and 2 important warning signs with your own read of the numbers.
Looking for more ideas beyond Brinker International?
Brinker International gives you one story. A broader watchlist gives you options when sentiment shifts, and that is where the Simply Wall St screener helps.
- Hunt for mispriced quality by scanning a 29 high quality undervalued stocks that couples solid balance sheets with what could be discounted market expectations.
- Strengthen your portfolio backbone with a list of solid balance sheet and fundamentals (25 results) that highlights companies carrying manageable debt and healthy financial cushions.
- Surface off-the-radar potential through a 20 high quality undiscovered gems that filters for strong fundamentals before wider attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com