
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Insight Enterprises (NSIT) Fully Priced Following Its Zacks Upgrade?
Analyst upgrade puts Insight Enterprises in focus
Insight Enterprises (NSIT) moved onto investor watchlists after Zacks raised its rating on the stock to Rank #1, citing a recent upward trend in earnings estimates over the past 3 months.
At a share price of $160.13, Insight Enterprises has seen strong momentum build, with a 90.72% year to date share price return and a 44.69% total shareholder return over the past year, even after a recent 30 day pause.
Scan how Insight Enterprises compares with other fast moving IT and AI infrastructure plays by reviewing the hand picked 91 AI infrastructure stocks in the same space.
Insight Enterprises has already rewarded early entrants, yet the recent 30 day stall raises a practical question. Does that pause offer a clearer entry now, or suggest waiting until valuation lines up more clearly?
Most Popular Narrative: 2% Undervalued
On the most followed view, Insight Enterprises carries a fair value of $163.75 versus a last close of $160.13. This puts the current rally in context as largely in line with that assessed worth rather than wildly out of step.
The company’s pivot from legacy partner programs toward higher margin cloud, managed services and AI focused consulting is now reinforced by cloud gross profit rising into the high double digits in recent quarters and by higher gross margin guidance. Together these factors point to a sustained mix shift that could support gross margin and adjusted EPS growth.
See why 3 investors see Insight Enterprises as 2% undervalued.
Result: Fair Value of $163.75 (UNDERVALUED)
Still, the Insight Enterprises story depends on clients maintaining IT and AI infrastructure spending and on vendor program changes not squeezing gross profit harder than expected.
Find out about the key risks to this Insight Enterprises narrative.
Another View: What P/E Says About Insight Enterprises
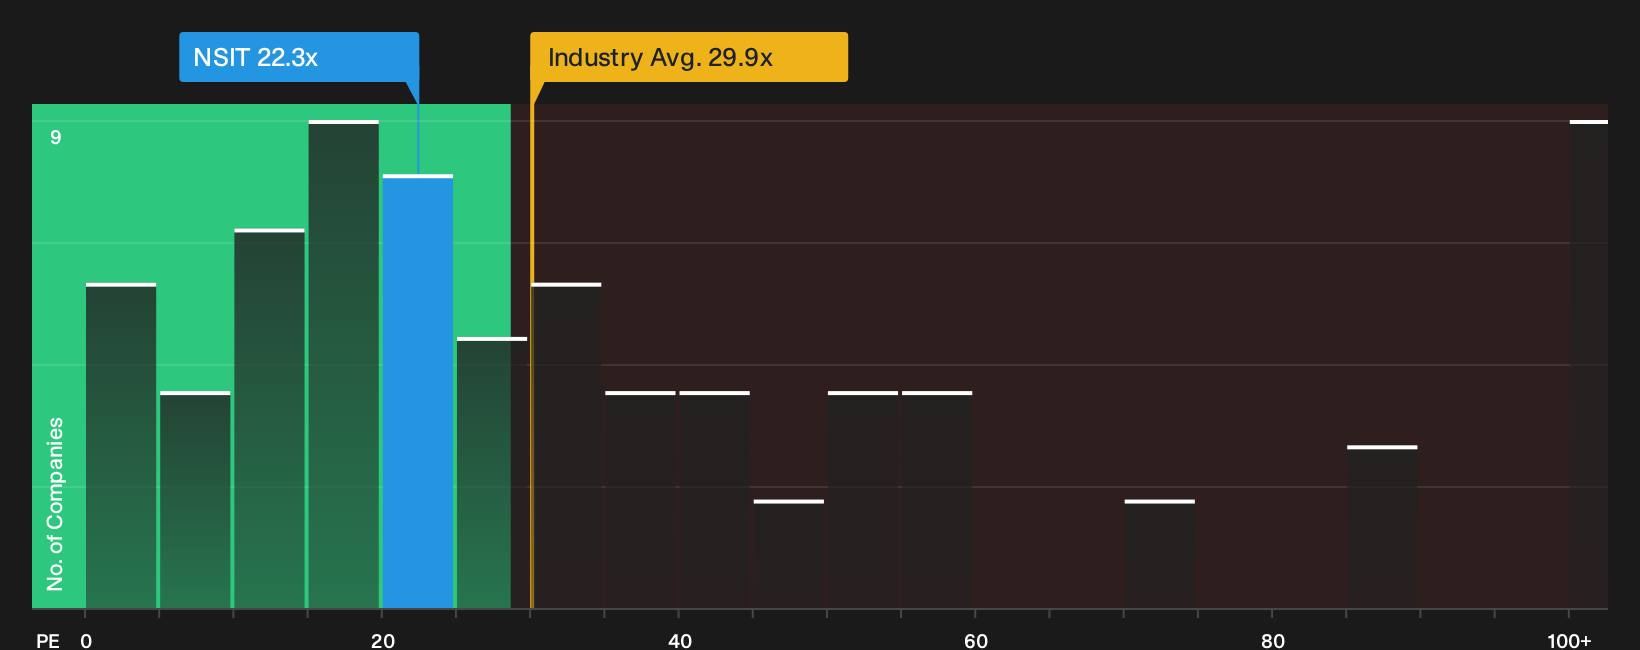
Analysts calling Insight Enterprises 2% undervalued on fair value see a different message once the current P/E is brought into the picture. The stock trades on 22.3x earnings, richer than peer averages at 20.9x, yet still below a fair ratio estimate of 30.6x. That mix of premium pricing versus peers and a gap to the fair ratio raises a simple question: is this more about upside that is not fully priced in, or about limited room for error if expectations slip?
For a closer look at how these earnings multiples stack up, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Insight Enterprises are clear, which is exactly why it helps to test the numbers yourself and move quickly from headlines to your own evidence based view. For a balanced snapshot of both sides of the story, start with 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Insight Enterprises?
If Insight Enterprises is on your radar, broadening your watchlist now can help you spot opportunities earlier instead of reacting once prices have already moved.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (25 results) that combine financial strength with room for potential re rating.
- Hunt for mispriced quality by checking the 29 high quality undervalued stocks that highlights businesses with solid fundamentals trading below assessed worth.
- Build a cash flow focused watchlist by reviewing the 8 dividend fortresses that concentrates on higher yielding payouts with an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com