
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Synaptics (SYNA) Following Onsemi Bid Is The Stock Fully Valued
Onsemi has revised its proposed acquisition of Synaptics (SYNA) into a US$5.7b all-cash offer, removing stock dilution and giving Onsemi full ownership of Synaptics' connectivity and AI processing portfolio.
Synaptics' share price has surged recently, with a 7 day share price return of 17.82% and a 30 day share price return of 20.68%. The proposed all cash acquisition and focus on physical AI and connectivity have helped refocus attention after a 90 day share price return that was down 7.75%.
Scan how markets are repricing physical AI and connectivity after the Synaptics bid shock by reviewing the hand picked 91 AI infrastructure stocks that is now shaping this theme.
With Synaptics up sharply on the Onsemi bid and trading near the announced cash offer, the debate now turns to price. Is most of the upside already captured, or does the current valuation still leave meaningful headroom?
Most Popular Narrative: 8% Undervalued
On the most followed view, Synaptics trades below an assessed fair value of about $130, compared with a last close of $119.46, which puts the Onsemi cash offer in direct tension with this implied upside.
The company's strategy to bundle highly integrated solutions that combine wireless connectivity, low-power mixed-signal processing, and embedded AI/software content is expected to increase silicon content per device and drive higher gross margins as more revenue is captured per customer design win. Active product portfolio optimization, including organic and disciplined inorganic investment, is intended to repurpose engineering talent toward higher ROI segments (especially Core IoT and Edge AI). This supports expanding operational leverage and could contribute to margin expansion and operating earnings growth.
See why 15 investors see Synaptics as 8% undervalued.
Result: Fair Value of $130 (UNDERVALUED)
Still, Synaptics faces real pressure if execution on Core IoT and edge AI stalls, or if rivals undercut pricing and squeeze already thin profitability.
Find out about the key risks to this Synaptics narrative.
Another Angle On Synaptics' Valuation
On one hand, Synaptics screens as about 8% undervalued against the $130 fair value from the consensus narrative. On the other, the SWS DCF model points to a future cash flow value of $82.64 per share, which makes the current $119.46 price look expensive instead. Which lens is more useful for evaluating a deal-driven story like this?
Look into how the SWS DCF model arrives at its fair value.
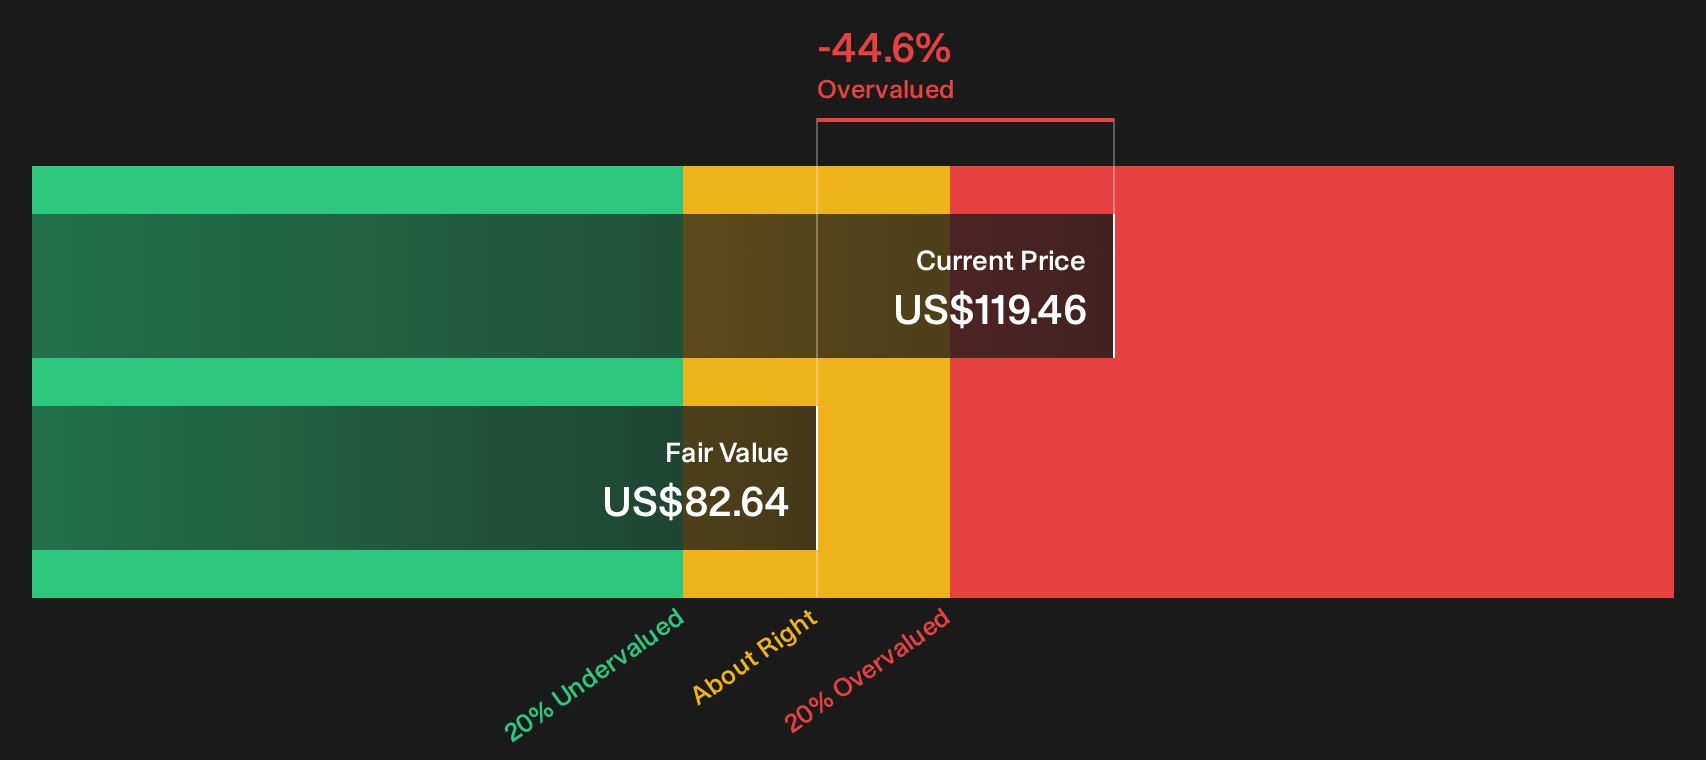
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Synaptics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Synaptics after the Onsemi offer make this a live debate, so act quickly, review the data, and weigh the 1 key reward and 1 important warning sign.
Looking for more ideas beyond Synaptics?
If you stop with Synaptics, you risk missing other opportunities that fit your style. Widen your scope and pressure test your thesis using targeted screeners.
- Hunt for potential bargains by scanning a curated 29 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their underlying metrics.
- Build a steadier portfolio by focusing on income ideas through a focused set of 8 dividend fortresses designed for investors who care about reliability as much as yield.
- Prioritise resilience by filtering for companies on a 31 resilient stocks with low risk scores that aim to keep balance sheets and risk scores at the center of your process.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com