
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Parex Resources (TSX:PXT) Stock May Be Undervalued Based On Earnings Power
Parex Resources has delivered a strong share price run over the past year, which naturally puts the focus on whether the current tag still lines up with its earnings power. With that backdrop, the key question for investors is how much of the recent optimism is already embedded in today's valuation.
- Parex Resources has returned 56.5% over the past year, which raises the issue of whether the recent gain fairly reflects what the business is earning today.
- The company relies heavily on converting oil and gas production into consistent profits and cash flow, so any change in operating costs or field performance can shift what looks like a reasonable earnings multiple.
- Your read on Parex Resources is one view; the desks covering it have another. See what analysts think Parex Resources's shares could be worth.
The stock's next move may depend on whether Parex Resources' current share price is justified by the earnings it is generating right now.
If you are weighing Parex Resources against other opportunities that also hinge on earnings power, it can help to compare it with a broader set of 7 high quality undervalued stocks.
Is Parex Resources a Bargain on Earnings?
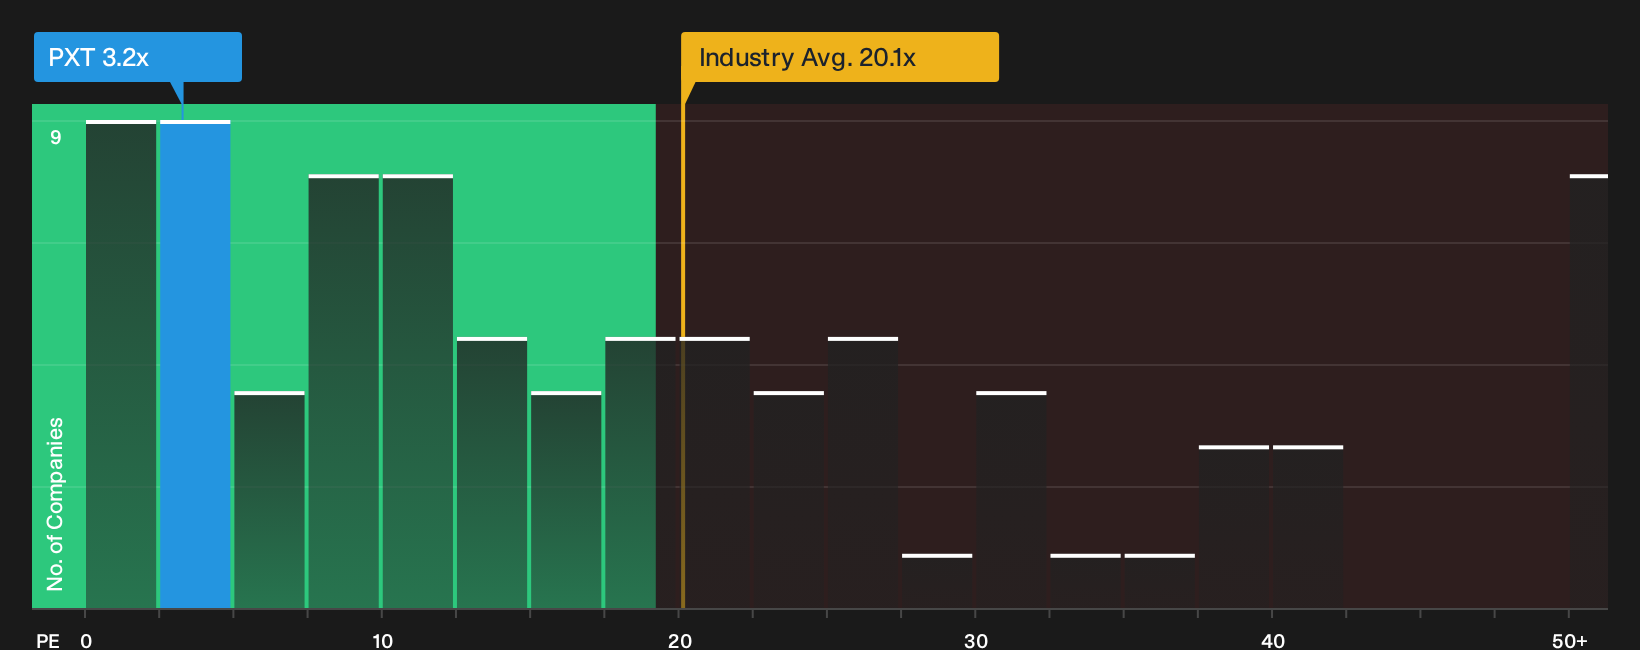
The P/E ratio fits Parex Resources because earnings sit at the center of how investors value an oil and gas producer. On this measure, the stock trades on about 3.2x its earnings, which is far below the Oil and Gas sector average of roughly 20.1x and also well under a broader peer group that clusters near 50.2x. That kind of gap indicates that the market is putting a much lower price on each dollar of Parex Resources' profit than on many comparable producers.
The fair multiple estimated for Parex Resources, based on its own growth profile, margins, size and risk, comes out higher than where the shares change hands today. That places the current P/E at a level that screens as undervalued by this tailored yardstick rather than by broad industry rules of thumb. Any investor weighing the recent share price run against these earnings multiples will need to decide whether the discount reflects risk that is already well understood or an opportunity that the market has not fully priced. Explore the numbers behind Parex Resources's P/E valuation.
The Parex Resources Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Parex Resources pick up where the P/E puzzle leaves off and spell out which paths for future growth, profitability and earnings could make the current share price look high, low or roughly in line. They sit on the Community page and turn a single ratio or model output into a set of concrete assumptions you can watch over time, so you can see whether the story behind that number continues to hold up.
One of the top community narratives on Parex Resources: 15% undervalued
"Meaningful internal cost optimizations, infrastructure upgrades, and lower normalized power costs have structurally reduced operating expenses, enhancing netbacks and driving higher net margins..."
Discover why this Narrative puts Parex Resources at 15% undervalued.
One more Parex Resources check that sits beyond the earnings multiple
Price and profits only tell part of the story for Parex Resources, since the track record and pay structure of the people running it can tilt the risk and reward equation. See who runs Parex Resources and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com