
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To VSE (VSEC) Raised 2026 Guidance
- VSE Corporation reported record Q2 2026 revenue and profitability, supported by the completed acquisitions of Precision Aviation Group and Northstar and by continued organic growth in its aviation aftermarket operations. Management raised full year 2026 guidance for revenue and adjusted EBITDA margin.
- The Q2 performance shows how VSE's pure play aviation aftermarket model, built around higher margin engine and component services, is starting to scale as recent acquisitions and existing operations feed into stronger adjusted EBITDA economics.
- Next, the focus will be on how VSE's raised 2026 guidance could reshape the existing investment narrative built around its aviation aftermarket strategy.
VSE Investment Narrative Recap
To stay invested in VSE, you need to believe its pure play aviation aftermarket model can keep scaling as engine and component services become a larger share of activity. The big near term swing factor is execution on integrating Precision Aviation Group and Northstar while keeping that 19.2% adjusted EBITDA margin profile broadly intact.
The biggest operational risk is that heavier exposure to aviation cycles, plus higher leverage from the roughly US$2b PAG deal and inventory investments like the APU program, puts more pressure on cash generation if demand softens. The latest guidance raise supports the existing thesis rather than fundamentally changing it.
The most relevant update for this Q2 print is VSE's completion of the Precision Aviation Group and Northstar acquisitions, which now sit inside the aviation aftermarket platform. Those deals expand the footprint to 61 locations across 8 countries and helped lift adjusted EBITDA margins to 19.2% in the quarter.
For you as a shareholder, the key question is whether VSE can translate that larger global network into durable engine related aftermarket activity, OEM distribution volume and the US$15m synergy run rate targeted from PAG by 2027. Any sign of integration friction, slower deleveraging or weaker free cash flow would quickly test that assumption.
VSE's current analyst storyline points to revenues of US$2.4b and earnings of US$250.0m by 2029, based on forecast revenue growth of 21.7% per year and an earnings increase of roughly US$166.5m from US$83.5m today. This would equate to about a 3x increase in profit over that period.
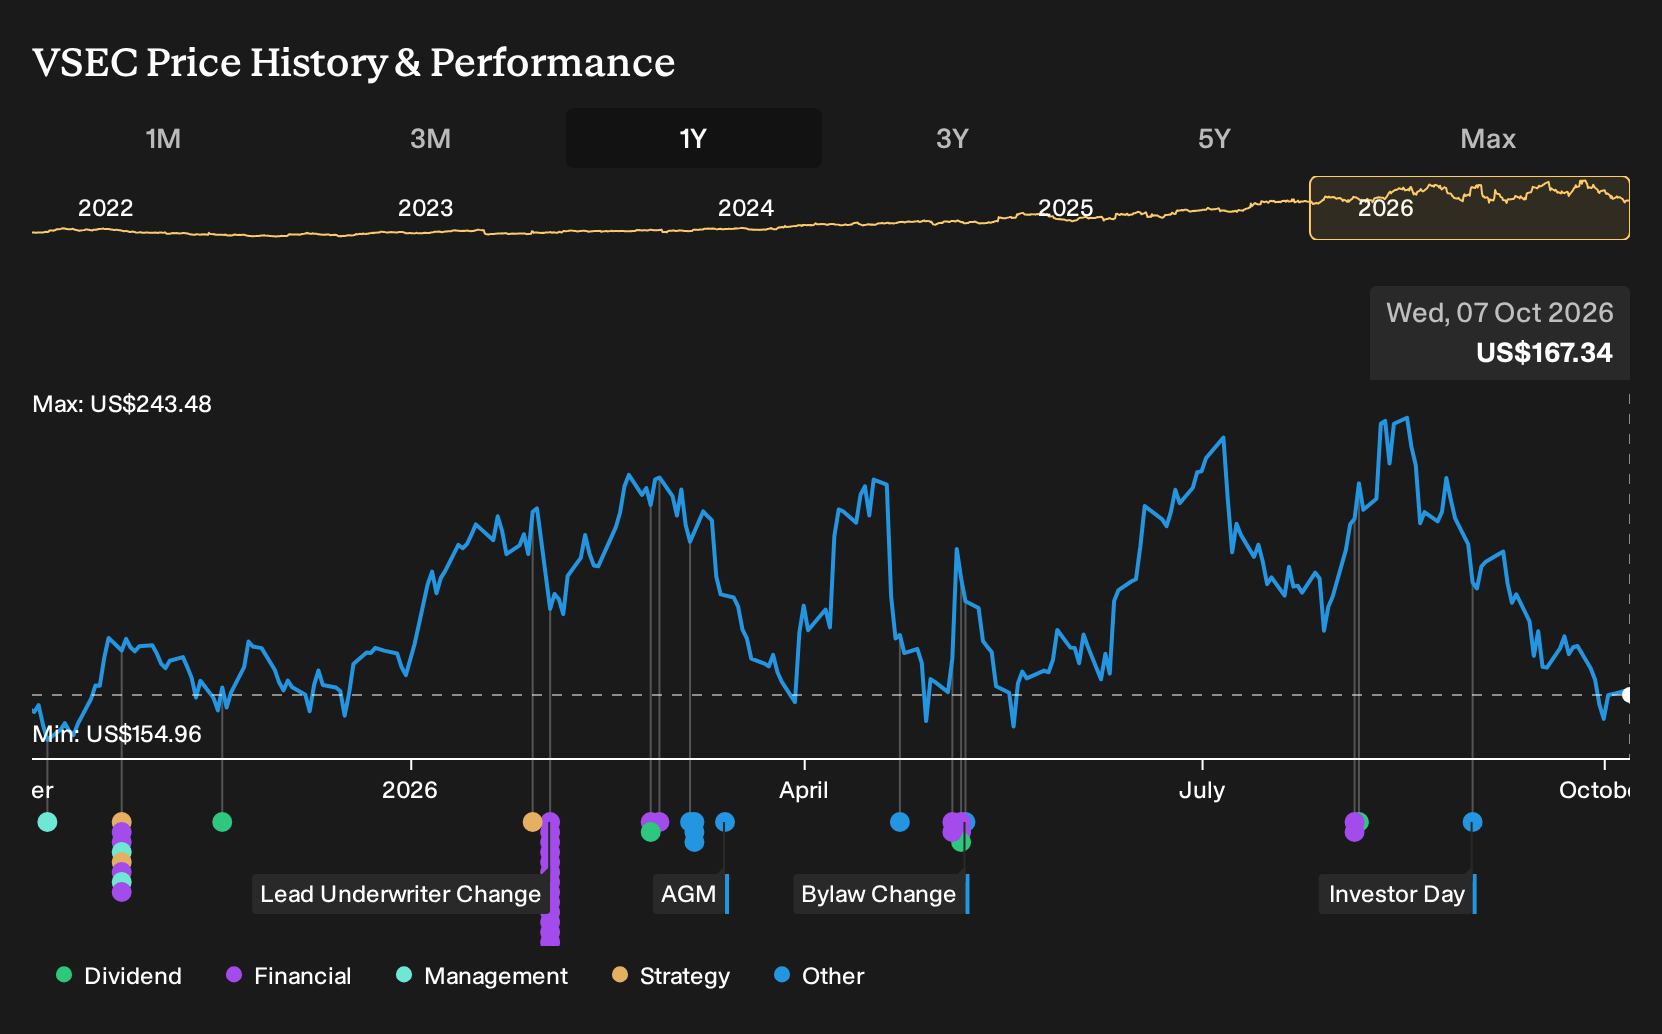
Uncover how VSE's fair value indicates a 61% potential upside to its current price, which could narrow quickly if VSE keeps executing on its plan.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster tightly between US$270 and about US$289.8 per share, so retail views on VSE Corporation currently sit in a relatively narrow band. Those opinions pre date the Q2 2026 guidance lift, so you should weigh them against risks around aviation cycles, leverage and integration before drawing your own conclusions.
Explore 2 other VSE fair value estimates, including one that suggests there may be as much as 73% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your VSE research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for VSE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate VSE's overall financial health at a glance.
Looking For More Ideas Beyond VSE?
If VSE has sharpened your interest in aviation aftermarket stories and service led earnings, it can help to compare it with other businesses that share some of the same financial strengths. The Simply Wall St Screener lets you quickly filter for different combinations of balance sheet quality, profitability and dividend profiles so you can build a broader watchlist around your own risk and return preferences.
- If you want a wider field of financially resilient businesses, start with a 31 resilient stocks with low risk scores that are built around sturdier balance sheets and lower risk scores.
- For investors focused on value and fundamentals, scan through 29 high quality undervalued stocks that pair healthy cash flows with stronger balance sheets.
- If you are hunting for less crowded stories with room for the thesis to develop, sort through 20 high quality undiscovered gems that already show solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com