
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Duolingo (DUOL) Gains Ahead Of Earnings, Is The Premium Already Priced In?
Duolingo stock moves ahead of earnings
Duolingo (DUOL) gained 2.43%, topping major indexes during a weak session for broader markets. Investors focused on the language learning platform's upcoming earnings report and its premium valuation versus industry peers.
At around US$151.72 per share, Duolingo has shown short-term strength with a 7 day share price return of 6.54% and a 90 day share price return of 16.75%. However, the year to date share price return is down 14.03% and the 1 year total shareholder return has declined 56.31%, suggesting that recent momentum has picked up while longer term holders have faced a much tougher run.
Pace your exposure to premium growth stories like Duolingo by scanning a curated 20 high quality undiscovered gems that have strong fundamentals but far less attention.Duolingo has rebounded sharply in the short term while longer-term holders are still in a deep hole. Does that recent strength still leave enough upside to justify the current valuation risk?
Most Popular Narrative: 13% Overvalued
Duolingo last closed at $151.72, while the most followed narrative pegs fair value at $134.29 using a 7.29% discount rate. That gap matters because the thesis leans on strong user trends and product expansion to justify paying a premium for the shares.
Continued investment in and expansion of adjacent educational categories such as Math, Music and Chess, with chess already reaching about 7 million daily active users and growing faster than languages, extends Duolingo’s reach into new learner segments and can add incremental revenue streams over time.
Experiments with new monetization formats, including an ad supported Super Lite tier at roughly half the price of Super and efforts to improve ad sales quality, aim to convert users who are less likely to pay for the full subscription and to raise ad ARPU, which can support bookings, revenue growth and earnings over time even as some paywall friction is reduced.
See why 168 investors see Duolingo as 13% overvalued.
Result: Fair Value of $134.29 (OVERVALUED)
Still, if Duolingo sees user growth in mature markets cool or regulatory hurdles in China tighten further, the current user-first thesis could quickly lose traction.
Find out about the key risks to this Duolingo narrative.
Another View: Duolingo Through A Cash Flow Lens
Price targets and narratives suggest Duolingo looks rich, yet the SWS DCF model points in the opposite direction. At $151.72, the shares are described as trading below an estimated future cash flow value of $301.81. This frames the stock as undervalued on this approach. Why does one framework flag premium risk while another signals a discount?
Look into how the SWS DCF model arrives at its fair value.
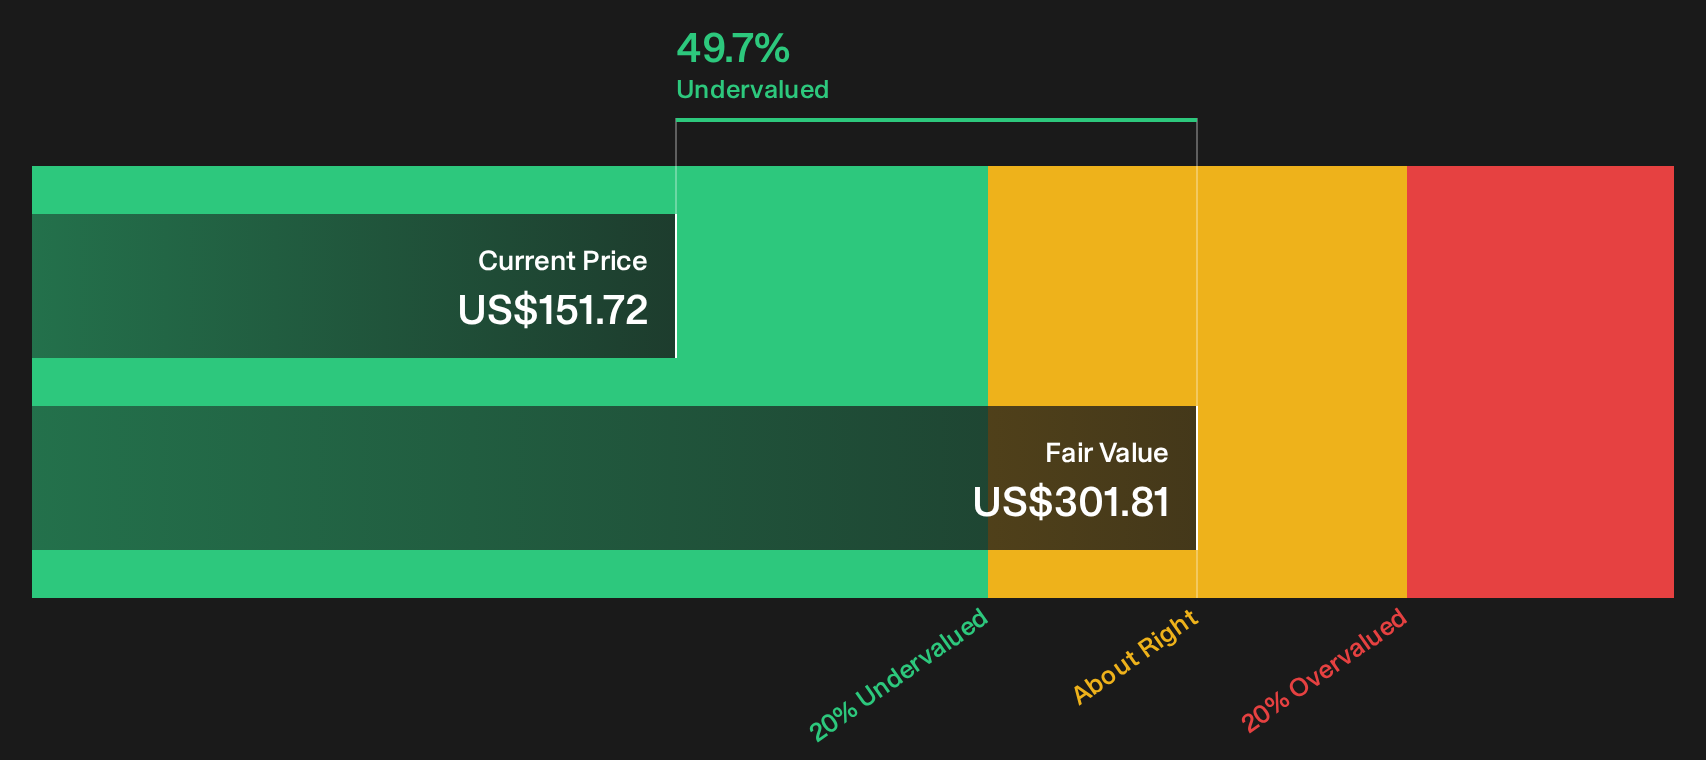
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Duolingo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Duolingo is clearly split, with optimism on potential rewards sitting right beside concern about real risks. Move fast and review the full breakdown of upside drivers and red flags through 2 key rewards and 2 important warning signs
Looking for more Duolingo sized ideas?
Do not stop with Duolingo when the wider market is full of other potential opportunities that could better match your risk tolerance and return goals.
- Target reliable cash generators by reviewing companies with a list of solid balance sheet and fundamentals (25 results) that can better handle shocks and keep funding their growth plans.
- Hunt for potential mispricing and compare Duolingo with a curated 29 high quality undervalued stocks that screens for quality businesses trading below estimated worth.
- Protect the downside first, and then think about upside by scanning a 31 resilient stocks with low risk scores tailored for resilience when conditions get tougher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com