
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Conagra Brands Stock After Profitability Improves
- Conagra Brands reported first quarter 2026 results with sales of US$2,595.9 million, net income of US$174.3 million, and basic EPS from continuing operations of US$0.36, while affirming a US$0.175 quarterly dividend to be paid on December 3, 2026.
- Profitability improved even as sales were slightly lower than a year earlier, which highlights Conagra Brands' cost control, margin work, and dividend commitment for anyone tracking its longer term earnings profile.
- This raises the question of how Conagra Brands' higher earnings per share alongside softer sales may influence the broader investment narrative around profitability.
See how Conagra Brands' steady earnings and dividend focus compare with other consumer stocks on our hand picked 8 dividend fortresses for income minded investors watching payout resilience.
Conagra Brands Investment Narrative Recap
To own Conagra Brands, you need to believe that cost programs, portfolio clean up and supply chain projects can steadily rebuild profitability even if sales stay flat or slightly weaker. The first quarter result, with softer revenue but higher earnings per share, fits that margin repair story and supports the idea that productivity work is flowing through.
The near term swing factor still sits in execution on those productivity targets while managing volume pressure and tariffs. The biggest risk remains leverage and cash generation. If inflation or weaker demand keep squeezing operating cash flow, it could slow debt reduction and leave less room to fund projects like Project Catalyst at the pace investors expect.
The most relevant recent announcement for that thesis is the first quarter 2026 report. Sales of US$2,595.9 million, net income of US$174.3 million and basic EPS of US$0.36, compared with US$0.34 a year earlier, point to efficiency gains helping offset volume softness. That pattern matters more for the story than a single quarter of top line movement.
For you as a shareholder, the key question is whether Conagra Brands can repeat this kind of margin performance while rolling out Project Catalyst, higher capital spending and portfolio simplification. Any stumble that drags on cash flow would make its existing leverage and dividend commitments more uncomfortable and could weigh on how much patience the market has with the margin rebuild narrative.
What Analysts Are Building Into The Conagra Brands Story
Conagra Brands' narrative projects US$11.0 billion revenue and US$810.2 million earnings by 2029. This assumes revenue stays broadly flat each year and implies an earnings increase of about US$2.7b from current earnings of a US$1.9b loss.
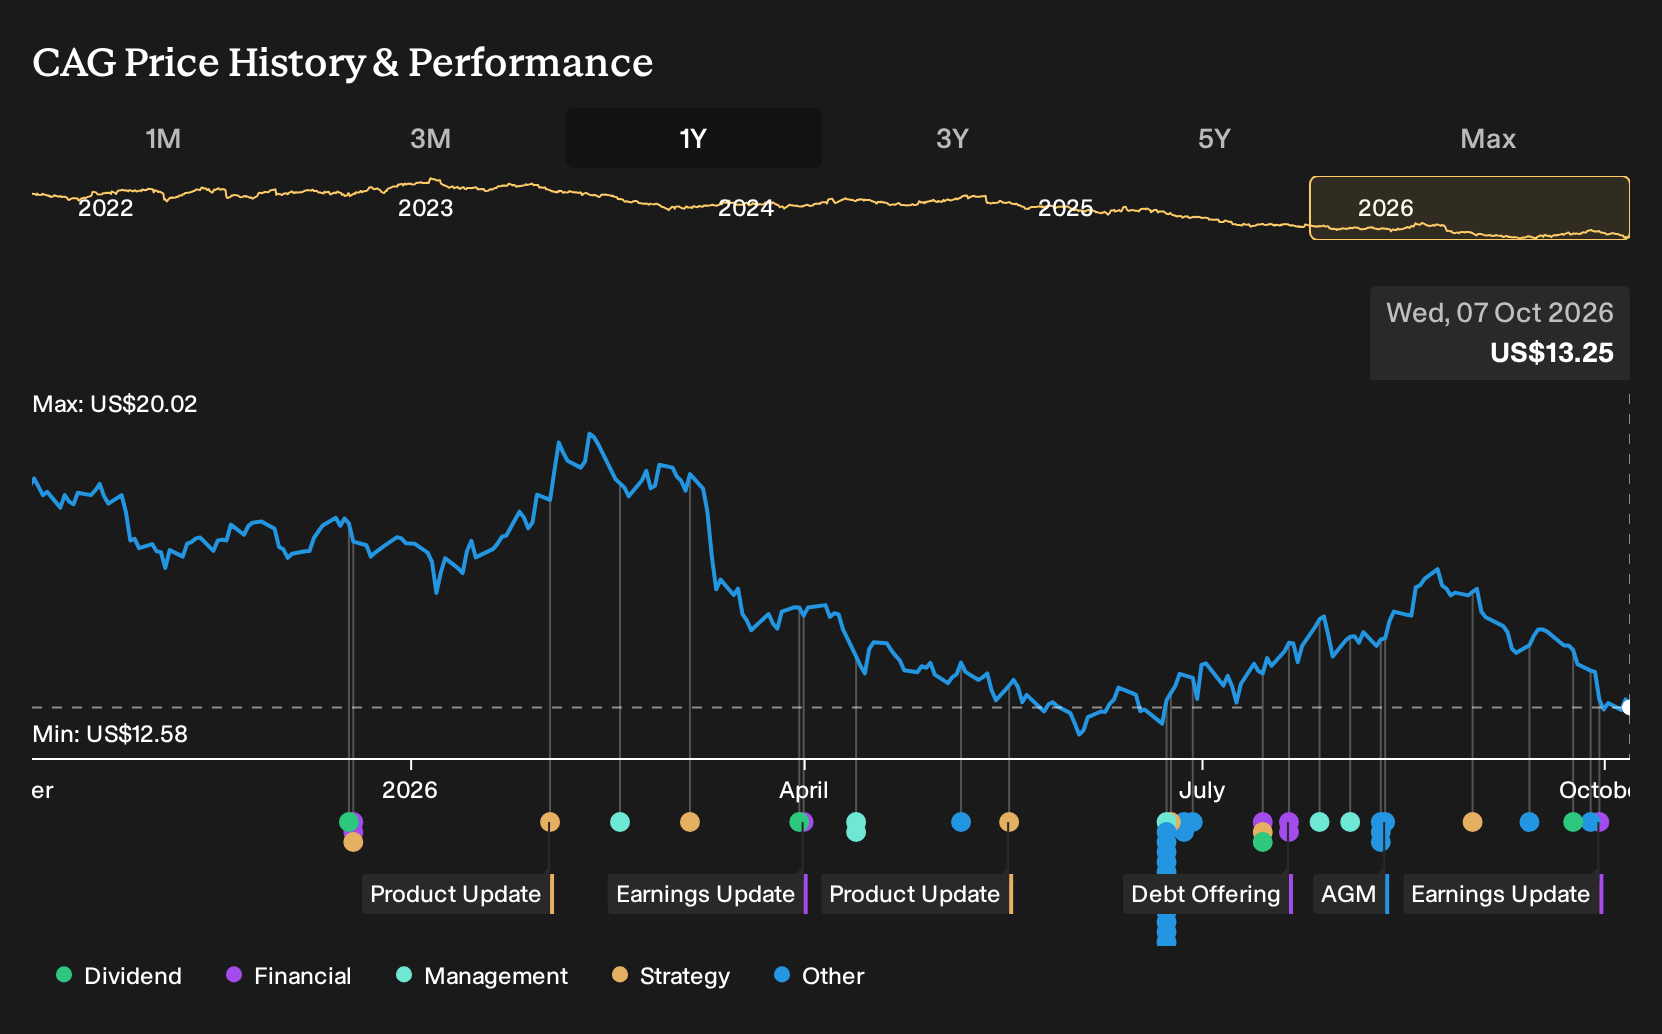
Uncover why Conagra Brands' fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest Conagra Brands forecasts lean heavily on demand risk. Those analysts were penciling in revenue of about US$10.7b and earnings of roughly US$427.0 million by 2029, which is well below the consensus path. You should treat today’s stronger EPS print as a fresh data point that could reshape those views.
Explore 7 other Conagra Brands fair value estimates, including one that suggests as much as 17% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Conagra Brands research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Conagra Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Conagra Brands' overall financial health at a glance.
Looking For More Conagra Brands Style Ideas?
If Conagra Brands appeals to you for its earnings profile and dividend focus, it can help to benchmark that story against other listed businesses with different strengths. A broad look at peers can sharpen your view on risk, balance sheet strength and income potential.
You can use the Simply Wall St Screener to find other stocks that match your preferences across income, value and resilience.
- If you want resilient businesses with fewer balance sheet surprises, start with our 31 resilient stocks with low risk scores which emphasises financial strength and lower risk scores.
- If income is your priority, compare Conagra Brands with companies on our 8 dividend fortresses and see which payouts and coverage profiles best fit your needs.
- If you are hunting for overlooked opportunities with solid fundamentals, scan through our 20 high quality undiscovered gems which focuses on quality stocks the market may not be watching closely yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com