
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Bandwidth (BAND) Pullback Puts Its Cloud Communications Story And Valuation In Focus
Bandwidth (BAND) has drawn fresh attention after a sharp single day decline of about 4.4%, even as the stock shows a gain over the past month and a positive year to date performance.
For context, Bandwidth shares now trade at US$57.47. The sharp single day drop and a 7 day share price return that is down 5.3% come after a strong 30 day share price return of 31.3% and a very large year to date share price gain of 304.2%. At the same time, the 1 year total shareholder return of 255.4% and 3 year total shareholder return of over 4x hint that recent volatility reflects shifting views on future growth and risk rather than a simple one day setback.
Scan how Bandwidth’s sharp swings compare with other fast moving opportunities using our curated list of 20 high quality undiscovered gems.
Bandwidth now trades at a steep discount to one valuation estimate and below analyst targets after this pullback. Is the market sensibly cautious about the business, or overly skeptical of what the current price already reflects?
Most Popular Narrative: 14.5% Undervalued
On this view, Bandwidth’s fair value of $67.25 sits well above the last close at $57.47, drawing attention to what assumptions are driving that gap.
The ongoing migration of large enterprises from on-premises telephony to cloud-based communications solutions (UCaaS/CCaaS), often in regulated verticals, positions Bandwidth as a preferred provider for mission-critical, compliant, and reliable communications infrastructure, supporting sustained revenue growth and larger, higher-margin multi-year deals.
See why 11 investors see Bandwidth as 15% undervalued.
Result: Fair Value of $67.25 (UNDERVALUED)
Still, Bandwidth’s heavy reliance on a concentrated set of large enterprises, as well as on its Maestro and AI platforms, means slower adoption or customer churn could quickly challenge that undervalued thesis.
Find out about the key risks to this Bandwidth narrative.
Another View: What Bandwidth’s Sales Multiple Signals
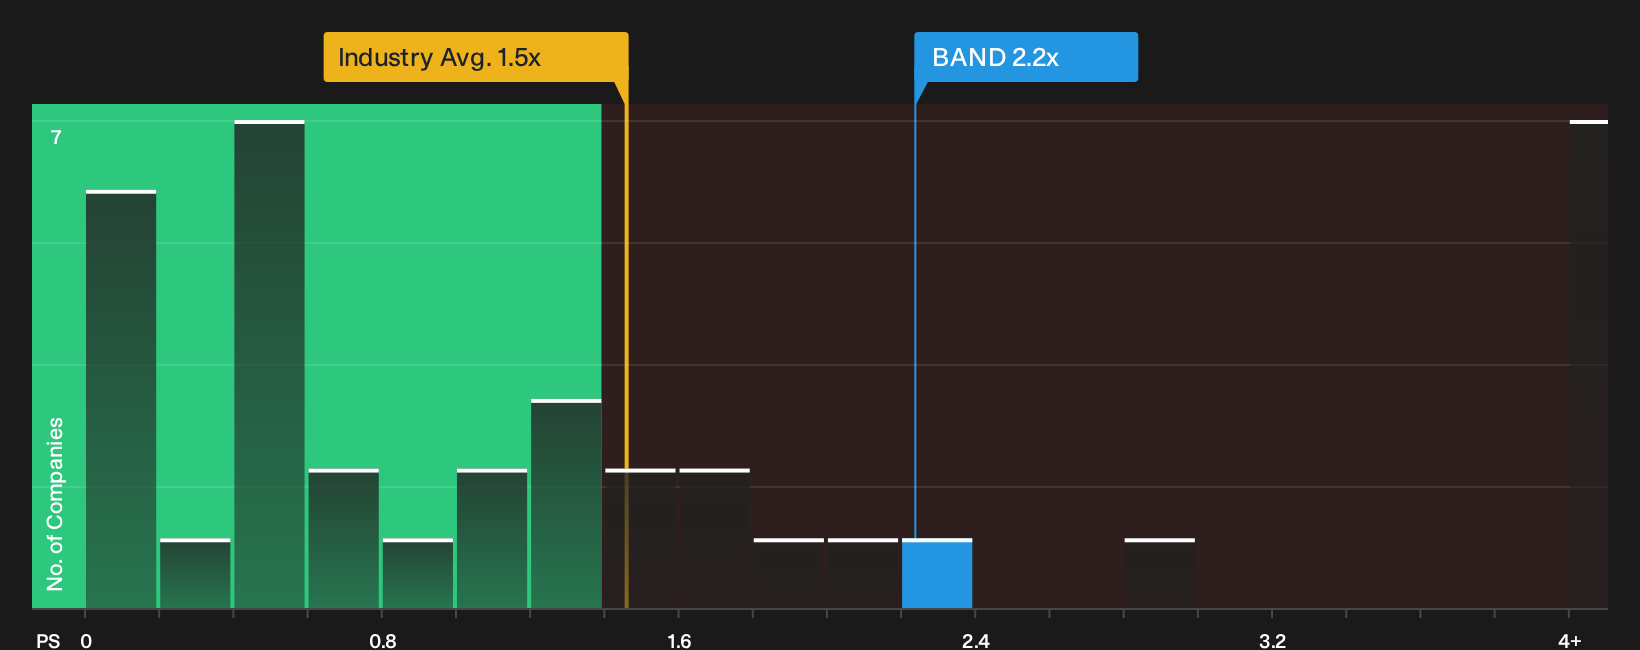
While the SWS DCF model suggests Bandwidth is heavily undervalued, the simple sales multiple tells a different story. The stock trades on a P/S of 2.2x, compared with a fair ratio of 1.2x, the US Telecom average of 1.5x, and a peer group around 2.2x. That gap points to meaningful valuation risk if investor enthusiasm cools or growth expectations slip even slightly.
Seen through that lens, the question becomes whether you trust the rich revenue multiple that the market currently pays or the much higher value implied by cash flow forecasts.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Recent moves in Bandwidth have raised strong opinions on both risk and upside. Consider acting while sentiment is fresh and reach your own conclusion by weighing 3 key rewards and 3 important warning signs.
Looking for more Bandwidth sized ideas?
If you stop with Bandwidth, you risk missing other opportunities that match your style. Put the screener to work and let it widen your field.
- Target resilient compounding candidates by focusing on companies with steady finances and robust balance sheets through our curated list of solid balance sheet and fundamentals (25 results).
- Hunt for pricing gaps where quality and valuation intersect by scanning our focused set of 29 high quality undervalued stocks.
- Lock in potential income streams alongside capital appreciation potential by reviewing a hand picked group of 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com