
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To ZoomInfo Stock As Agent Teams Launches
- ZoomInfo Technologies recently launched Agent Teams inside GTM Studio, using DoubleO.ai's orchestration architecture to coordinate AI agents across company systems, ZoomInfo data, and buying signals so go to market workflows can run from signal to action without new contracts or SKUs.
- The new Agent Teams capability points to a push for deeper workflow automation across revenue operations, which could influence customer adoption patterns and how existing buyers rely on ZoomInfo's data and tools in everyday selling.
- We will look at how ZoomInfo's investment narrative around AI driven GTM workflows intersects with the Agent Teams launch for revenue teams.
Scan how ZoomInfo Technologies fits into the wider AI tooling shift by comparing it with 91 AI infrastructure stocks that are wiring data and automation directly into revenue teams' everyday workflows.
ZoomInfo Technologies Investment Narrative Recap
To own ZoomInfo Technologies, you need to believe its GTM platform and AI tooling can offset revenue pressure, including forecast annual top line declines of 1.3% over the next three years, and a shrinking smaller customer base. The near term story is still about stabilising revenue while working toward the profitability that analysts expect over the same period.
The current operating swing factor is execution on upmarket clients and AI led workflows like Agent Teams, without letting customer concentration or commoditisation creep in. Heightened data privacy rules and the firm’s high debt remain the most immediate risks, and the new launches do not materially change that risk profile yet.
Of the recent announcements, Agent Teams inside GTM Studio looks most relevant. It ties ZoomInfo Technologies deeper into customers’ daily GTM workflows by using DoubleO.ai’s orchestration to connect its data, buying signals, and existing systems so plays run from signal to action without manual babysitting and without new SKU or contract complexity.
If Agent Teams gains traction, the practical catalyst would be stronger embedding with large enterprises that are already standardising on GTM.AI, Copilot, and Operations. That could support cross sell, stickier contracts, and the margin story that analysts are watching, while still leaving competitive pressure, downmarket weakness, and regulatory costs as key execution risks for the business.
ZoomInfo Technologies Consensus Expectations Check
ZoomInfo Technologies' current analyst narrative leans heavily on a reset in the income statement over the next few years rather than rapid top line expansion. Forecasts point to revenue decreasing by 1.3% a year, while profit margins are expected to move from a loss position of 43.0% today to a positive 32.4% by 2029.
On earnings, consensus points to a swing from a loss of US$541.0 million today to earnings of US$391.8 million by 2029. That shift implies an earnings improvement of about US$933 million, which is a very large absolute step up for a business of ZoomInfo Technologies' size.
Those estimates sit alongside an analyst view that shares would need to trade on a P/E of 3.9x on those 2029 earnings to back current price targets. This compares with a P/E of 13.5x for the wider US Interactive Media and Services peer set. Forecasts also build in share count shrinking by 6.57% a year over the next three years, which would concentrate any future earnings across a smaller base of stock.
Bringing it together, consensus implies that by 2029 ZoomInfo Technologies would be producing US$1.2b of revenue, US$391.8 million of earnings and trading on a materially lower P/E multiple than the sector, all while revenue edges down modestly each year. The key question for investors is whether AI led products such as GTM Studio, Copilot and Agent Teams can support that margin recovery and earnings profile even as headline sales are forecast to decline slightly.
ZoomInfo Technologies' narrative projects US$1.2b revenue and US$391.8 million earnings by 2029. This aligns with revenue declining 1.3% per year and an earnings improvement of about US$933 million from a loss of US$541.0 million today.
Uncover how ZoomInfo Technologies' fair value indicates a 24% potential upside to its current price. This opportunity could narrow quickly as sentiment shifts.
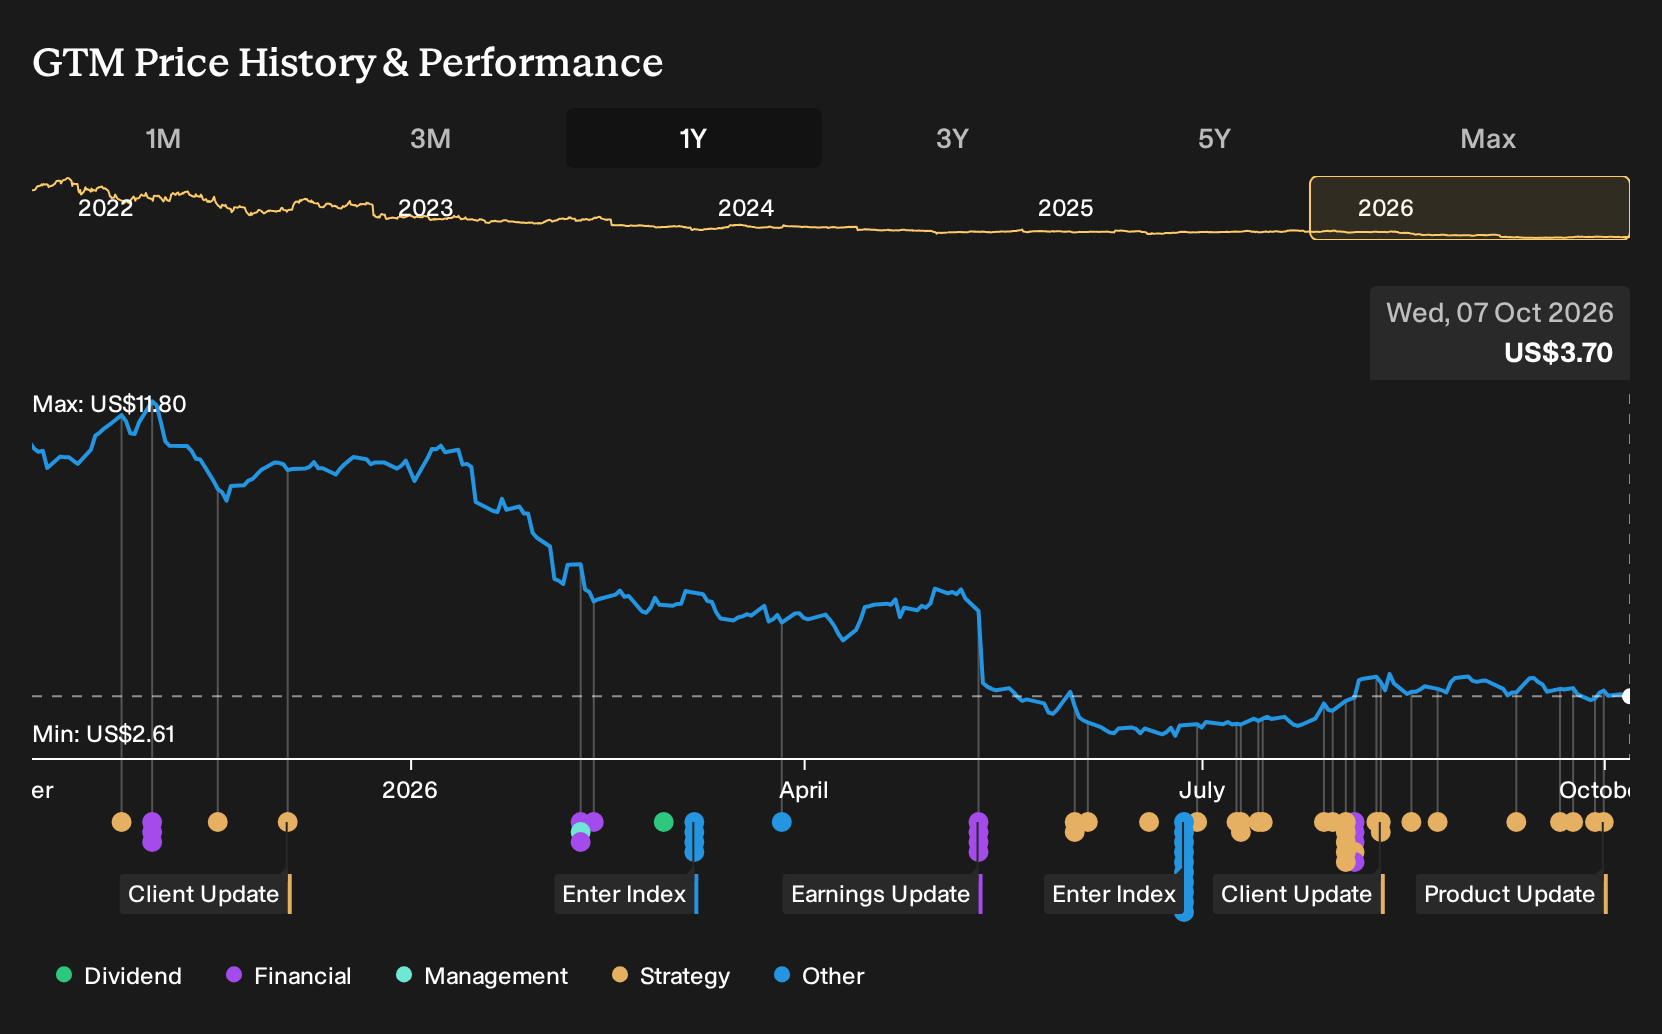
Exploring Other Perspectives
One alternate view on ZoomInfo Technologies focuses on the risk that revenue keeps slipping as the pricing model shifts. The most bearish analysts were assuming revenue would fall about 4% a year and earnings would land closer to US$300.6 million by 2029. Those estimates pre date Agent Teams, so expect opinions to move as you compare different forecasts.
Explore 4 other ZoomInfo Technologies fair value estimates, including one that suggests it could be worth just $4.58!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ZoomInfo Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ZoomInfo Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ZoomInfo Technologies' overall financial health at a glance.
Looking for more investment ideas beyond ZoomInfo Technologies?
Once you have a view on ZoomInfo Technologies, it can help to line it up against other opportunities that match your risk profile, income needs, or preference for balance sheet strength. The Simply Wall St Screener lets you do that side by side in a structured way.
- For investors who want quality cash flows at a discount, scan a focused 29 high quality undervalued stocks that pair strong fundamentals with prices that may not fully reflect them yet.
- If capital preservation sits near the top of your priority list, filter for 31 resilient stocks with low risk scores that score well on our risk metrics and may offer a smoother ride through market swings.
- When you are hunting for potential early stage opportunities with solid underpinnings, sort through a curated 20 high quality undiscovered gems that combine resilient balance sheets with under followed stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com