
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Southwest Gas Holdings (SWX) Looks 18% Undervalued, Is The Pullback A Buying Opportunity?
Southwest Gas Holdings (SWX) has drawn fresh attention after recent trading left the share price at US$82.48, with the utility’s returns mixed over the past month and over the past 3 months.
Recent trading has been choppy for Southwest Gas Holdings, with the share price falling 6.34% over the past 30 days and 9.52% over 3 months, even though the year to date share price return is 2.91% and the 1 year total shareholder return is 6.93%. This builds on 3 year and 5 year total shareholder returns of 54.83% and 50.89%, highlighting longer term momentum that sits in contrast to the more cautious tone in the recent price action.
Spot similar utility opportunities and contrast Southwest Gas Holdings with a curated list of solid balance sheet and fundamentals (25 results) that have not seen the same recent share price swings.Southwest Gas Holdings has a long operating history and recent annual revenue and net income growth, yet the share price has pulled back over the past quarter. Does that combination leave the stock looking cheap, fair, or already full?
Most Popular Narrative: 18% Undervalued
On the most followed narrative, Southwest Gas Holdings screens as undervalued, with a fair value estimate of $100.63 against the recent $82.48 close. This puts the current pullback in a very different light for anyone focused on long term earnings power.
Accelerated infrastructure investment opportunities are now anchored by a larger US$2.3b capital plan for the Great Basin 2028 Expansion Project and a broader US$6.3b 5 year utility capital program. These are expected to expand regulated rate base and in turn support higher future regulated revenue and earnings.
See why 3 investors see Southwest Gas Holdings as 18% undervalued.
Result: Fair Value of $100.63 (UNDERVALUED)
Still, Southwest Gas Holdings faces meaningful risks if regulators turn less supportive on key rate cases or if the US$2.3b Great Basin expansion encounters cost or timing setbacks.
Find out about the key risks to this Southwest Gas Holdings narrative.
Another View On Southwest Gas Holdings' Valuation
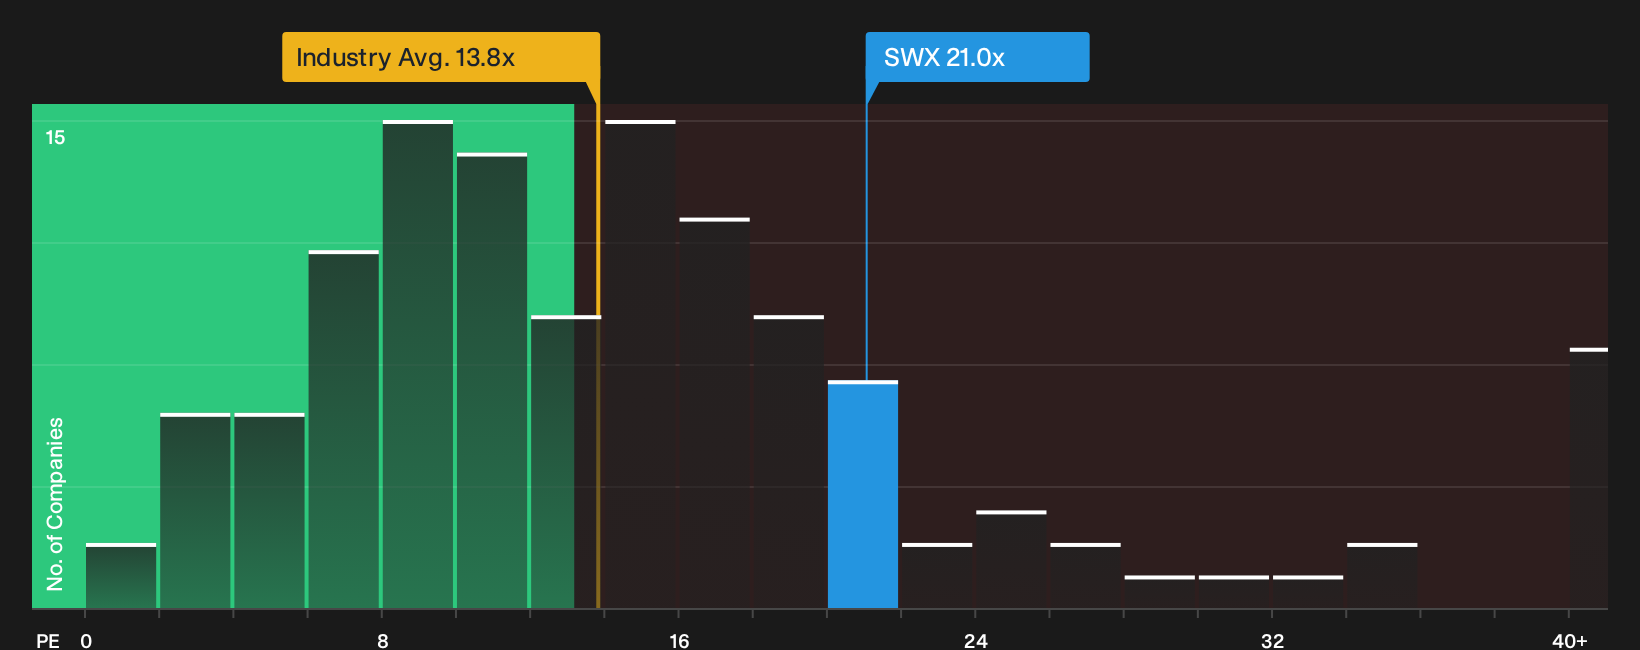
The fair value narrative paints Southwest Gas Holdings as 18% undervalued, yet the market is charging a premium P/E of 21x compared with 15.8x for US gas utilities and a 20.1x fair ratio estimate. That premium narrows the safety margin and raises the question of how much optimism is already in the price.
For investors weighing that premium, it can help to see how today’s P/E compares against history, peers and the fair ratio in one place, as set out in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed views on Southwest Gas Holdings so far. If you want your stance to be based on more than headlines, consider both sides of the story and review the 3 key rewards and 2 important warning signs
Looking For More Investment Ideas Beyond Southwest Gas Holdings?
If you want your research to work harder, start lining up a few fresh watchlist candidates now rather than waiting for the next headline move.
- Target resilient compounding by scanning the 31 resilient stocks with low risk scores that screens for businesses with lower risk profiles that can help balance out more volatile holdings.
- Hunt for potential value by reviewing the 20 high quality undiscovered gems where underfollowed companies with solid fundamentals might be getting far less attention than they deserve.
- Strengthen your core portfolio by checking the 8 dividend fortresses that focuses on higher yielding companies built around more durable payout histories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com