
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Stocks That May Be Undervalued By Up To 47.8%
The United States market has shown positive momentum, rising 2.0% over the last week and 12% over the past year, with earnings expected to grow by 18% annually. In this environment, identifying undervalued stocks can be crucial for investors seeking opportunities that may offer potential value despite the broader market's upward trend.
Top 10 Undervalued Stocks Based On Cash Flows In The United States
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Zions Bancorporation National Association (ZION) | $61.92 | $121.76 | 49.1% |
| Textron (TXT) | $73.03 | $142.91 | 48.9% |
| TD SYNNEX (SNX) | $271.52 | $523.23 | 48.1% |
| SouthState Bank (SSB) | $98.91 | $192.39 | 48.6% |
| KeyCorp (KEY) | $19.83 | $39.14 | 49.3% |
| Insteel Industries (IIIN) | $29.59 | $57.31 | 48.4% |
| Chagee Holdings (CHA) | $11.16 | $21.45 | 48% |
| Boston Scientific (BSX) | $41.58 | $79.80 | 47.9% |
| Artisan Partners Asset Management (APAM) | $33.75 | $64.98 | 48.1% |
| Addus HomeCare (ADUS) | $113.27 | $226.18 | 49.9% |
Here's a peek at a few of the choices from the screener.
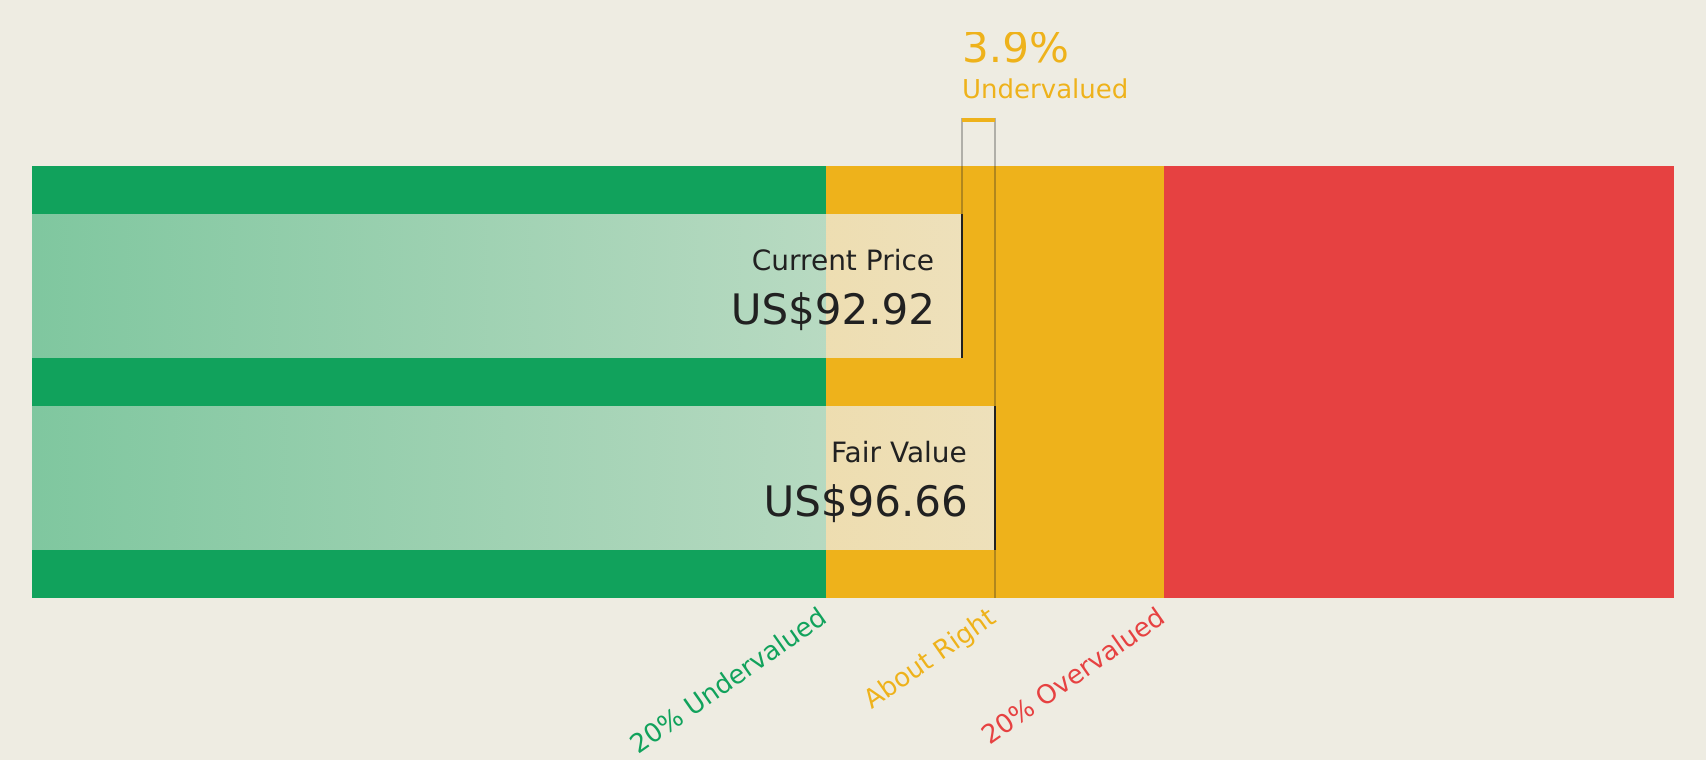
National Fuel Gas (NFG)
Overview: National Fuel Gas Company operates as a diversified energy company with a market cap of approximately $7.45 billion.
Operations: The company generates revenue through its Utility segment ($938.46 million), Pipeline and Storage segment ($430.74 million), and Integrated Upstream and Gathering segment ($1.29 billion).
Estimated Discount To Fair Value: 27.2%
National Fuel Gas appears undervalued, trading at US$77.68, below its estimated future cash flow value of US$106.64. The company is considering strategic alternatives for its natural gas business, potentially enhancing shareholder value through a spinoff or sale valued around $5 billion. Despite high debt levels and modest forecasted earnings growth of 4.6% annually, National Fuel's revenue has increased to $2.05 billion over nine months, reflecting strong cash flow fundamentals amidst strategic evaluations.
- Upon reviewing our latest growth report, National Fuel Gas' projected financial performance appears quite optimistic.
- Click here and access our complete balance sheet health report to understand the dynamics of National Fuel Gas.
PPG Industries (PPG)
Overview: PPG Industries, Inc. is a global manufacturer and distributor of paints, coatings, and specialty materials with operations across multiple regions including the United States, Canada, the Asia Pacific, Latin America, Europe, the Middle East, and Africa; it has a market cap of approximately $23.68 billion.
Operations: The company's revenue segments include Industrial Coatings at $6.71 billion, Performance Coatings at $5.69 billion, and Global Architectural Coatings at $4.03 billion.
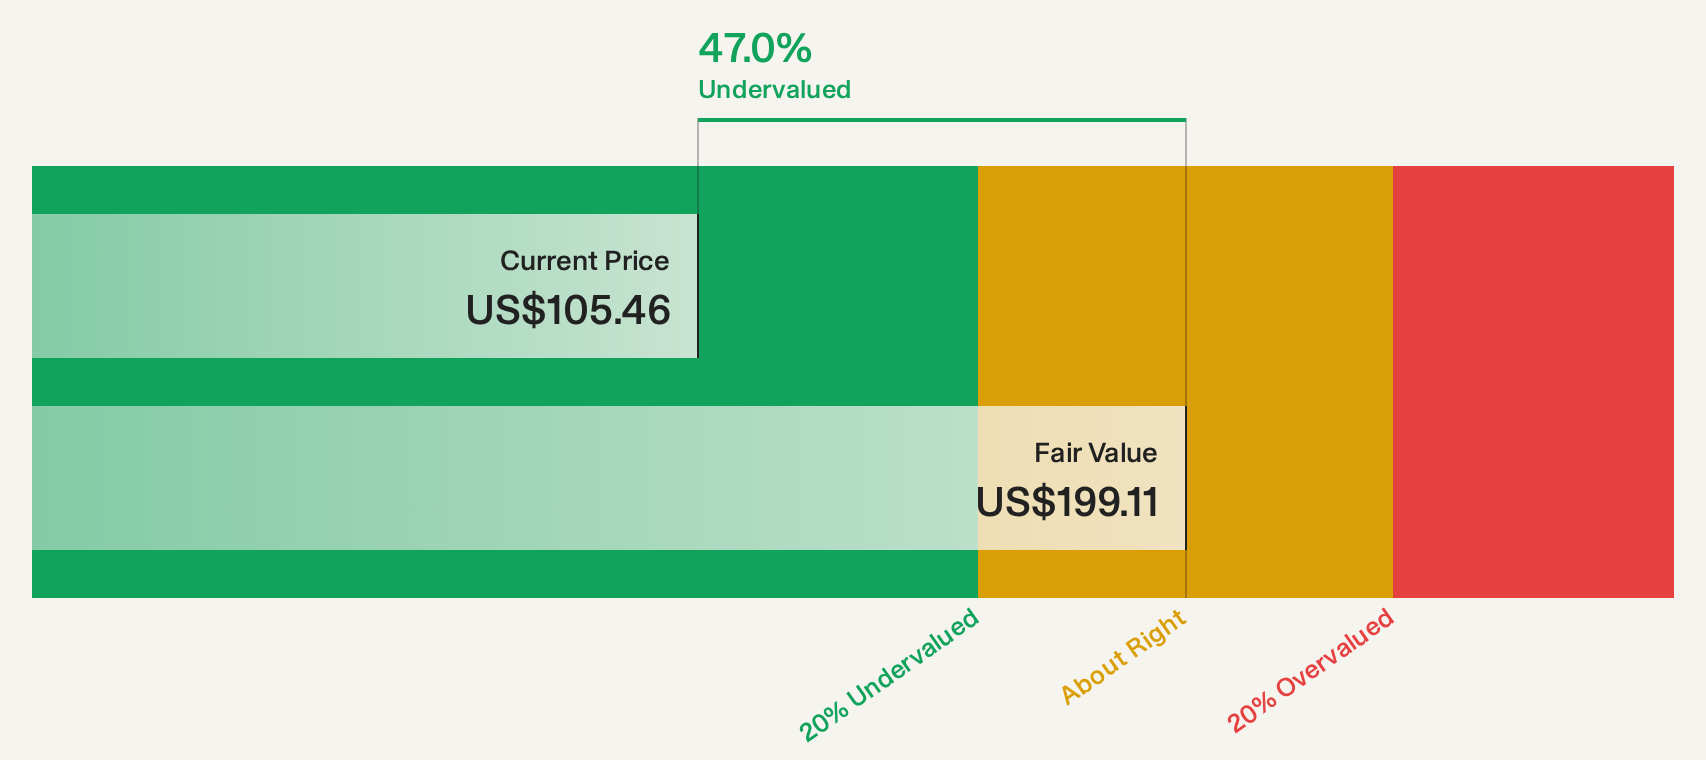
Estimated Discount To Fair Value: 47.8%
PPG Industries is trading at $105.08, significantly below its estimated future cash flow value of $201.26, suggesting strong undervaluation based on cash flows. Despite high debt levels and slower forecasted earnings growth compared to the US market, PPG's recent expansions and product innovations in aerospace and marine coatings may bolster revenue potential. The company maintains a reliable 2.82% dividend yield, reflecting solid cash flow management while enhancing production capacity to meet increasing demand in key sectors.
- In light of our recent growth report, it seems possible that PPG Industries' financial performance will exceed current levels.
- Get an in-depth perspective on PPG Industries' balance sheet by reading our health report here.
Tidewater (TDW)
Overview: Tidewater Inc. operates a global fleet of offshore marine service vessels, providing support services to the offshore energy industry, with a market cap of $4.08 billion.
Operations: The company's revenue segments include Vessel - Americas at $259.11 million, Vessel - Middle East at $183.11 million, Vessel - West Africa at $336.80 million, Vessel - Asia Pacific at $190.34 million, and Vessel - Europe/Mediterranean at $365.16 million.
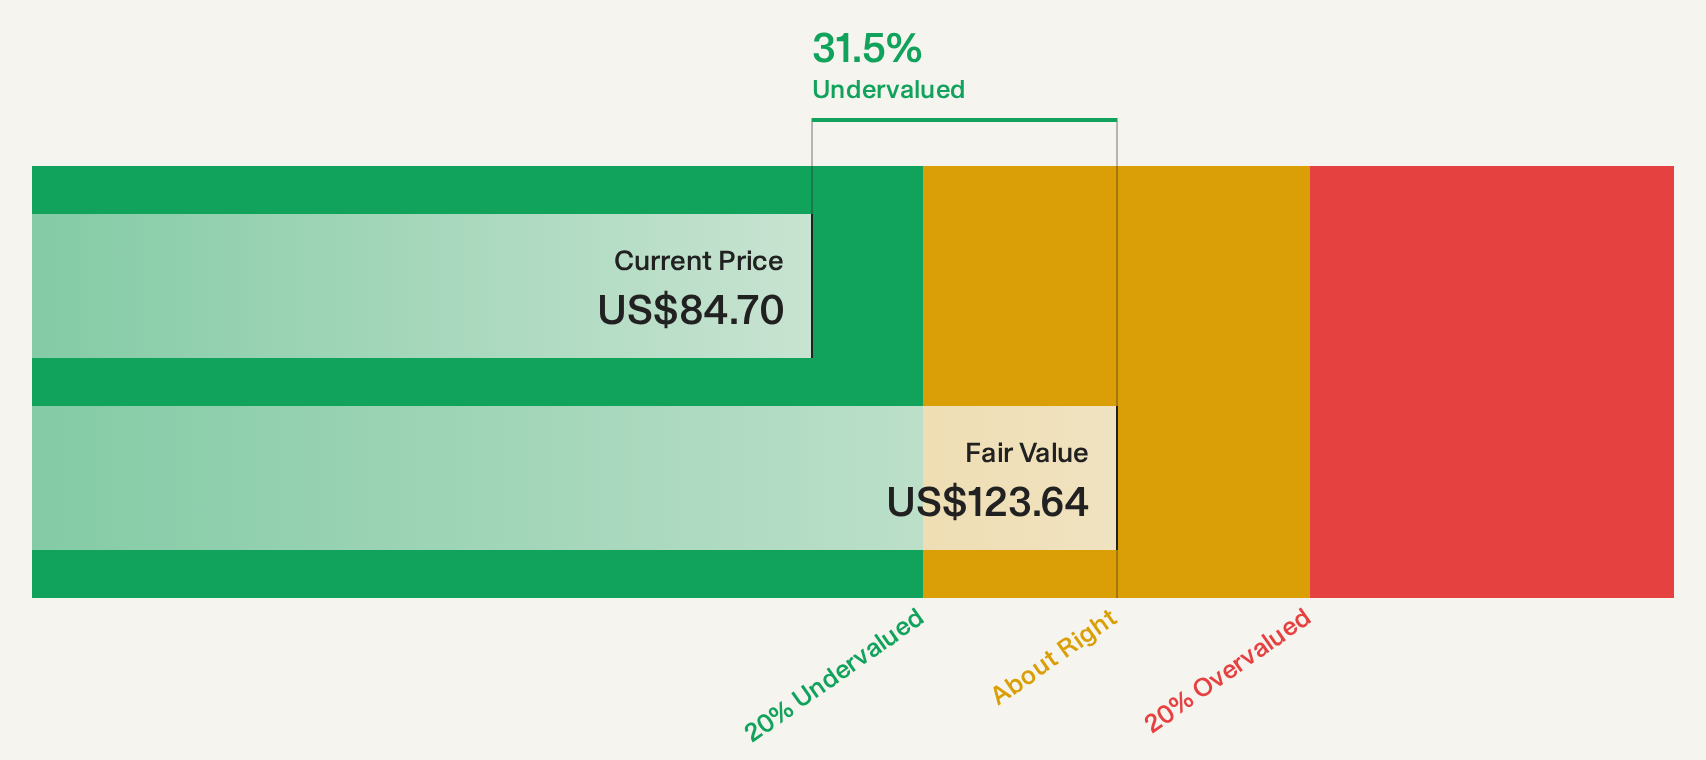
Estimated Discount To Fair Value: 32.3%
Tidewater Inc. is trading at $83.4, well below its estimated future cash flow value of $123.19, highlighting undervaluation based on cash flows. Despite a decline in recent net income and revenue growth forecasted to lag behind the US market, earnings are expected to grow significantly at 25% annually over the next three years. The company remains disciplined in pursuing M&A opportunities and has shown commitment through a completed share buyback program worth US$180.73 million.
- Our growth report here indicates Tidewater may be poised for an improving outlook.
- Click to explore a detailed breakdown of our findings in Tidewater's balance sheet health report.
Next Steps
- Discover the full array of 109 Undervalued US Stocks Based On Cash Flows right here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Contemplating Other Strategies?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com