
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Garmin (GRMN) Launches Two Premium Wearables On A Valuation Story Still In Focus
Garmin (GRMN) just rolled out two high-end wearables, the Enduro 4 for endurance athletes and the Approach S72 for golfers, in a twin product launch that puts fresh attention on the stock.
Despite the buzz around Enduro 4 and Approach S72, Garmin’s recent 7-day share price return is down 3.72% and the 1-day move is down 1.09%. At the same time, the year-to-date share price return of 36.42% and 3-year total shareholder return of 167.33% point to strong longer term momentum that shorter pullbacks have not erased.
Capitalize on Garmin’s specialist wearables momentum by scanning a curated set of peers with 88 robotics and automation stocks that are building the next wave of performance-focused hardware.Garmin now trades at a single digit discount to the average analyst target after a brief pullback, while longer term returns appear strong. Is the market being fairly cautious here, or mispricing the story?
Most Popular Narrative: 9% Undervalued
Garmin’s most followed valuation storyline points to a fair value of $302 against the last close of $276.16, which frames today’s pullback as a gap rather than a stretch.
The launch of the Garmin Connect+ premium service, which offers AI based health and fitness insights, is likely to boost subscription based revenue growth and improve overall margins through higher margin services. The acquisitions of TrainingPeaks and TrainHeroic, which add endurance and strength training platforms around Garmin wearables, are expected to deepen the service ecosystem and create more recurring revenue streams that can support gross margin and operating margin over time.
See why 47 investors see Garmin as 9% undervalued.
Result: Fair Value of $302 (UNDERVALUED)
Still, Garmin’s Outdoor softness and management’s expectation that Auto OEM could slip back into operating losses give this 9% undervalued narrative real execution risk.
Find out about the key risks to this Garmin narrative.
Another View: Garmin On Earnings Multiples
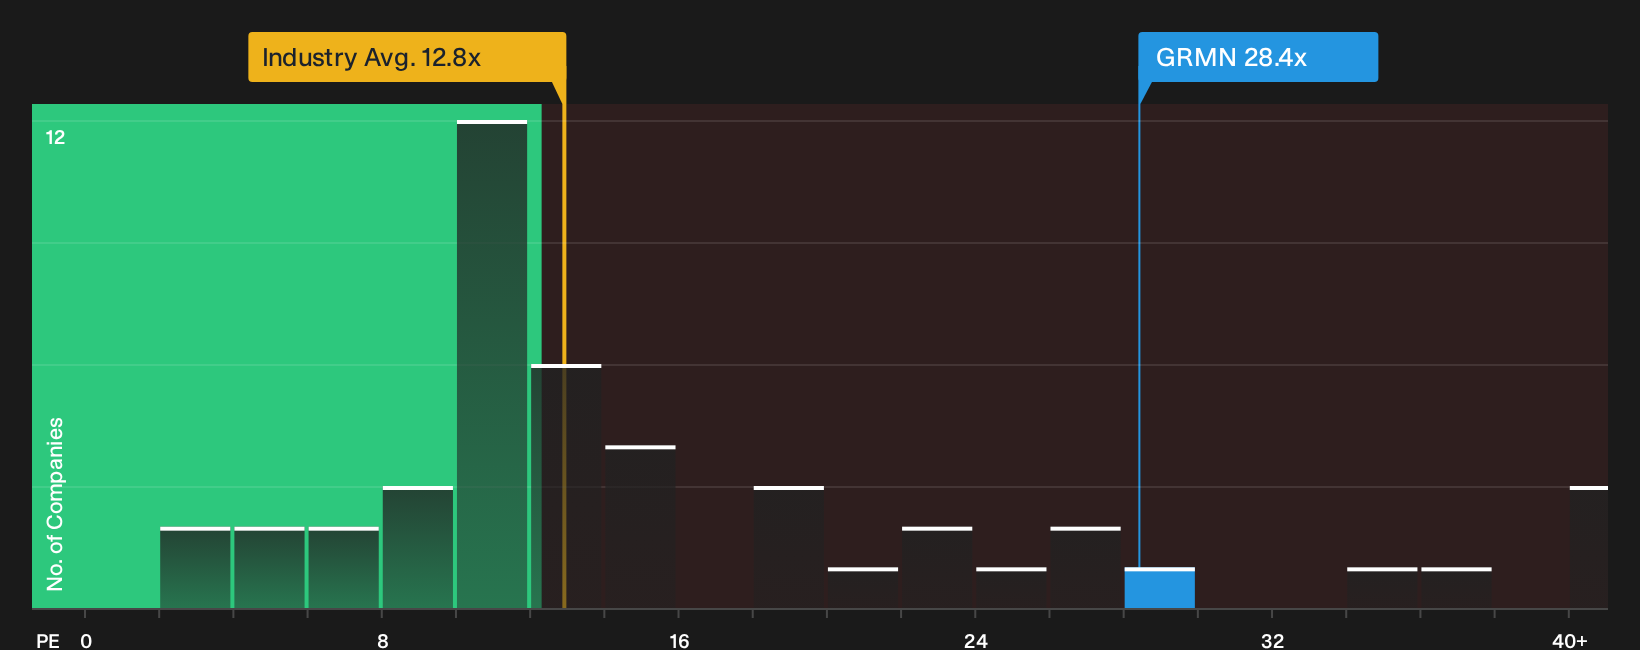
Garmin’s story changes when you stop at the simple earnings multiple. The stock trades on a P/E of 28.4x, while the US Consumer Durables group sits at 12.8x, peers average 24x, and the fair ratio for Garmin is estimated at 20.5x. That gap points to meaningful valuation risk if sentiment cools rather than improves further. Where does that leave your own comfort zone on price for quality?
See what the numbers say about this price in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether Garmin’s recent moves justify the excitement or the concern? Take a closer look at both sides of the debate with 3 key rewards and 1 important warning sign.
Looking for more Garmin sized opportunities?
If Garmin has sharpened your appetite for quality ideas, do not stop here. Broader research gives you more options and helps balance portfolio risk.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that highlights businesses with robust fundamentals ready for closer inspection.
- Hunt for potential mispricings through a 29 high quality undervalued stocks that lines up companies where quality metrics and current pricing appear out of sync.
- Spot future market leaders early by reviewing a 20 high quality undiscovered gems that surfaces strong fundamentals before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com