
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Charter Communications' Edge AI Expansion Means For Shareholders
- Adeia announced a multi year renewal of its intellectual property license with Charter Communications’ Spectrum brand, covering pay TV, video, broadband and mobility. At the same time, Spectrum outlined a broad edge computing rollout using NVIDIA accelerated hardware and more than 1,000 embedded facilities to host AI and low latency workloads.
- The decision to activate Spectrum’s Edge Compute Infrastructure across existing network sites suggests Charter Communications is trying to monetize sunk network and power assets by layering on AI focused compute services for enterprises and advanced automation use cases.
- We will look at how Charter Communications' investment narrative intersects with its new edge AI infrastructure push across the Spectrum network.
Scan how Charter Communications’ edge AI push compares with other network and infrastructure players by filtering for 91 AI infrastructure stocks that could also benefit as AI workloads move closer to users.
Charter Communications Investment Narrative Recap
Owning Charter Communications means believing the broadband and mobile bundle can stabilize churn and that Cox integration, cost control and lower capex can support healthier cash generation even while competition stays intense. In the near term, the key factor is whether broadband losses and video pressure ease enough to offset cost inflation and interest expense.
Right now the biggest risk is that fixed wireless and fiber rivals keep chipping away at internet subscribers, while the loss of Affordable Connectivity Program support squeezes value focused households. The latest edge AI announcements help the long term story but do not materially change that near term customer and earnings pressure.
The most relevant update is Spectrum’s move to activate computing power across more than 1,000 embedded facilities and begin commercializing the Edge Compute Infrastructure platform with NVIDIA and partners such as Cast AI, HP and WWT. This points to Charter Communications leaning on its existing network, power and fiber footprint to support AI and low latency workloads.
For you as an investor, this ECI push sits alongside the Cox integration, bundling strategy and capex glide path as a potential extra revenue line rather than a replacement for the core subscription engine. Execution risk is real. Monetizing 250 megawatts of capacity and attracting sustained enterprise demand will matter for whether edge AI becomes a meaningful EBITDA contributor.
Charter Communications Edge AI In Context Of Analyst Expectations
Charter Communications is being modeled by analysts to deliver US$71.9b in revenue and US$10.3b in earnings by 2029, based on a 9.7% yearly top line growth rate and a move from US$4.9b of earnings today to that higher profit level. This implies an earnings increase of about US$5.4b over the period.
Uncover how Charter Communications' fair value indicates a 66% potential upside to its current price that investors may see narrow more quickly than expected.
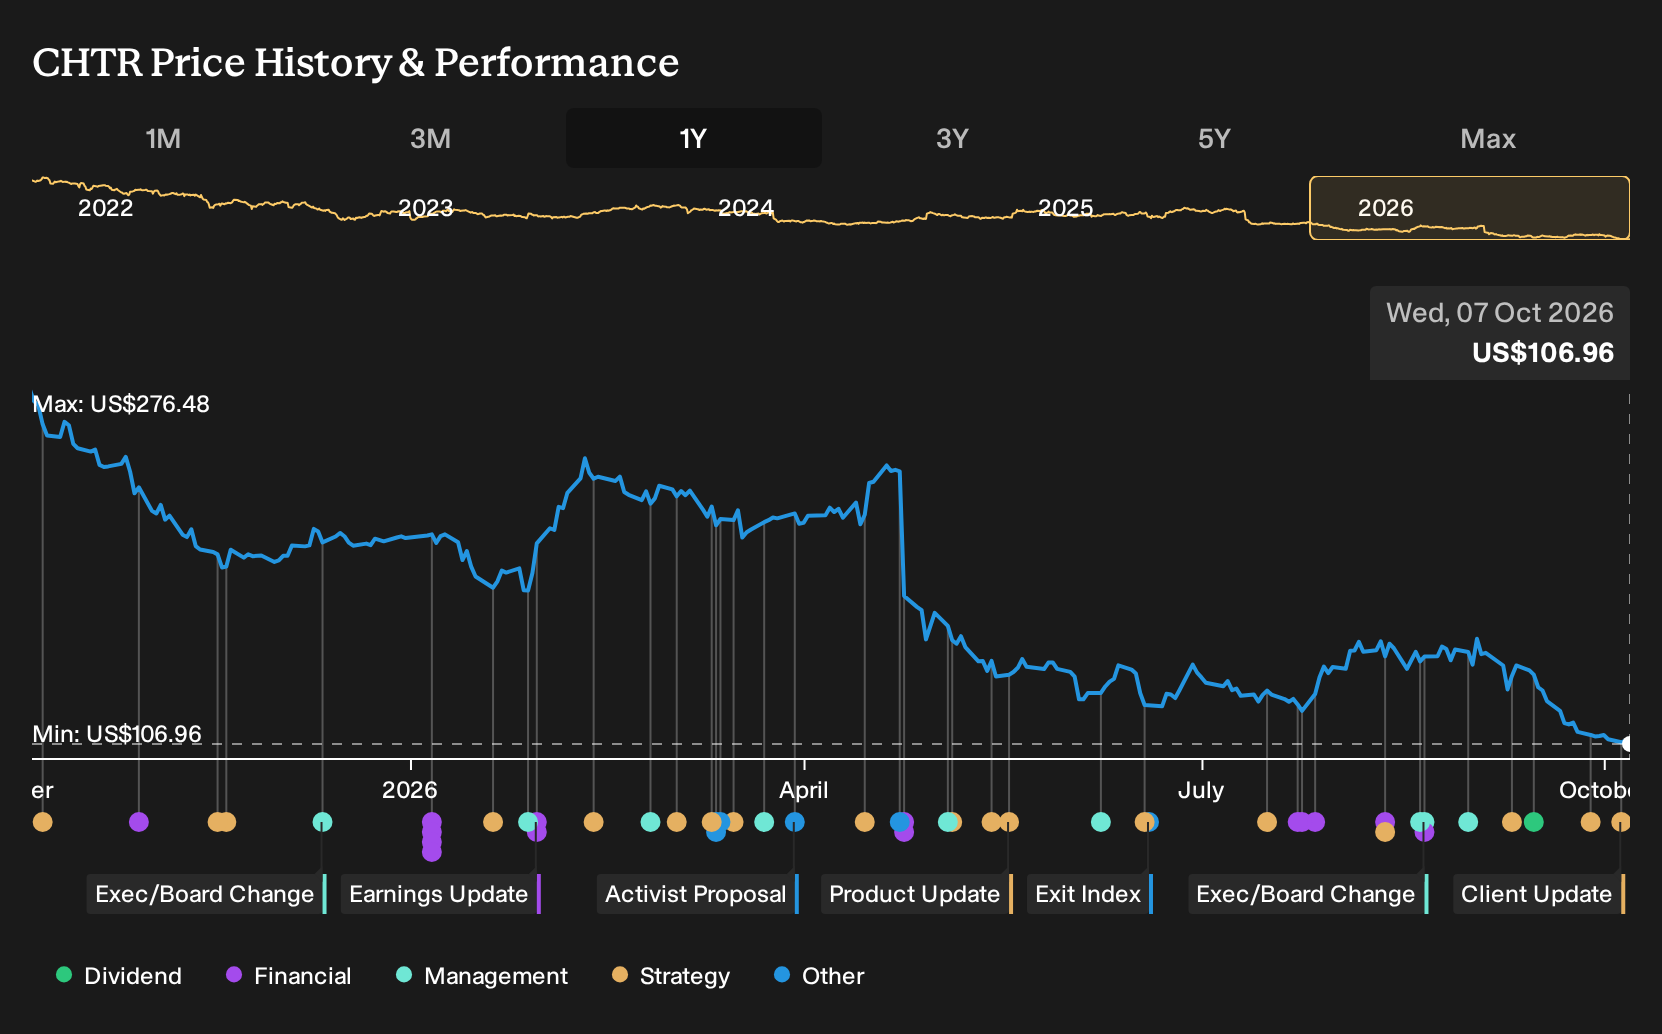
Exploring Other Perspectives
One bullish twist on Charter Communications focuses on edge AI as a margin story. The most optimistic analysts were already penciling in revenue of about US$69.9b and earnings of US$11.2b by 2029 before this news. If you think ECI and the Adeia renewal deepen that profit path, you may see their upbeat view as worth revisiting while you compare different forecasts.
Explore 6 other Charter Communications fair value estimates, including one that suggests as much as 429% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Charter Communications research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Charter Communications. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Charter Communications' overall financial health at a glance.
Looking For More Investment Ideas Beyond Charter Communications?
If the Charter Communications story has you thinking about portfolio balance and opportunity size, it can help to scan a wider field of companies that fit different roles, from income anchors to potential mispriced quality.
- For investors who want resilient balance sheets to help underpin capital preservation, consider screening for a list of solid balance sheet and fundamentals (25 results) that can act as the financial backbone of a diversified portfolio.
- If income is the priority and you are building a cash flow focused plan, look for businesses in the 8 dividend fortresses that may support more consistent payout streams.
- When hunting for potential mispriced quality and looking to get ahead of the crowd, you can scan the 20 high quality undiscovered gems that pair strong fundamentals with lower current visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com