
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is IDEXX Laboratories (IDXX) Cheap Following Its Share Price Slide?
IDEXX Laboratories (IDXX) has come under pressure recently, with the share price closing at US$506.67 and logging declines over the past month, past 3 months, year to date, and over the past year.
For IDEXX Laboratories, the recent weakness has been broad based, with the share price return down 5.36% over 30 days and 9.30% over 3 months, feeding into a year to date share price decline of 24.38%, even though the 3 year total shareholder return is still positive at 13.63%.
Broaden your watchlist beyond IDEXX Laboratories by scanning a curated set of resilient businesses in our 31 resilient stocks with low risk scores that feature lower risk scores and sturdier fundamentals.
IDEXX Laboratories still looks like a high quality vet diagnostics business on the surface, yet the share price has reset sharply. The real concern now is whether you are paying a fair price for that quality.
Most Popular Narrative: 28% Undervalued
On the most followed narrative, IDEXX Laboratories screens as undervalued, with a fair value of $701.33 versus the last close at $506.67. This puts the current weakness against a backdrop of recurring diagnostics strength and long term margin ambitions.
High customer retention and a growing installed base of premium instruments are supported by Q2 2026 CAG diagnostics recurring revenue growth of 10.3% organically despite modest U.S. clinic visit declines and by company guidance for high free cash flow conversion and 70 to 90 basis points of operating margin expansion in 2026. These factors can help IDEXX Laboratories translate recurring revenue growth into higher earnings and free cash flow.
See why 28 investors see IDEXX Laboratories as 28% undervalued.
Result: Fair Value of $701.33 (UNDERVALUED)
Still, the bullish IDEXX Laboratories script can unravel quickly if U.S. clinic visits stay weak or if higher spending on expansion and R&D weighs on margins.
Find out about the key risks to this IDEXX Laboratories narrative.
Another View: What IDEXX Laboratories Looks Like On Earnings
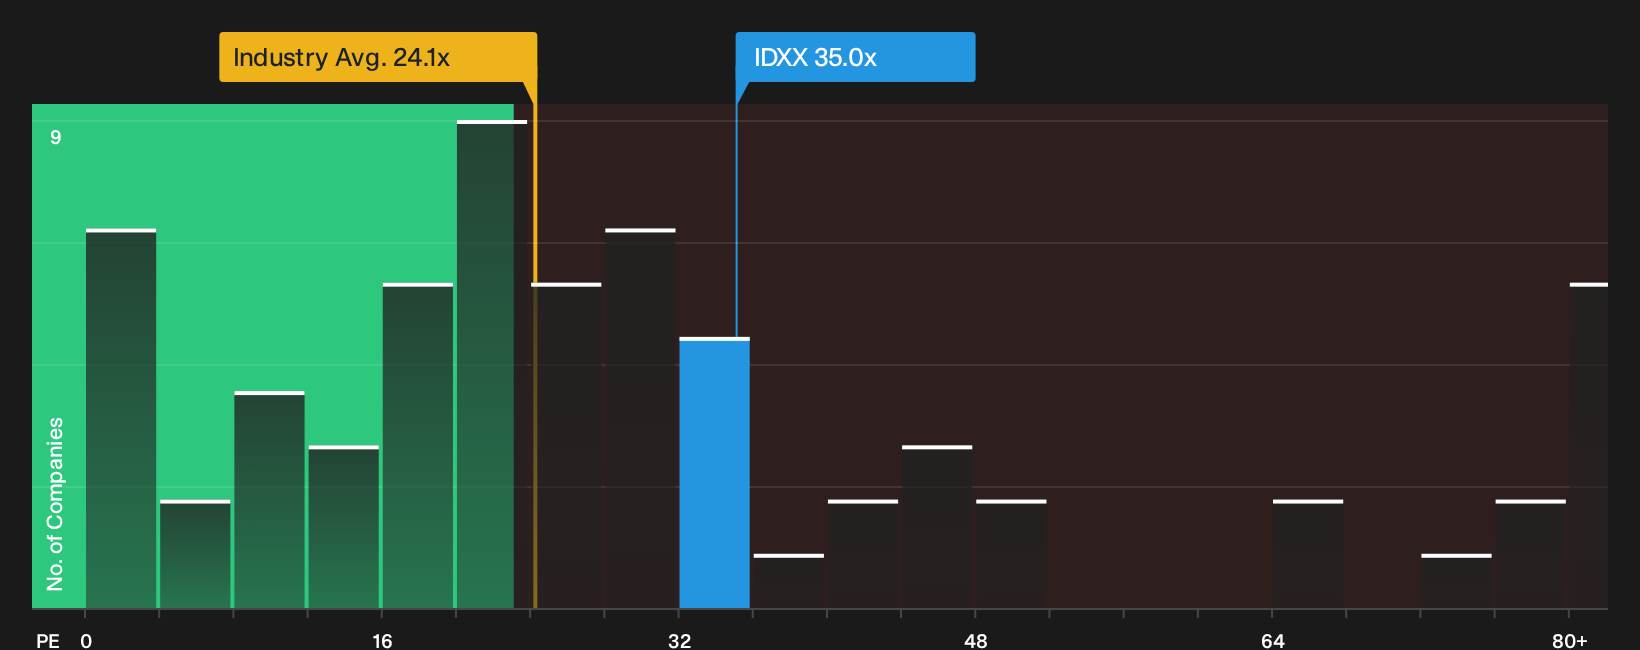
The consensus narrative paints IDEXX Laboratories as undervalued, yet the current P/E ratio of 35x tells a different story. That is higher than the US Medical Equipment industry on 24.1x, above the peer average of 33.2x, and above the fair ratio estimate of 28.6x. Paying a premium multiple when growth is slower than both the industry and the wider US market raises a simple question: How much optimism are you really comfortable baking into the price?
To see how these earnings based signals stack up against a fuller valuation breakdown, including the fair ratio and peers, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages around IDEXX Laboratories can be confusing, so move quickly from headline takes to your own view by weighing both sides through the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond IDEXX Laboratories?
Do not stop with IDEXX Laboratories. Apply the same disciplined lens across other opportunities so your portfolio does not lean too heavily on a single story.
- Target companies with strong cash generation and quality fundamentals by scanning the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing stocks in the 8 dividend fortresses.
- Shore up the defensive side of your portfolio by assessing businesses from the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com