
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Option Care Health (OPCH) Agreed To A $32.05 Buyout, Is It Fully Priced?
Option Care Health (OPCH) moved into the spotlight after agreeing to a cash buyout by Clayton, Dubilier & Rice and McKesson at $32.05 per share, implying an enterprise value near $5.8b.
That takeover premium has had a clear impact on momentum. Option Care Health’s 7 day share price return of 37.9% and 90 day share price return of 43.1% reflect investors pricing in the US$32.05 offer. The 1 year total shareholder return of 14.1% contrasts with a flatter year to date share price performance, suggesting recent enthusiasm has been heavily deal driven rather than part of a longer upward trend.
Scan for other potential takeover or re-rating stories in healthcare by reviewing the hand picked 35 healthcare AI stocks that could be next in the spotlight.
Option Care Health now trades just below a signed US$32.05 cash offer, so the real puzzle is whether the remaining spread still compensates you for deal timing and closing risk.
Most Popular Narrative: 8% Overvalued
On the latest consensus view, Option Care Health screens as modestly overvalued, with a narrative fair value of $28.58 against a last close of $31.01 that already reflects the $32.05 bid in the background. That gap matters because the narrative assumes regular trading conditions. The live price is now dominated by merger expectations and deal risk.
Growth in both acute and chronic infusion therapies is outpacing the market, driven by demographic shifts such as an aging population and higher prevalence of complex conditions. This is expanding Option Care Health's addressable market and supporting future revenue and earnings potential.
See why 3 investors see Option Care Health as 8% overvalued.
The most followed thesis uses a 7.33% discount rate and points to a fair value of $28.58, which sits below both the $31.01 trading level and the $32.05 cash offer. That suggests the current quote is leaning more on deal terms than on the longer term cash flow story implied by that narrative.
Result: Fair Value of $28.58 (OVERVALUED)
Still, the narrative around Option Care Health can be knocked off course if Stelara related chronic inflammatory headwinds deepen or if guidance is reset again.
Find out about the key risks to this Option Care Health narrative.
Another View: Option Care Health Through The P/E Lens
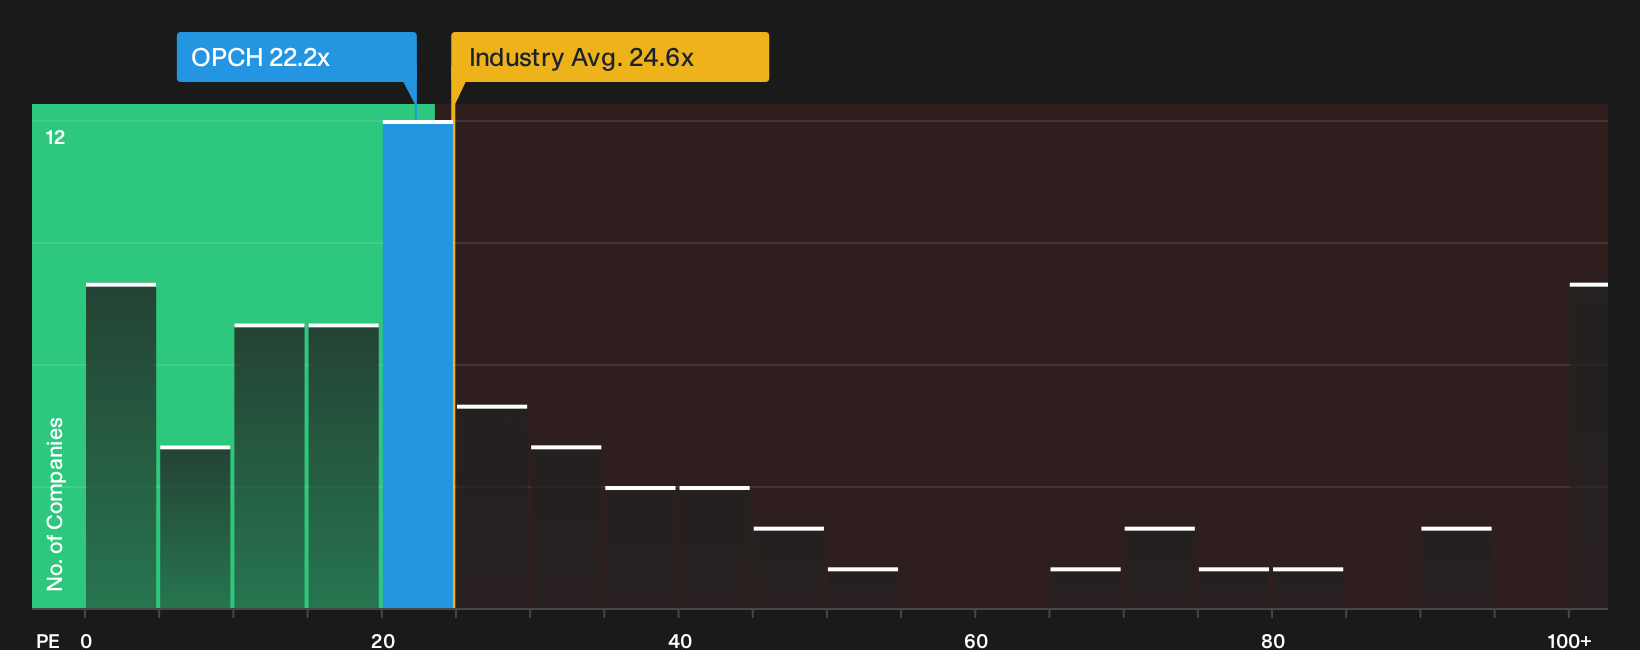
Step away from the narrative fair value and Option Care Health looks different when you just look at the earnings multiple. The stock trades on a P/E of 22.2x, below the US Healthcare industry at 24.5x, the peer group at 43.6x, and even under its own fair ratio of 26.8x. That gap points to less multiple risk than the DCF style narrative suggests. The question is whether deal risk or fundamentals will end up driving where the valuation settles.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Option Care Health's valuation and deal risk are clear, so move quickly, review the underlying data, and pressure test both sides of the story using the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Option Care Health?
If the Option Care Health story feels mostly tied to this buyout, broaden your watchlist with other focused ideas that could fit very different playbooks.
- Target income resilience by scanning for companies with reliable payouts and higher yields using the 8 dividend fortresses.
- Hunt for mispriced opportunities by running the 29 high quality undervalued stocks that combines stronger balance sheets with attractive valuations.
- Prioritise capital preservation and steadier compounding by reviewing the 31 resilient stocks with low risk scores that filters for more resilient business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com