
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is PTC (PTC) Trading At A Discount After The $22.6b Deal?
PTC has been in sharp focus after a proposed US$22.6b acquisition by Schneider Electric, and the share price moves around that news put a spotlight on one question. Are investors paying a level for PTC that is supported by what the business earns today and what its earnings can reasonably sustain over time?
- Over the past 5 years, PTC has delivered a 60.4% share price gain, which puts real weight on whether that track record is matched by the strength of its earnings profile.
- Schneider Electric's planned purchase of PTC, announced as a US$22.6b deal expected to close by 2027, can reshape expectations for the software group's future profitability and the timing of its cash generation.
- The analysts covering PTC have run their own numbers. See what analysts think PTC's shares could be worth.
The stock's next move may depend on whether PTC's current price is aligned with what its earnings justify today.
If you are weighing PTC after the Schneider Electric offer, it can help to see how other industrial software and AI players stack up by scanning 91 AI infrastructure stocks.
Is PTC a Bargain on Earnings?
The P/E ratio is a useful lens for PTC because earnings remain the core driver of how much cash the business can return or reinvest over time.
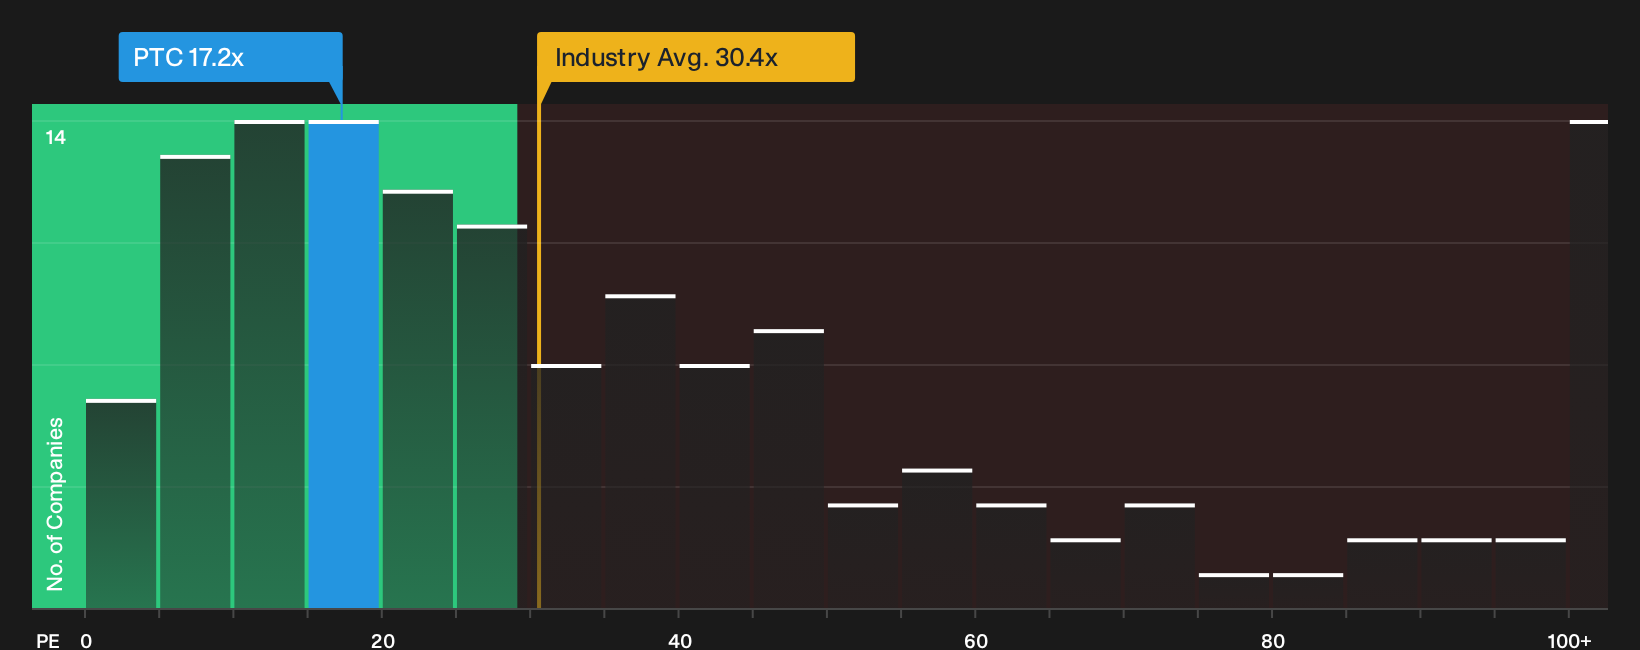
On this measure, PTC trades on a P/E of 17.2x, which is well below the broader software industry average of 30.4x and also below a peer group closer to 46.8x. The valuation model that blends in PTC's margins, growth expectations, size and risk profile points to a higher P/E as a reasonable reference point, so the current earnings multiple screens as undervalued against that tailored yardstick. Despite Schneider Electric agreeing to pay about US$22.6b for PTC, the P/E still prices the stock at a discount to many software and industrial software peers, which leaves the earnings multiple looking conservative if the business can broadly sustain its recent profitability profile. Explore the numbers behind PTC's P/E valuation.
The PTC Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the PTC valuation question leaves off by spelling out which future growth, margin and earnings paths would need to play out for the stock to look meaningfully cheaper or more expensive than it does today. Each one treats PTC's fair value as a hypothesis about how the business might perform that you can track over time, and they sit together on the platform's Community page.
Community views on PTC now split between those who see Schneider Electric's US$205 offer as a ceiling and those who focus on AI driven upside and deal certainty.
Bull case: 6% undervalued
"PTC's underlying SaaS and subscription shift is delivering stronger operating leverage than appreciated, as non-GAAP expenses are growing at half the rate of ARR..."
Discover why this Narrative puts PTC at 6% undervalued.
Bear case: 6% overvalued
"PTC is still working through elevated churn in the ServiceMax business, and this segment is described as dilutive to overall growth..."
Explore why this Narrative puts PTC at 6% overvalued.
Before you act on PTC's valuation, there is one more piece to check
The price you see reflects earnings and deal terms, but the people steering PTC and the way they are rewarded can tilt risk and reward in very different directions. See who runs PTC and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com