
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is DocuSign (DOCU) Fairly Valued After Weak Growth And Softer Deal Trends?
DocuSign stock reacts to weaker growth signals
DocuSign (DOCU) is back in focus after commentary around its modest 5.5% annual recurring revenue growth and softer long term deals sharpened concerns about demand and sales efficiency.
Investors now have to weigh these contract renewal headwinds, expectations for only tepid growth over the next year, and rising sales and marketing pressure against DocuSign’s broader e-signature and agreement management opportunity.
Recent trading reflects that debate. DocuSign’s 90-day share price return of 41.3% and 6.25% year-to-date gain show momentum building into the current US$68.90 level, even as the 1-year total shareholder return declined 3.69% and the 5-year total shareholder return fell 73.43%. This hints that investors are still reassessing long run prospects after an earlier boom and bust cycle.
Spot opportunities beyond DocuSign by scanning a hand picked 29 high quality undervalued stocks.Bulls see DocuSign as a reset growth story, while bears see a maturing tool with fading pricing power. Recent gains set the stage for one question: Do current valuation levels lean more toward optimism or caution?
Most Popular Narrative: 13% Overvalued
DocuSign’s most followed valuation narrative pegs fair value at $60.99, which sits below the recent $68.90 share price and frames the stock as slightly ahead of those fundamentals.
On a market capitalisation basis, justifying roughly $11.0 billion at a 9% discount needs about $850 million of GAAP net income in 2031, which on 7% revenue growth implies a net margin near 19%.
The buyback lowers that materially, because the same earnings are spread across fewer shares. Once you run the inputs and I can solve the constant, I will pin the exact requirement. My provisional read is that at the current repurchase pace the requirement falls to roughly 15%, which is close to the base case, meaning DocuSign is priced near fair on these assumptions rather than obviously cheap or dear.
See why 7 investors see DocuSign as 13% overvalued.
According to rcb9, the narrative hinges on a few moving parts: mid single digit constant currency revenue growth, a long runway to lift GAAP net margins from about 9.7%, and continued share repurchases all need to work together to justify the current market value.
The same storyline flags several pressure points that could tilt that balance. Intelligent Agreement Management taking a smaller share of annual recurring revenue than guided, margins not progressing toward the mid-teens, or dilution outpacing buybacks would each weaken the case that DocuSign is simply “near fair” on these assumptions.
For readers weighing that framework against their own expectations on product adoption, cost control, and capital returns, the narrative effectively says the stock price already bakes in a decent amount of execution.
Result: Fair Value of $60.99 (OVERVALUED)
Still, that fair value story wobbles quickly if Intelligent Agreement Management stalls below targets or if rising share based pay eats into the expected margin lift.
Find out about the key risks to this DocuSign narrative.
Another View: SWS DCF Model Paints A Very Different Picture
While the rcb9 framework calls DocuSign about 13% overvalued at $60.99 per share, the SWS DCF model points the other way entirely. On that approach, DocuSign at $68.90 is trading roughly 56% below an estimated future cash flow value of $158.07, which treats the current quote as heavily discounted rather than stretched. So which story feels closer to how you think the cash flows will actually play out?
Look into how the SWS DCF model arrives at its fair value.
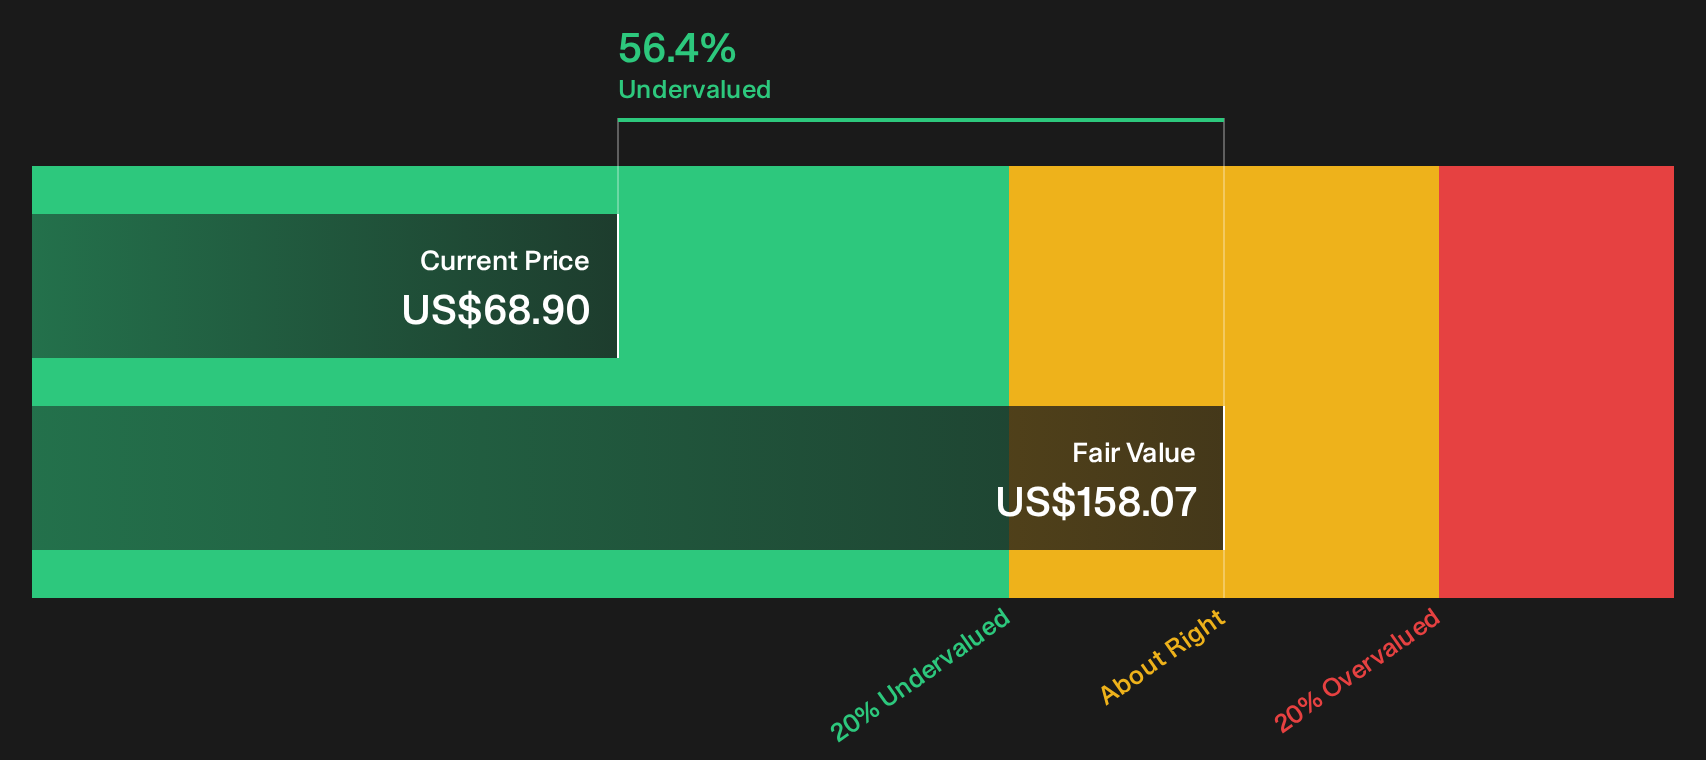
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DocuSign for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around DocuSign’s value and future can feel messy, so move quickly to your own evidence based view by weighing the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond DocuSign?
Do not stop your research at DocuSign. Broader context helps you judge risk, income potential, and value, so widen your watchlist before the next move hits.
- Hunt for potential mispriced opportunities by scanning a focused group of 29 high quality undervalued stocks that pair strong fundamentals with appealing entry points.
- Strengthen your capital preservation game by reviewing a 31 resilient stocks with low risk scores that prioritises resilient balance sheets and lower risk scores.
- Target future standouts early by checking a curated 20 high quality undiscovered gems built around companies with solid quality metrics but limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com