
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Patrick Industries (PATK) Undervalued On Its Marine And Housing Expansion?
Patrick Industries (PATK) has drawn investor attention after a sharp pullback, with the share price down about 22% over the past month and roughly 41% year to date.
At a share price of $64.92, Patrick Industries has seen momentum fade, with the 7 day share price return down 4.22% and the 30 day share price return down 21.63%, while the 3 year total shareholder return of 39.79% and 5 year total shareholder return of 25.99% present a very different experience for longer term holders.
Scan the pullback in Patrick Industries alongside other potential value opportunities with the hand picked 29 high quality undervalued stocks that share strong cash flows and solid balance sheets.
The question now is whether Patrick Industries is being priced for a weaker business or is simply caught in a sharp swing in sentiment that has run ahead of the fundamentals investors can actually see.
Most Popular Narrative: 40% Undervalued
On Simply Wall St's most followed narrative, Patrick Industries screens as undervalued, with a fair value of $108 against the last close of $64.92, which raises an obvious question about what assumptions have to play out for that gap to close.
Expansion of Patrick Industries into Marine, Powersports and Housing, where recent growth has helped offset weaker RV revenue while RV and Marine wholesale shipments remain more than 20% below 2019 levels, supports the case for a larger and more resilient revenue base as these end markets continue to contribute a greater share of sales and earnings.
See why 2 investors see Patrick Industries as 40% undervalued.
Result: Fair Value of $108 (UNDERVALUED)
Still, the Patrick Industries story can break if RV retail demand stays softer than expected, or if the planned LCI merger delivers smaller cost synergies than modeled.
Find out about the key risks to this Patrick Industries narrative.
Another View on Patrick Industries' Valuation
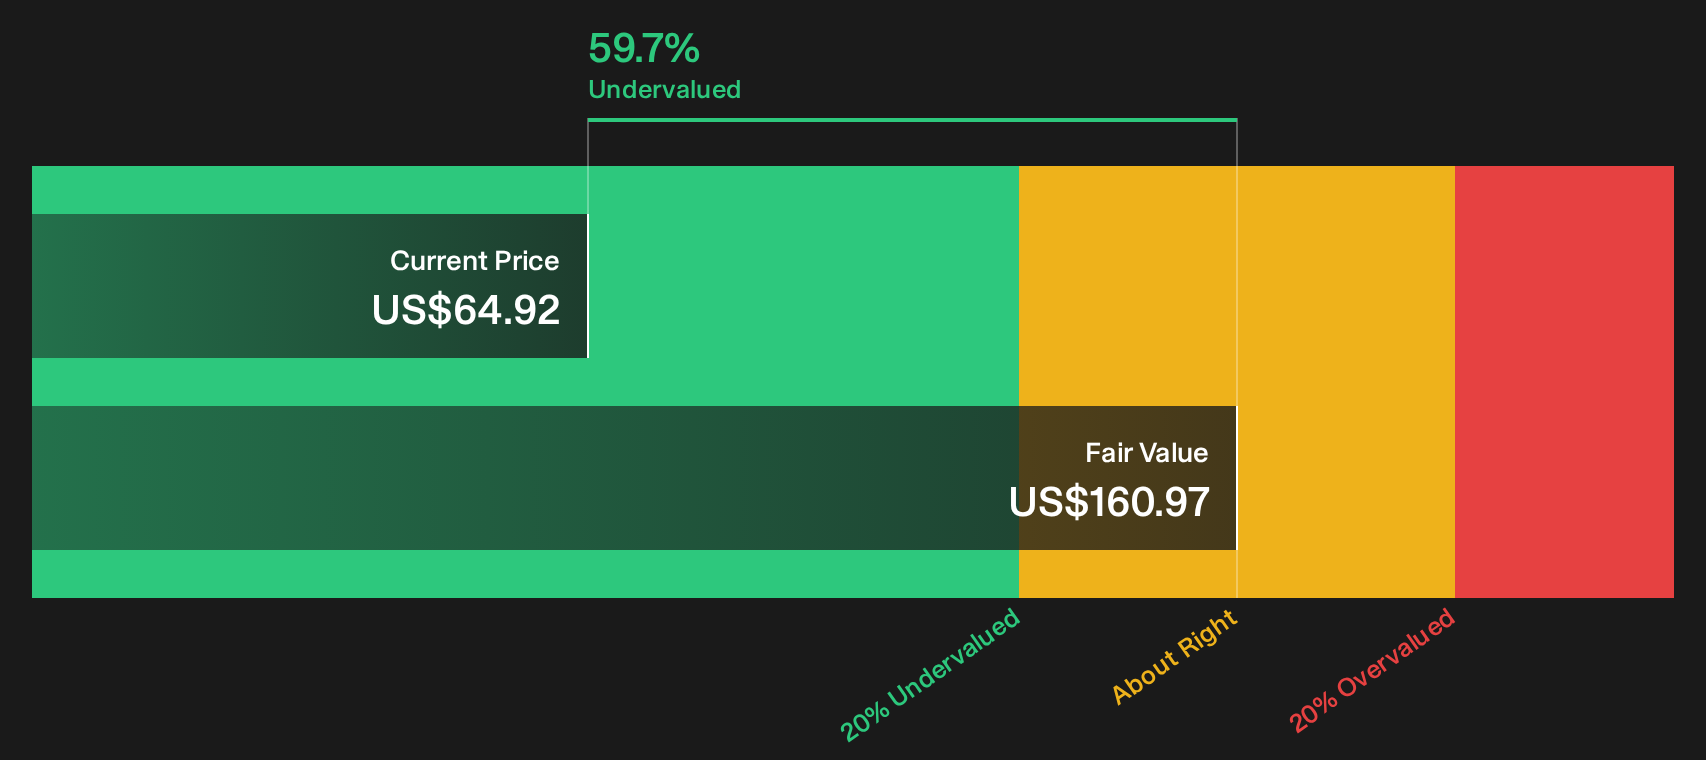
The Simply Wall St DCF model points to a very different picture for Patrick Industries, with an estimated future cash flow value of $160.97 versus the current share price of $64.92. That screens as deeply undervalued on cash flows, so how comfortable are you with the long term assumptions sitting underneath that gap?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Patrick Industries can be confusing, so move quickly: pull up the full data set, weigh the concerns against the bright spots, and ground your own view in the balance of 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Patrick Industries?
If Patrick Industries has sharpened your focus on valuation gaps and risk, do not stop here. Use the screener to spot fresh setups before the crowd moves.
- Target quality at a discount by scanning a curated 29 high quality undervalued stocks that combines stronger cash flows with healthier balance sheets.
- Build staying power into your portfolio by reviewing a focused 31 resilient stocks with low risk scores that aims for resilience rather than drama.
- Get ahead of the market by combing through 20 high quality undiscovered gems that pair solid fundamentals with relatively low attention today.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com