
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Oil And Gas Stocks With Earnings Leverage To Higher Crude Prices
Oil markets are back in the spotlight as the Iran conflict and Strait of Hormuz attacks push crude higher, reignite inflation worries, and pressure global equities. Big integrated producers can feel the shock in very different ways, from pricing power to funding costs. This article walks through 3 stocks from our Global Integrated Oil & Gas Producers screener that appear more positively exposed to this news and explains what that might mean for your portfolio thinking.
The three integrated oil and gas stocks highlighted below are only a sample and the full screen surfaced 15 more large producers with equally compelling narratives that are not covered in this article. To size up that wider peer group quickly, head straight to the Global Integrated Oil & Gas Producers screener to identify, analyze, and focus on the highest conviction ideas for your watchlist.
Hindustan Petroleum (NSEI:HINDPETRO)
Overview: Hindustan Petroleum is a large Indian refiner and fuel marketer that turns crude oil into everyday transport, aviation and household energy products.
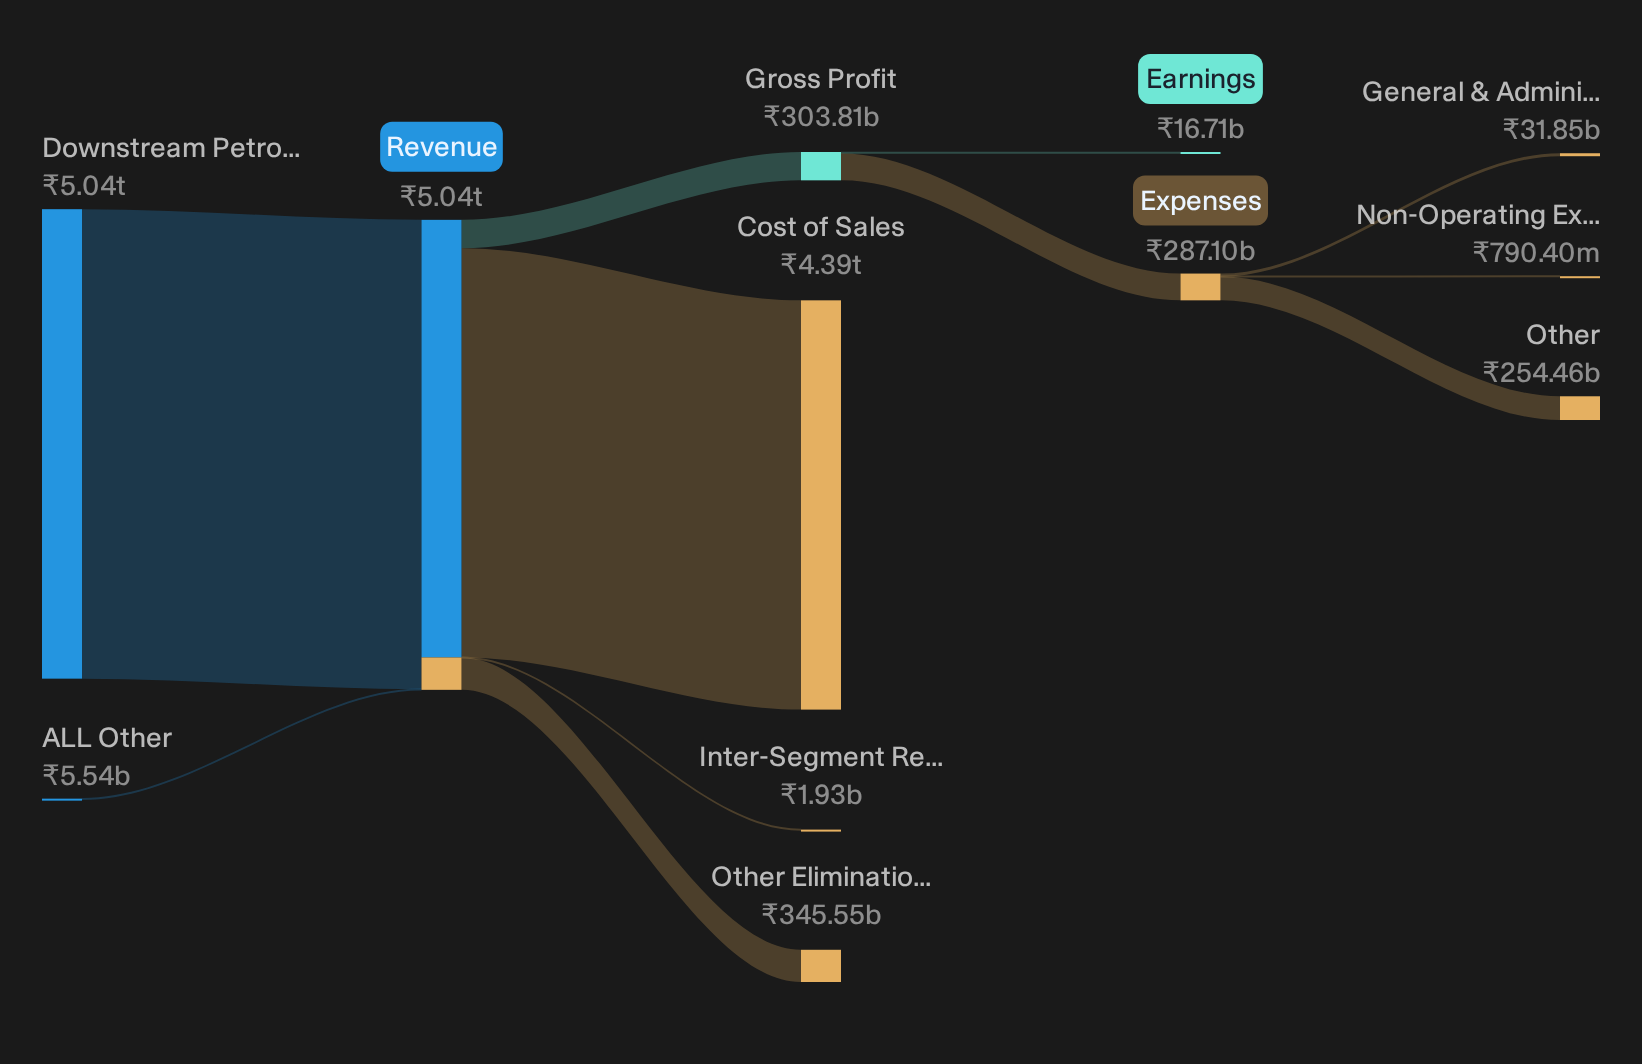
Operations: Around ₹5,035.4b of revenue comes from Downstream Petroleum, with about ₹5.5b from All Other activities and modest inter segment offsets.
Market Cap: ₹730.2b
Among the integrated producers in this screen, Hindustan Petroleum provides one of the clearest ways to focus on downstream pricing power when refined product margins remain firm after a supply shock.
"The commissioning of the Vizag residue upgradation facility, together with the guided ramp to distillate yields in the 80% range, creates room for Hindustan Petroleum to lean into more complex crude slates and sell a richer middle distillate mix once the unit is fully stabilized."
What happens to its earnings profile if a single key assumption about future product spreads and regulated pricing changes in either direction?
That hinge point on future product spreads is exactly what you unpack in the full narrative for Hindustan Petroleum, where pricing power, earnings mix and policy risk are all tested.
SNGN Romgaz (BVB:SNG)
Overview: SNGN Romgaz is a large Romanian natural gas explorer and producer that supplies domestic customers and operates storage and power assets.
Operations: Romgaz generates about RON 7.1b from Upstream gas activities, with additional hundreds of millions from Storage, Electricity, and Other services, all currently in Romania.
Market Cap: RON 68.99b
Romgaz provides exposure to natural gas within the Global Integrated Oil & Gas Producers theme, where upstream exposure to hydrocarbon prices sits alongside storage and power activities that can support cash flow resilience.
"European energy security needs and expanded export access position Romgaz for sustained pricing power, diversified revenues, and long-term margin improvement."
How might that earnings profile change if there is a single pressure point in future gas contract terms and regional demand shifts in either direction?
Those contract and demand swings are exactly what the full narrative for SNGN Romgaz unpacks, highlighting where SNGN Romgaz risk could be capped and where upside might be quietly accelerating.

ADNOC Drilling Company P.J.S.C (ADX:ADNOCDRILL)
Overview: ADNOC Drilling Company P.J.S.C provides onshore and offshore drilling, construction, and oilfield services that support ADNOC’s upstream projects across the UAE.
Operations: ADNOC Drilling generates about US$2.1b from Onshore work, US$1.4b from Offshore, and US$1.5b from Oil Field Services, all in the UAE.
Market Cap: AED90.8b
Within the Global Integrated Oil & Gas Producers theme, ADNOC Drilling offers a direct link to upstream activity, as higher crude prices are often associated with ADNOC and regional producers keeping rigs busy and multi year development plans on track.
"Multi year visibility on drilling activity, underpinned by record new contract awards (over $4.8 billion in Q2 2025), fleet expansion, and continued high utilization rates, reflects the company’s focus on topline revenue, earnings stability, and support for regional producers’ priorities around energy security and long term resource development."
The real swing factor is how one shift in ADNOC’s future drilling intensity could ripple through ADNOC Drilling’s pricing power and margins.
That drilling intensity question is exactly what the full narrative for ADNOC Drilling Company P.J.S.C tackles, highlighting where ADNOC Drilling margins could be pressured and where earnings power might be quietly accelerating.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Late money just chases momentum. Scan new watchlist candidates before they are caught by the crowd and while the information still matters. Act now.
- Spot under-the-radar strength and track 619 high quality undiscovered gems that pair solid fundamentals with stories most investors have not priced in yet.
- Ride structural demand shifts by scanning the 43 power grid technology and infrastructure stocks built around companies tied to grid upgrades, electrification, and critical infrastructure spending.
- Target durable income streams using the 227 dividend fortresses that filters for higher yielding payouts backed by balance sheets built to handle stress.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com