
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
PPL (PPL) Leans On Data Center Growth, Is It Still Below Fair Value?
PPL (PPL) has drawn investor attention after recent trading left the shares around $33.95, with performance mixed over the past month and past 3 months. The utility’s long record and multi-state footprint provide important context for the discussion.
Recent trading suggests short-term momentum in PPL is softening, with the 30 day share price return down 3.3% and the year to date share price return also down 3.3%. However, the 3 year total shareholder return of 55.5% and 5 year total shareholder return of 41.8% reflect a stronger multi year experience for long term holders.
Compare PPL’s recent swings with other regulated utilities by scanning our hand picked 43 power grid technology and infrastructure stocks for ideas in the same part of the market.
PPL has pulled back over the past quarter while still carrying a strong multi year record, which leaves investors weighing an entry at today’s price against the option of waiting. How does the current valuation compare at this point?
Most Popular Narrative: 15% Undervalued
PPL’s most followed valuation storyline anchors on a fair value of $40.13, which sits above the recent $33.95 share price and presents today’s pullback as a potential discount in that narrative view.
The accelerating growth in data center construction and new economic development, now supported by roughly 32 GW of advanced stage projects in Pennsylvania and a 13.7 GW pipeline in Kentucky, continues to point to sizable future load additions for PPL that are expected to require more infrastructure and support higher regulated revenue over time.
See why 18 investors see PPL as 15% undervalued.
Result: Fair Value of $40.13 (UNDERVALUED)
Still, the PPL story depends heavily on constructive regulation and on data center projects proceeding as planned. Any shift in policy or project timing could quickly challenge this valuation narrative.
Find out about the key risks to this PPL narrative.
Another Look At PPL’s Valuation
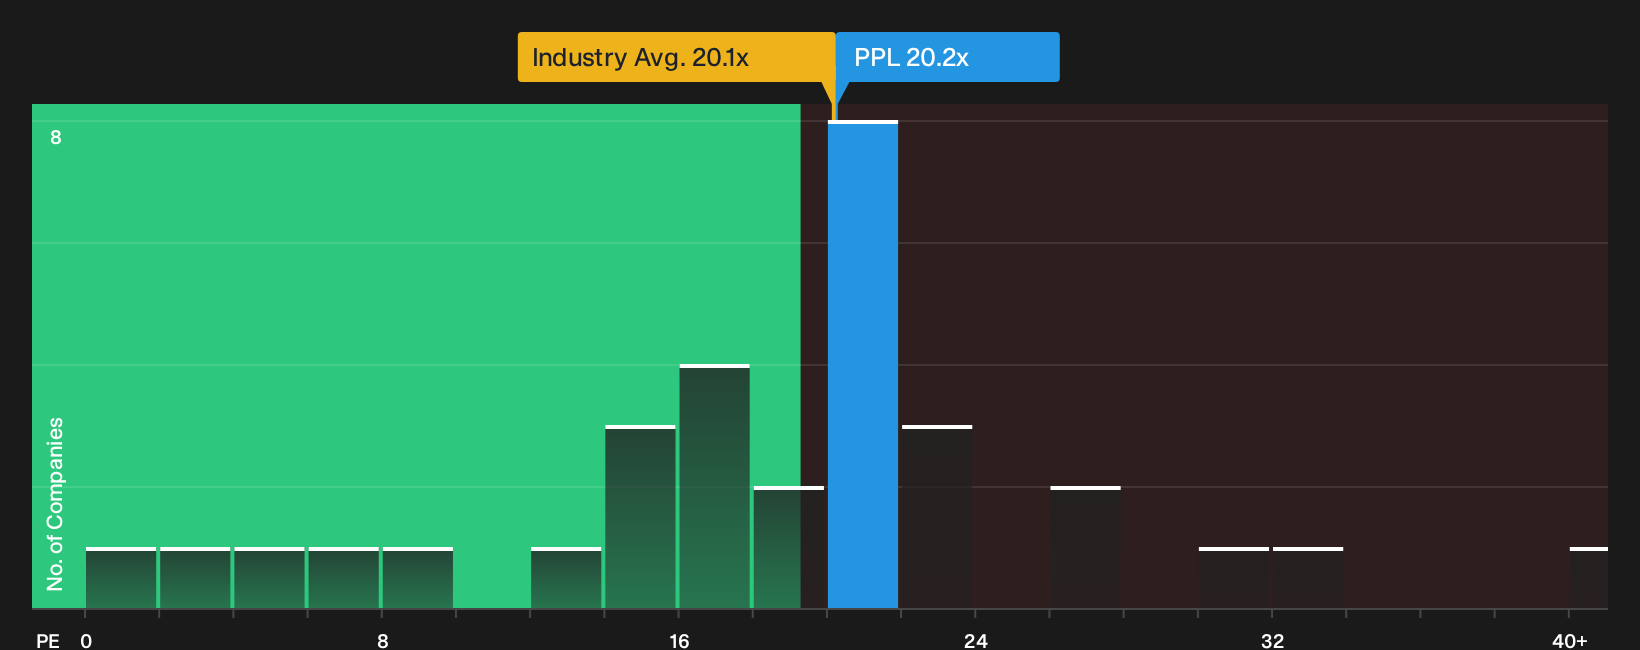
The first storyline presents PPL as 15% undervalued based on a fair value estimate of $40.13. A simple P/E check offers a different perspective. The stock trades at 20.2x earnings, which is slightly higher than the US Electric Utilities industry at 20x and above peers at 19.8x.
On the other hand, the fair P/E ratio for PPL is 20.9x, which is slightly above the current multiple and points to a narrow gap between valuation risk and opportunity rather than a clear case of mispricing. Which signal should serve as the main reference point: the narrative fair value or the earnings multiple that the market is already assigning?
See what the numbers indicate about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on PPL’s price and valuation story create a split view. If you want to move with confidence, you can dig into both sides of the argument through 2 key rewards and 2 important warning signs.
Looking for more PPL investment ideas?
If PPL has your attention, do not stop here. Fresh opportunities are always emerging, and a targeted screener can help you spot them early.
- Start building a watchlist of quality businesses trading at appealing valuations by running the 29 high quality undervalued stocks.
- Secure potential income ideas by focusing on companies that appear built to support meaningful payouts through the 8 dividend fortresses.
- Limit unpleasant surprises by filtering for companies with sturdier finances using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com