
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Hana Financial Group Doubters Overlooked
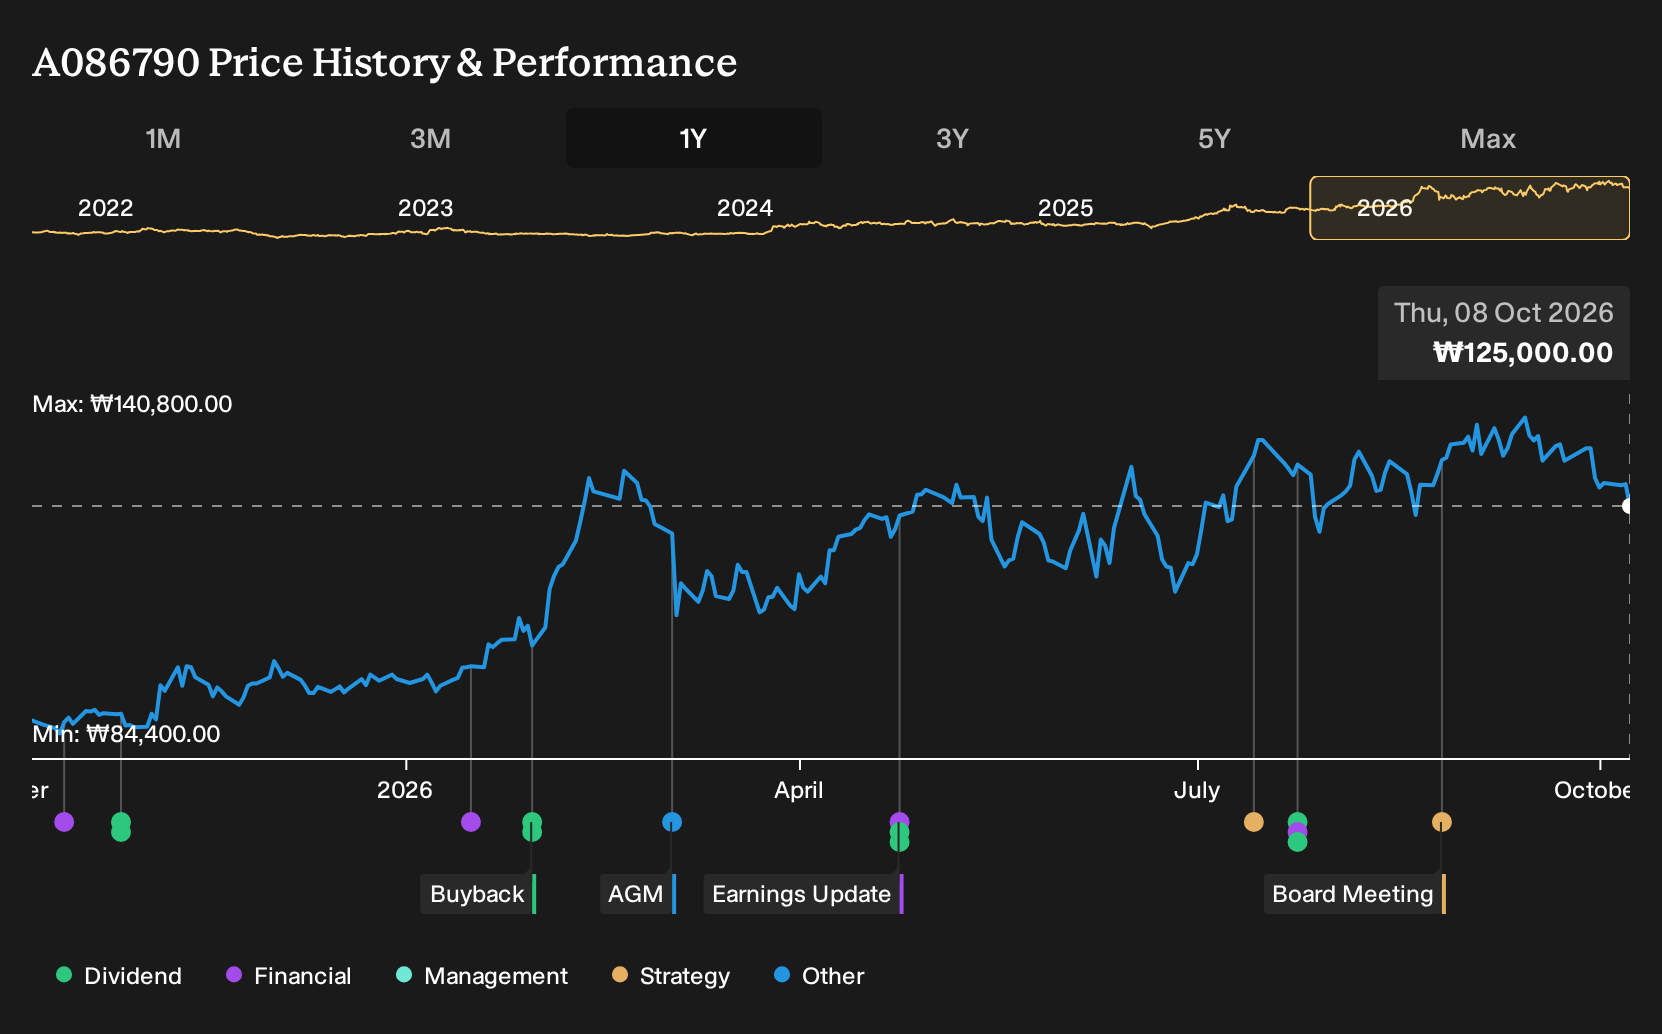
Hana Financial Group’s latest quarter put hard numbers around its digital push, with Q2 2026 revenue of ₩8,715,490 million and net income of ₩1,149,492 million on record even as net margin slipped to 13.2%. Holding Hana Financial Group over the past year would have returned 46.9%, including dividends. If you had bought on 8 October 2025, what did you need to believe about that digital and fee-income story for this outcome to feel reasonable?
The easy part of this move is behind Hana Financial Group. Zero in on 184 high quality undervalued stocks for companies trading below our estimates.
The Two Hana Financial Group Stories Investors Had To Weigh
The shares cost ₩89,300 at the start of the period, and you had to decide which story about Hana Financial Group felt more realistic.
The optimistic camp saw a Fair Value of ₩106,448, essentially the price implied if digital expansion and fee income growth supported 2.0% annual revenue gains and a future P/E of 7.9x.
The cautious side worked off a Fair Value of ₩65,500, where tougher digital competition and aging Korean demographics meant revenue declining 1.1% a year and a lower 5.7x P/E.
What The Hana Financial Group Results Put To The Test
Q2 2026 put fresh numbers on the Hana Financial Group debate. Revenue reached ₩8,715,490 million and net income was ₩1,149,492 million, which supported the optimistic argument that fee and digital income could lift the top line. Net margin moving from 15.3% to 13.2% challenged the idea that profitability would follow the same path. Overall, the evidence cut both ways.
The episode hinged on one assumption. You had to judge whether revenue gains without firmer margins still backed the upbeat digital story. When you test another bank, track whether higher fee or digital income shows up in both the income figure and the net margin, not just one of them.
What Hana Financial Group's Price Now Asks You To Believe
Hana Financial Group trades at ₩125,000 today, after a 46.9% gain over the past year. The selected Narrative’s Fair Value sits above the current price and leans on a shift from loan driven growth to capital returns and a richer fee mix from nonbank subsidiaries.
The Narrative argues that today's valuation still does not fully credit disciplined credit costs, higher ROE targets and fee based profit compounding at Hana Securities and other units.
"Bullish analysts expect Hana Financial Group to translate the Value Up Plan, higher ROE targets and rising fee income from nonbank subsidiaries into faster earnings growth than the market currently prices in. The main requirement is that Hana sustains disciplined credit costs while lifting ROE toward the new 12% goal and growing fee-based profit at Hana Securities and other nonbank units."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
One Step Beyond Hana’s Story
Hana Financial Group shows how digital banking and fee income can reshape a traditional lender.
Look one step away and you find a different angle on this shift.
Some global banks lean on their investment arms to finance major technology and infrastructure tied to data and security.
These franchises arrange financing, structure deals and manage complex payment flows for large clients.
If more of that activity moves into one integrated platform, that institution’s role could diverge sharply from a classic retail bank.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 31% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com