
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Celcomdigi Berhad Bears Were Right Before The Drop
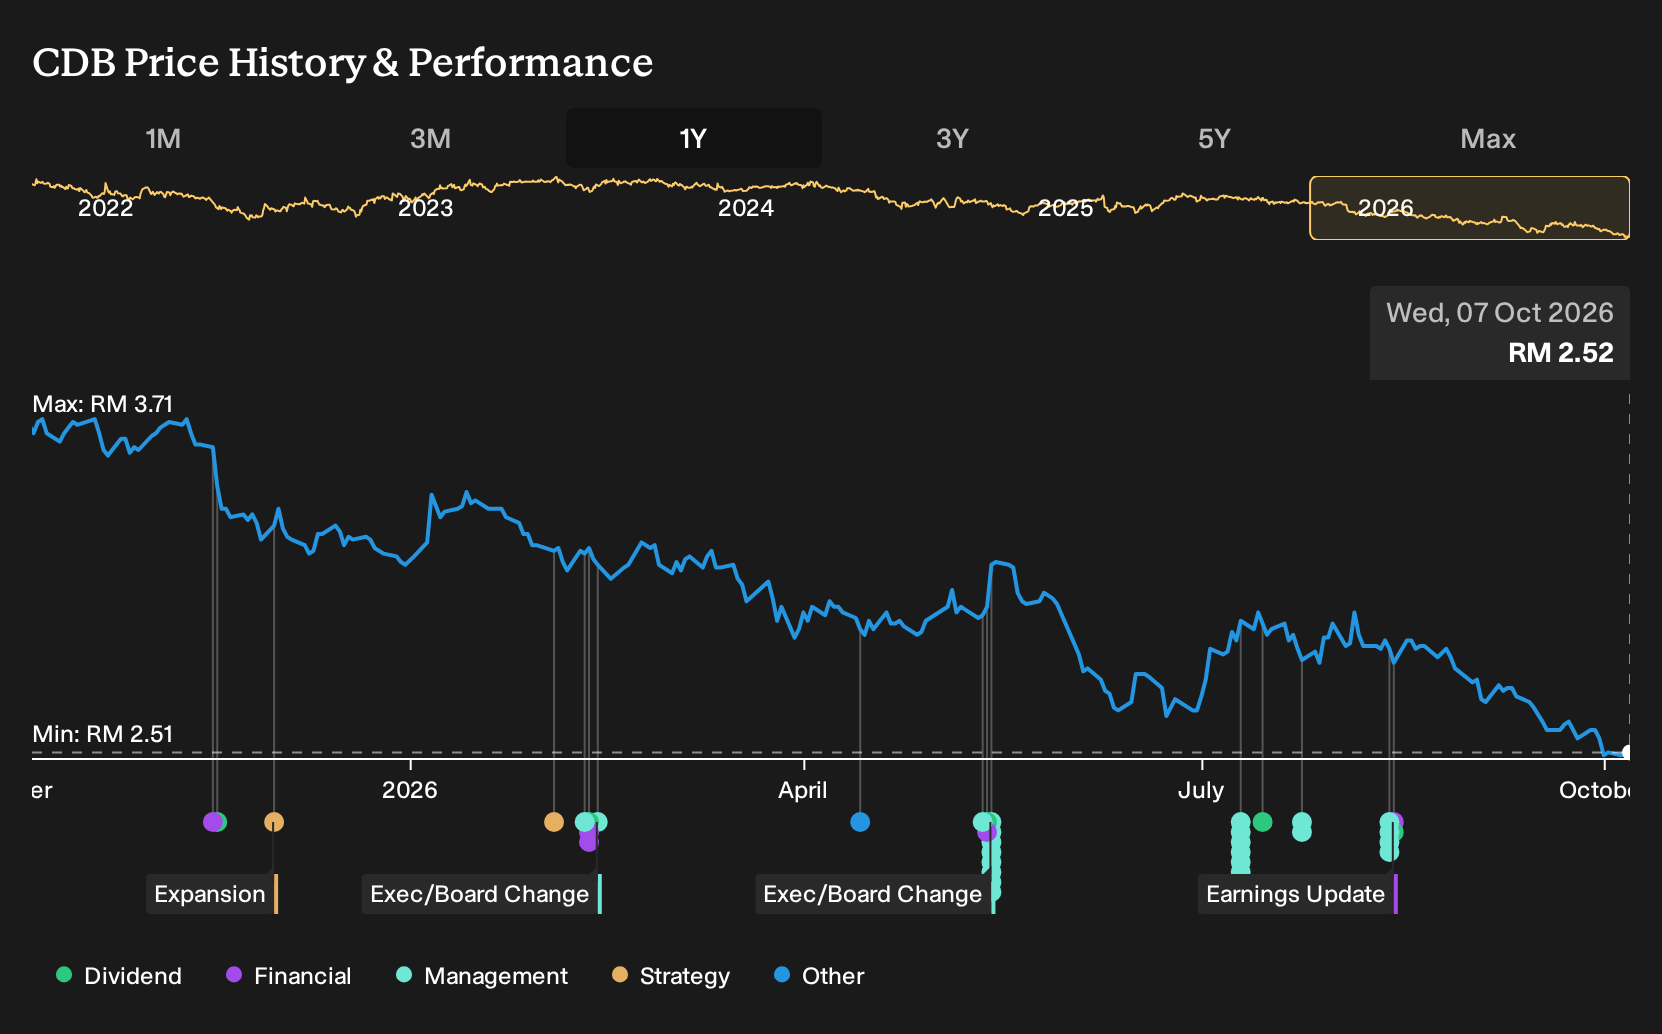
If you had decided in October 2025 that Celcomdigi Berhad looked too complicated, with clashing analyst views on network integration upside versus OTT pressure and debt risk, skipping it might feel like a close call now. For Celcomdigi Berhad shareholders, the loss over the past year was 28.6%, including dividends. With revenue at MYR 3,217m but net margin easing to 12.4% by Q2 2026, which early warning would you have focused on: execution risk or industry headwinds?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made Celcomdigi Berhad harder to judge, start where the gap is still open and scan 184 high quality undervalued stocks.
The Argument Investors Had To Settle On Celcomdigi Berhad
The shares cost MYR3.66 at the start of the period, and anyone looking at Celcomdigi Berhad then was really choosing between two stories that both sounded plausible.
On the optimistic side, the Fair Value of MYR4.05 assumed that completed network integration would lift efficiency and service quality. Analysts were modelling revenue growth of 1.4% a year and profit margins moving from 11.0% to 15.9%.
The cautious view put Fair Value at MYR3.03 and focused on pressure from over the top platforms and elevated debt. In this scenario, revenue was expected to decline 1.1% a year even as margins were projected to reach 14.6%.
What The Results Changed For Celcomdigi Berhad
Celcomdigi Berhad reported Q2 2026 revenue of MYR 3,217m compared with MYR 3,197m a year earlier, while net income slipped from MYR 439m to MYR 398m and net margin eased from 13.7% to 12.4%. That mix, with slightly higher sales but weaker profitability, challenged the optimistic case that near term integration would quickly lift margins and gave more weight to the cautious view.
The lesson is simple. When a merger story leans on efficiency gains, track net margin alongside revenue rather than just headline growth and test the thesis against each set of quarterly figures.
What You Are Paying For In Celcomdigi Berhad Today
Today Celcomdigi Berhad trades at MYR2.52, with this selected Narrative arguing that its Fair Value sits above that level based on execution of the integration story rather than a simple re rating.
The core idea is that cost synergies, higher value services and more efficient networks translate into the earnings profile the Narrative assumes.
"Key Takeaways: Network integration and modernization enhance efficiency and service quality, which in turn supports revenue and margins. Cost synergies and value-added services support profitability and the sustainability of future earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Which Company Could Surprise You Next?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 35% below our estimate - converts subsea project wins into higher-margin, longer-term service arrangements.
- Company 2 - 33% below our estimate - shifts from basic dairy staples toward nutrition-led products and expanded foreign partnerships.
- Company 3 - 47% below our estimate - transitions treatment-planning software into recurring contracts centered on AI-enabled automation workflows.
That is three of the list. See all 207 companies with the balance sheet to back it up →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com