
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Solaris Energy Infrastructure (SEI) Could Be 7% Undervalued As Yields And Fuel Markets Jolt Sentiment
Solaris Energy Infrastructure stock reacts to macro shocks
Solaris Energy Infrastructure (SEI) moved after a sharp rise in long-term Treasury yields and tighter energy markets, as the Group of Seven flagged a 100 million barrel fuel stockpile release.
For context, Solaris Energy Infrastructure now trades at US$76.46 after dropping about 4.1% on the day. The stock has still delivered a 39.0% one month share price return and a 52.1% share price gain year to date, supporting very strong one year and multi year total shareholder returns that suggest momentum has been building rather than fading.
Scan beyond Solaris Energy Infrastructure and see how other power grid and energy infrastructure plays are reacting by reviewing 43 power grid technology and infrastructure stocks in parallel with this move in yields and fuel markets.
The recent pullback in Solaris Energy Infrastructure sits against powerful trailing returns and solid reported growth in revenue and net income. Is this mostly a mood swing around macro news, or a reset of how the business is priced?
Most Popular Narrative: 6.8% Undervalued
On the most followed view, Solaris Energy Infrastructure screens slightly undervalued, with a fair value of $82 against the latest close at $76.46, and that pricing hinges heavily on how its contracted power projects and services pipeline play out over time.
While Solaris benefits from take-or-pay, long-term contracts that provide some earnings stability, its logistics business is susceptible to cyclical softness in oil-directed activity and commodity prices, which could limit cash flow generation and dampen consolidated EBITDA during industry downturns. Despite ongoing investment in automation, integration, and efficiency initiatives to improve operating leverage, the ability to maintain sustainable margin expansion could be challenged by rising competition from integrated renewable and distributed energy providers, as well as by the risk of project delays stemming from land use, permitting, or public opposition, which could negatively impact revenue visibility and growth.
See why 3 investors see Solaris Energy Infrastructure as 7% undervalued.
Result: Fair Value of $82 (UNDERVALUED)
Still, the Solaris Energy Infrastructure story could change quickly if its heavy reliance on one major data center client or its higher leverage after the US$1.25b notes offering begins to create pressure.
Find out about the key risks to this Solaris Energy Infrastructure narrative.
Another View on Solaris Energy Infrastructure valuation
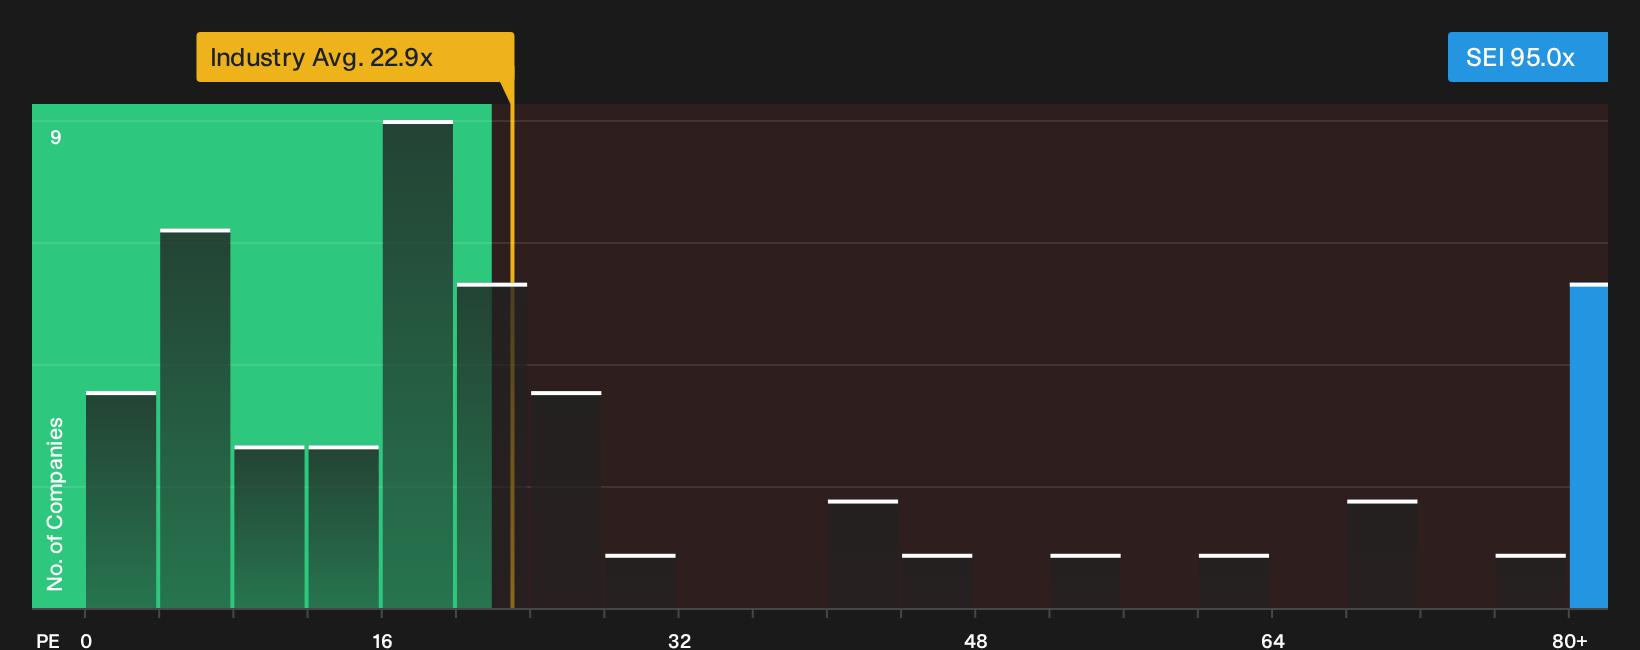
Those fair value estimates around $82 lean on detailed forecasts and analyst narratives. A simpler yardstick tells a different story. On a plain P/E basis, Solaris Energy Infrastructure trades at about 95x earnings, compared with 22.9x for the US Energy Services group, a 39.3x peer average, and a 25.4x fair ratio. That is a wide gap for anyone worried about how much optimism is already in the price.
For a closer look at how those earnings multiples stack up against what the numbers suggest as a more sustainable level, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Solaris Energy Infrastructure valuation and risk can pull you in both directions, so move quickly, review the numbers yourself, and weigh the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Solaris Energy Infrastructure?
If Solaris Energy Infrastructure has your attention, do not stop there. Broaden your watchlist with other opportunities that match your risk, income, and quality preferences.
- Target stronger value potential by scanning companies that screen as 29 high quality undervalued stocks and see which ones line up with your return and risk expectations.
- Lock in more dependable income streams by reviewing 8 dividend fortresses that could support a portfolio focused on cash returns.
- Reduce downside shocks by focusing on sturdier businesses through the 31 resilient stocks with low risk scores and see which profiles fit your comfort zone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com