
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why Ryman Hospitality Properties (RHP) Is Back In The Spotlight
How Ryman Hospitality Properties Is Positioned Today
Ryman Hospitality Properties (RHP) has drawn fresh attention after a recent price move, with the stock closing at US$119.29 on 30 September 2026. That level frames the discussion for current investors.
Recent trading has been softer, with the share price slipping 3.4% over the past month and 5.8% over the last quarter. However, Ryman Hospitality Properties still carries a 24.9% year to date share price return and a 40.7% one year total shareholder return, which signals momentum built over the past year even as shorter term sentiment has cooled.
Scan beyond Ryman Hospitality Properties and compare its momentum and fundamentals with a curated set of 20 high quality undiscovered gems that may still be flying under most investors' radar.
Bulls point to Ryman Hospitality Properties’ solid recent returns and convention focused portfolio. Bears see a pullback as the start of a longer cool down. Which case does the current valuation support?
Most Popular Narrative: 14.7% Undervalued
Against the last close at $119.29, the most followed narrative for Ryman Hospitality Properties points to a fair value of $139.79. This frames the current discount through the lens of acquisitions, group demand and entertainment earnings power.
Recent acquisitions and ongoing capital investments, now including the approximately US$1.38b Grande Lakes Orlando transaction alongside projects like meeting space upgrades at Gaylord properties and resort enhancements, extend the earlier thesis that Ryman Hospitality Properties can benefit from renewed appetite for large scale experiential travel and gatherings by adding more room, meeting and amenity capacity that can support revenue growth and future cash flow.
See why 7 investors see Ryman Hospitality Properties as 15% undervalued.
Result: Fair Value of $139.79 (UNDERVALUED)
Still, Ryman Hospitality Properties carries clear pressure points, including higher 2026 capex of US$400m to US$500m, as well as dilution and added interest from the Grande Lakes Orlando financing.
Find out about the key risks to this Ryman Hospitality Properties narrative.
Another View: What The P/E Ratio Signals For Ryman Hospitality Properties
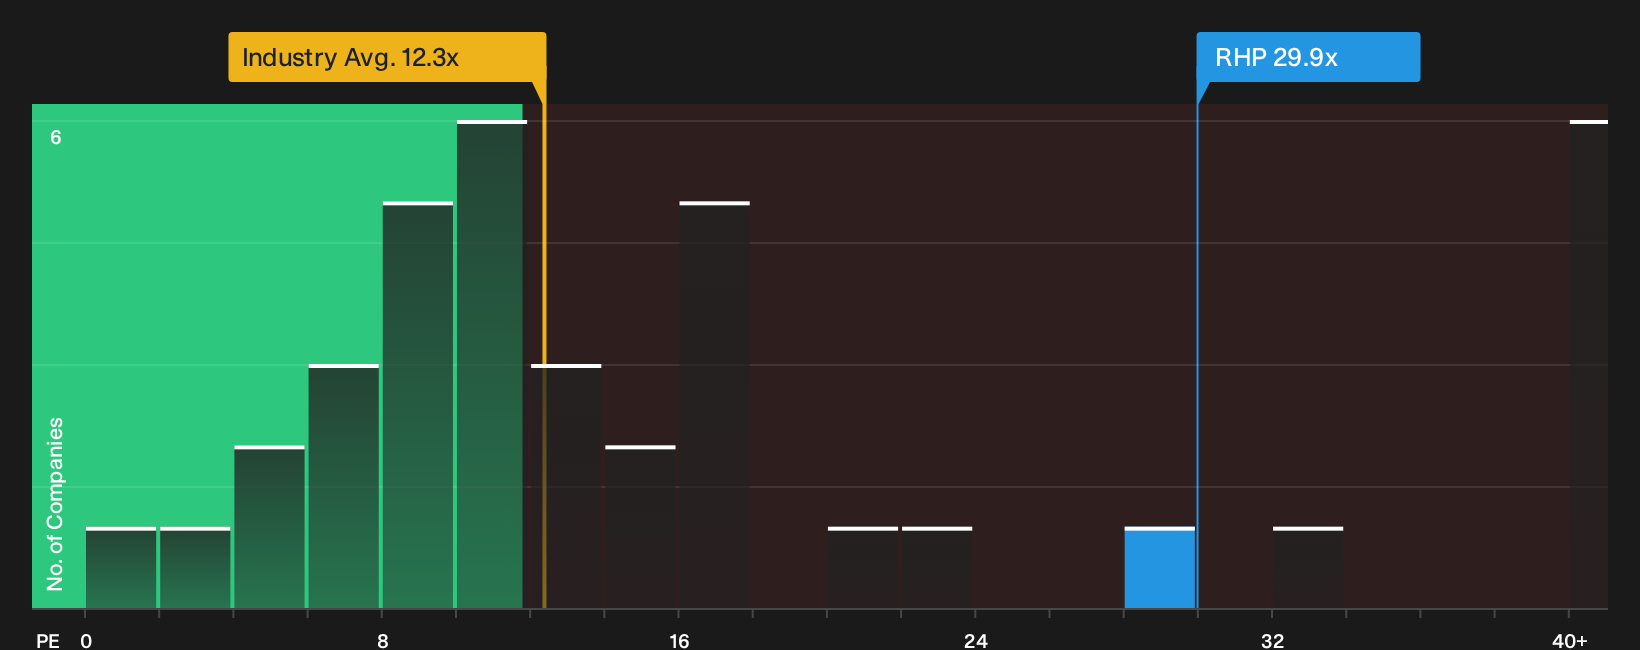
Analyst narratives frame Ryman Hospitality Properties as undervalued, yet the current P/E of 29.9x sits well above both the global Hotel and Resort REITs industry at 12.3x and the peer average at 25.8x. The fair ratio estimate of 40.9x points to further room on paper, but it also raises the question of how much valuation risk you are really willing to carry.
To see how this richer pricing stacks up in practice, including the gap between the current P/E, peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Ryman Hospitality Properties can create both opportunity and risk, so consider moving quickly, review the underlying data carefully, and shape your own judgment using the 3 key rewards and 2 important warning signs
Ready For More Ideas Beyond Ryman Hospitality Properties?
Ryman Hospitality Properties gives you a clear reference point, but your next move likely comes from comparing it with fresh ideas that match your own risk and income goals.
Use the Simply Wall St screener to quickly surface new possibilities before other investors get to them, and keep your watchlist working harder for you.
- Target potential mispricing by scanning a curated set of 29 high quality undervalued stocks that pair quality with compressed valuations.
- Strengthen your income stream by reviewing a focused group of 8 dividend fortresses that emphasise yield alongside fundamentals.
- Dial back risk without stepping away from the market by filtering for 31 resilient stocks with low risk scores that prioritise resilience and balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com