
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Pharvaris (PHVS) Is Getting Fresh Attention, What Is Behind It?
Investor focus around Pharvaris (NasdaqGS:PHVS) has picked up after a Pharvaris-funded hereditary angioedema study in Advances in Therapy highlighted gaps between guideline care and real-world practice, along with clear patient preference for daily oral treatments.
Recent price action reflects that tension between promise and risk. Pharvaris shares have pulled back, with a 30-day share price return down 10.1% and a 90-day share price return down 11.9%. At the same time, the year-to-date share price return sits at 19.6% and the 1-year total shareholder return is 37.9%, suggesting longer term holders have still seen gains while shorter term momentum has cooled after the latest clinical and conference updates.
Spot other rare-disease developers that investors are watching by scanning our hand picked list of 20 high quality undiscovered gems while you assess what this latest Pharvaris data could mean.Pharvaris now trades at a steep discount to both analyst targets and intrinsic value estimates after the recent pullback. Is that pricing in real clinical and execution risk, or has caution started to overshoot?
Most Popular Narrative: 45% Undervalued
On the most followed narrative, Pharvaris screens as materially undervalued, with a fair value of about $57.33 against a last close of $31.68. This puts a lot of weight on how far deucrictibant can reach across hereditary angioedema and related conditions.
Combined development of deucrictibant immediate release for on demand use and extended release for prophylaxis, backed by data supporting safe concurrent use, can position Pharvaris to capture both acute and chronic hereditary angioedema treatment spend and potentially support higher overall revenue per patient as physicians consolidate therapy around a single mechanism.
See why 2 investors see Pharvaris as 45% undervalued.
Result: Fair Value of $57.33 (UNDERVALUED)
Still, Pharvaris carries real pressure points, including undecided 2027 regulatory decisions for deucrictibant and ongoing quarterly losses that could eventually require fresh capital.
Find out about the key risks to this Pharvaris narrative.
Another View: Pharvaris Looks Expensive On P/B
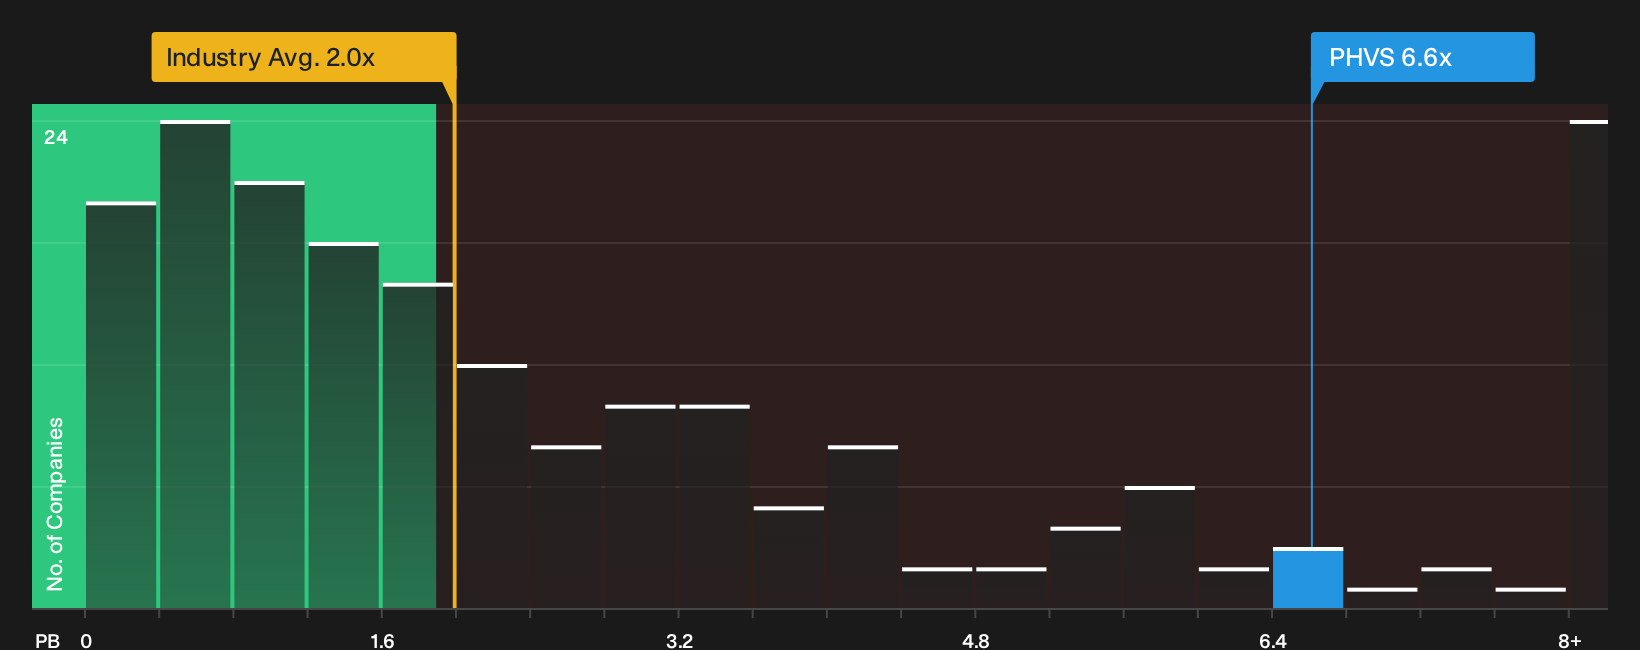
On a very different measure, Pharvaris trades on a P/B of 6.6x, while peers sit closer to 1.9x and the wider US pharmaceuticals group is around 2x. That gap points to a rich valuation on balance sheet terms. Is book value the wrong anchor for a late stage biotech story like this?
Investors weighing that question may want to see how this stacks up against a fuller valuation breakdown before leaning too hard on any single ratio. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Pharvaris can feel confusing, so move quickly, study the data first hand, then weigh the 2 key rewards and 2 important warning signs.
Looking for more Pharvaris-sized investment ideas?
Do not stop with Pharvaris alone. Use the Simply Wall Street Screener to uncover fresh opportunities before they move and keep your watchlist ahead of the crowd.
- Target value first and filter for strong businesses that may trade below their estimated worth through our curated set of 29 high quality undervalued stocks.
- Lock in dependable income streams by reviewing a focused group of 8 dividend fortresses that aim to combine yield with resilience.
- Lower portfolio stress and concentrate on resilience by scanning a refined universe of 31 resilient stocks with low risk scores that prioritize steadier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com