
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kulicke And Soffa Industries (KLIC) Stock Still Looks Stretched After AI Demand Update
Kulicke and Soffa Industries has seen its share price climb sharply over the past year, which puts a spotlight on whether the current valuation is adequately supported by its earnings power. With the stock now attracting more attention, the key issue is how that recent performance lines up with what the business is actually earning.
- The stock has returned 135.9% over the past year, which raises the question of how much of that move is backed by Kulicke and Soffa Industries' earnings profile versus changing expectations.
- Recent demand in semiconductor and memory applications, including AI led data center projects, may support expectations for stronger profitability and potentially more resilient earnings over time.
- Your read on Kulicke and Soffa Industries is one view; the desks covering it have another. See what analysts think Kulicke and Soffa Industries's shares could be worth.
The issue now is whether Kulicke and Soffa Industries' current share price is justified by the earnings that investors are effectively paying for today.
To assess whether Kulicke and Soffa Industries' sharp 1 year share price move aligns with its earnings profile, it can be helpful to compare it with a wider set of 91 AI infrastructure stocks
Does Kulicke and Soffa Industries Look Pricey on Earnings?
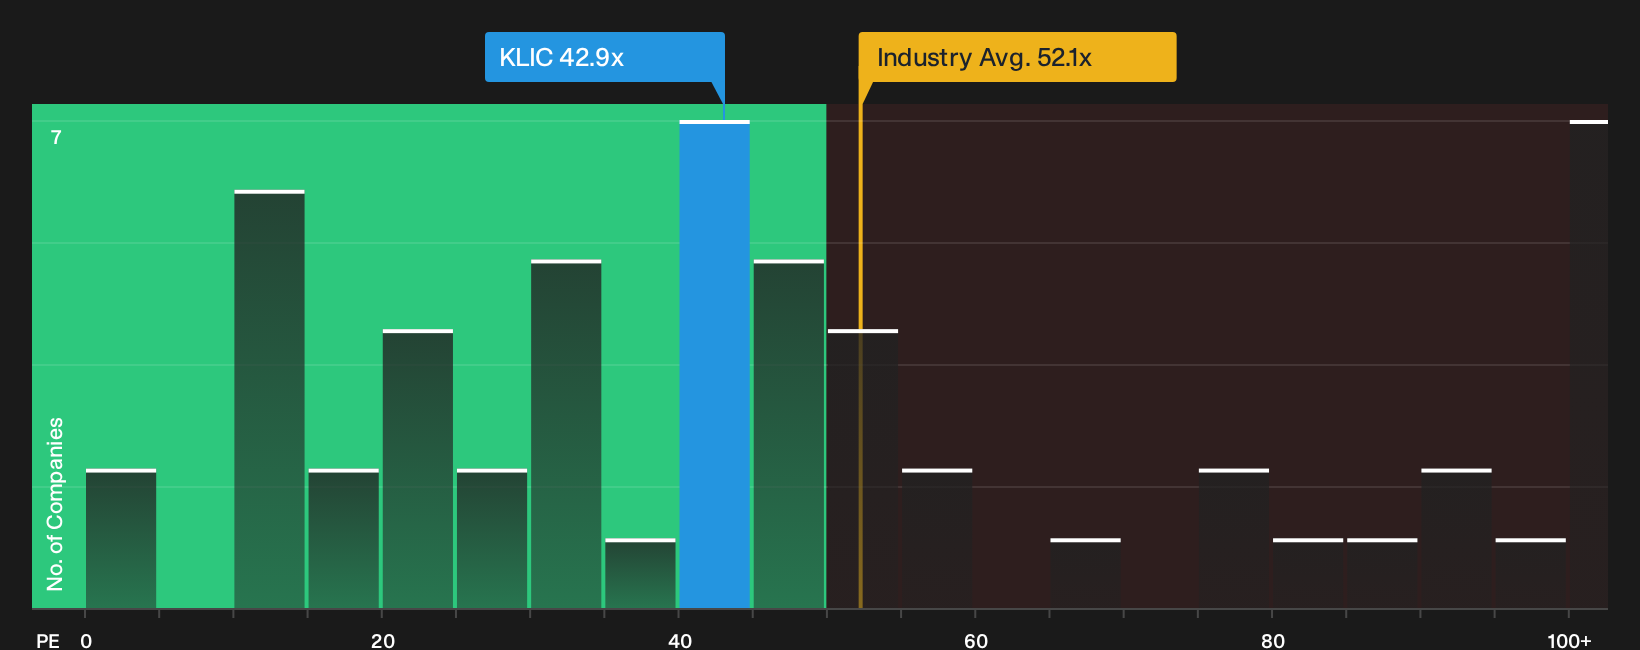
The P/E ratio suits Kulicke and Soffa Industries because earnings remain a central driver of how investors frame semiconductor equipment valuations. The stock currently trades on about 42.9x earnings, which is below the broader semiconductor sector average of roughly 52.1x and under the peer group near 63.4x. For a reader, that means the market is already assigning Kulicke and Soffa Industries a meaningful premium to many non tech sectors, but is still valuing its profit stream below a lot of chip related peers.
A fair value model that adjusts for growth, margins, size and risk points to a lower P/E as more typical for this business, which leaves the current 42.9x looking overvalued on this specific lens. Because management recently highlighted stronger demand tied to AI led data center projects and firmer revenue guidance into fiscal 2027, some investors may view this richer P/E as a reflection of confidence in that earnings trajectory rather than a simple anomaly. The key question for you is whether the earnings power Kulicke and Soffa Industries delivers over time justifies paying this kind of multiple today. Explore the numbers behind Kulicke and Soffa Industries's P/E valuation.
The Kulicke and Soffa Industries Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Kulicke and Soffa Industries pick up where the P/E debate leaves off and set out what kind of growth, margins and earnings profile would need to occur for the shares to appear meaningfully undervalued or expensive relative to today's price. Rather than relying on a single multiple or model output, each narrative explains the key assumptions behind its fair value view so you can track those inputs against actual results on the Community page.
One of the top community narratives on Kulicke and Soffa Industries: 17% undervalued
"New high-precision dispense platforms such as ACELON are aligned with growing assembly complexity across multiple end markets..."
Discover why this Narrative puts Kulicke and Soffa Industries at 17% undervalued.
Kulicke and Soffa Industries’ valuation still hinges on who is steering the ship
Price multiples only tell part of the story. The real open question is whether the leaders directing Kulicke and Soffa Industries, and the way they are rewarded, line up with how you want value to be created. See who runs Kulicke and Soffa Industries and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com