
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 India Consumer Staples Stocks With Pricing Power As Inflation Stays Hot
Inflation is back on centre stage in India, with food bills climbing, fuel linked to Brent crude above $100 and the RBI lifting the repo rate to 5.50%. That mix can punish some sectors while creating room for certain consumer staples and essential goods stocks to defend demand. This article unpacks that story and walks through three stocks exposed to these inflation trends that may deserve a closer look now.
The three stocks below are just a starting sample, since the full screen surfaced 68 more India focused consumer staples and essential goods companies with equally compelling narratives that are not covered here.
If you want to identify resilient inflation beneficiaries and analyze them side by side, head straight into the India Domestic Inflation Beneficiaries – Consumer Staples and Essential Goods screener.
Nestlé India (BSE:500790)
Overview: Nestlé India manufactures and sells branded packaged foods and beverages in India, covering daily staples like dairy, noodles, coffee, confectionery and nutrition.
Operations: The business reports about ₹243.95b in Food revenue, with roughly ₹233.32b generated in India and the rest from exports and unallocated items.
Market Cap: ₹2.55t
Nestlé India fits this inflation focused screen because it sells everyday food staples where brand strength and pricing power can matter more than short term cost spikes. This makes the expansion story especially important for investors tracking how resilient demand might be sustained.
"Expansion of Nestlé India’s direct distribution network, including a near 4x increase in distribution points since 2021 and the addition of around 500,000 retail outlets over five years, can support higher rural and small town penetration that feeds future revenue growth."
The real test for Nestlé India is how one unresolved pressure ultimately shapes the balance between volume momentum, pricing and margins.
That unresolved pressure is exactly what the full story unpacks, so read the full narrative for Nestlé India to see where pricing, volumes and margins could decouple next.

ITC (NSEI:ITC)
Overview: ITC is a large Indian FMCG group selling everyday staples, packaged foods, cigarettes and personal care essentials, alongside paper, agri and hotels.
Operations: ITC generates about ₹2b in FMCG cigarettes revenue, roughly ₹252.1b from other FMCG, ₹192b from agri and ₹89.6b from paperboards, paper and packaging.
Market Cap: ₹3.33t
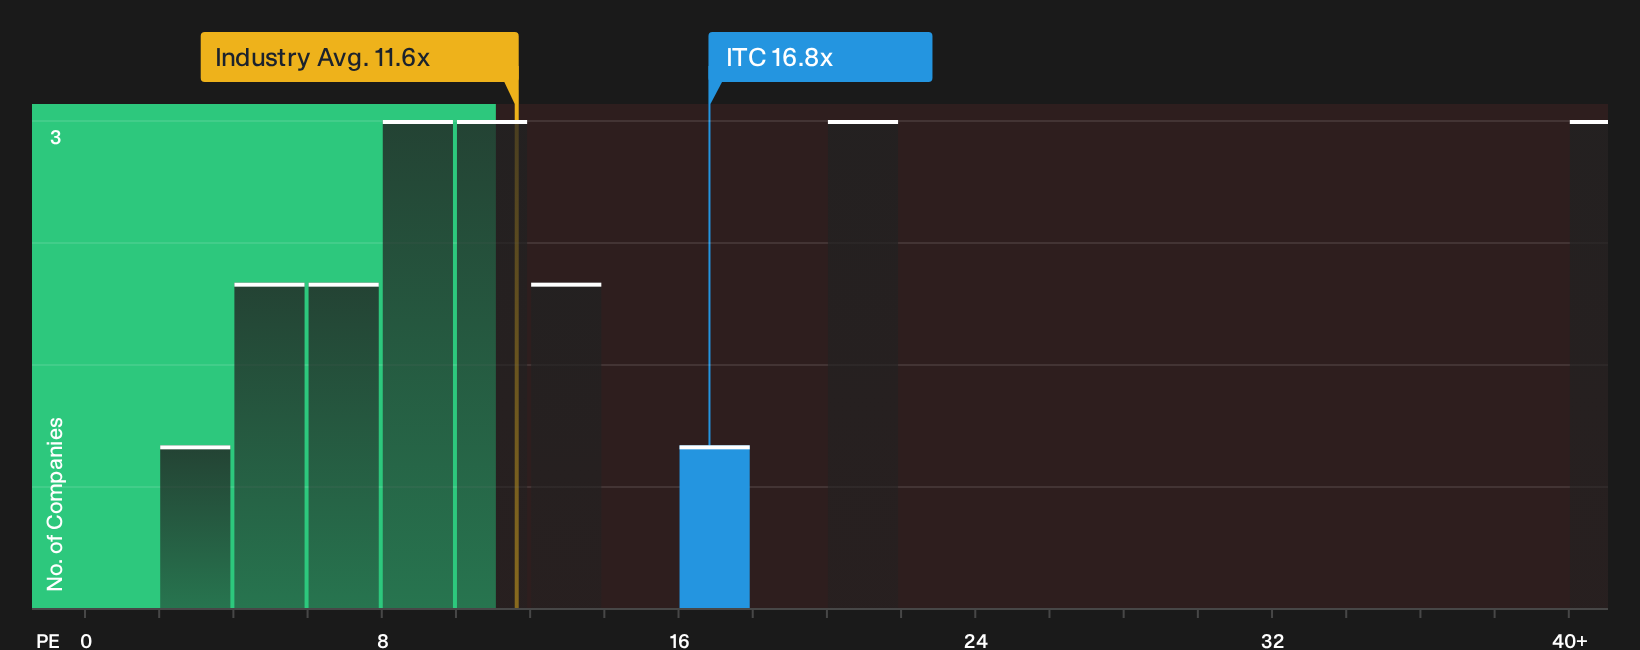
ITC offers a broad shelf of essential products, net margins of about 25.9% and a 27.7% ROE, which can matter when inflation is pressuring weaker consumer stocks. The combination of a 16.8x P/E, a 5.46% dividend yield and non discretionary categories may warrant attention if any unseen pressure on dividend coverage and funding costs moves in an unfavorable direction.
If you want to see how that risk reward tension lines up in detail, review the 2 key rewards and 1 important warning sign to see what might be getting overlooked.
Britannia Industries (NSEI:BRITANNIA)
Overview: Britannia Industries sells mass market biscuits, cakes, breads and dairy staples in India and abroad, targeting everyday food consumption.
Operations: Britannia generates about ₹194.7b in Foods revenue, reflecting a predominantly biscuits and packaged bakery focused portfolio.
Market Cap: ₹1.15t
Britannia Industries fits this inflation beneficiary screen because biscuits and bakery items sit in the weekly basket for millions of households, where small pack tweaks and recipe choices often matter more to shoppers than headline price tags.
"Deeper rural distribution, premium innovation and quick commerce expansion are set to drive long-term topline growth and greater market share."
What happens to Britannia’s margins if one quietly rising input or funding cost starts to move faster than the next round of price packs?
If that cost curve really starts to move, read the full narrative for Britannia Industries to see whether Britannia Industries is quietly building pricing muscle or risking a squeeze.

Seeking Alternatives Before The Crowd?
Fresh ideas move first, not last. Some themes could be building breakout momentum while they are still under the radar for now, so do not delay and get in early.
- Target dependable cash generators and scan a curated list of solid balance sheet and fundamentals (207 results) that focuses on resilient businesses before the crowd chases stability again.
- Review potential income momentum and a hand picked 224 dividend fortresses that could appeal if regular cash payouts sit at the centre of your plan.
- Spot possible growth stories early and work through a focused 619 high quality undiscovered gems curated for quality that many investors may not have caught yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com