
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Hewlett Packard Enterprise (HPE) Expensive As AI Orders And Networking Growth Lift Optimism?
Why Hewlett Packard Enterprise stock is back in focus
Hewlett Packard Enterprise (HPE) has jumped back onto investor radars after a $1.2b Vultr order for AI racks, fresh AMD EPYC powered servers, and higher networking growth expectations.
The share price has surged to US$72.09, with a 38.63% 1 month share price return and a 46.79% 3 month share price return, as investors react to Hewlett Packard Enterprise’s Vultr deal, new AMD EPYC servers, and networking growth targets. The 5 year total shareholder return of 460.84% shows how long term holders have been rewarded.
Scan Hewlett Packard Enterprise’s AI surge compared with a curated pack of other data center infrastructure players by reviewing performance, fundamentals, and momentum across 91 AI infrastructure stocks.
Bulls point to Hewlett Packard Enterprise’s AI orders and networking targets as the start of a new chapter. Skeptics see a hot story priced in after a rapid run. Which case aligns better with today’s valuation metrics?
Most Popular Narrative: 6% Overvalued
Hewlett Packard Enterprise last closed at $72.09, while the most followed narrative pegs fair value at $68.08, so the story centers on whether current AI and networking optimism already prices in much of the upside.
Strategic acquisitions and expansion in high-growth technologies, including the integration of Juniper, launches of next-gen Gen12 servers, and AI-driven management platforms, are enhancing HPE's competitive positioning in edge, networking, and AI, laying the groundwork for continued share gains and outsized revenue growth relative to traditional industry averages.
See why 87 investors see Hewlett Packard Enterprise as 6% overvalued.
Result: Fair Value of $68.08 (OVERVALUED)
Still, heavy dependence on legacy hardware, and any stumble integrating Juniper or scaling networking, could quickly challenge the current Hewlett Packard Enterprise optimism.
Find out about the key risks to this Hewlett Packard Enterprise narrative.
Another View: Hewlett Packard Enterprise on Earnings Multiples
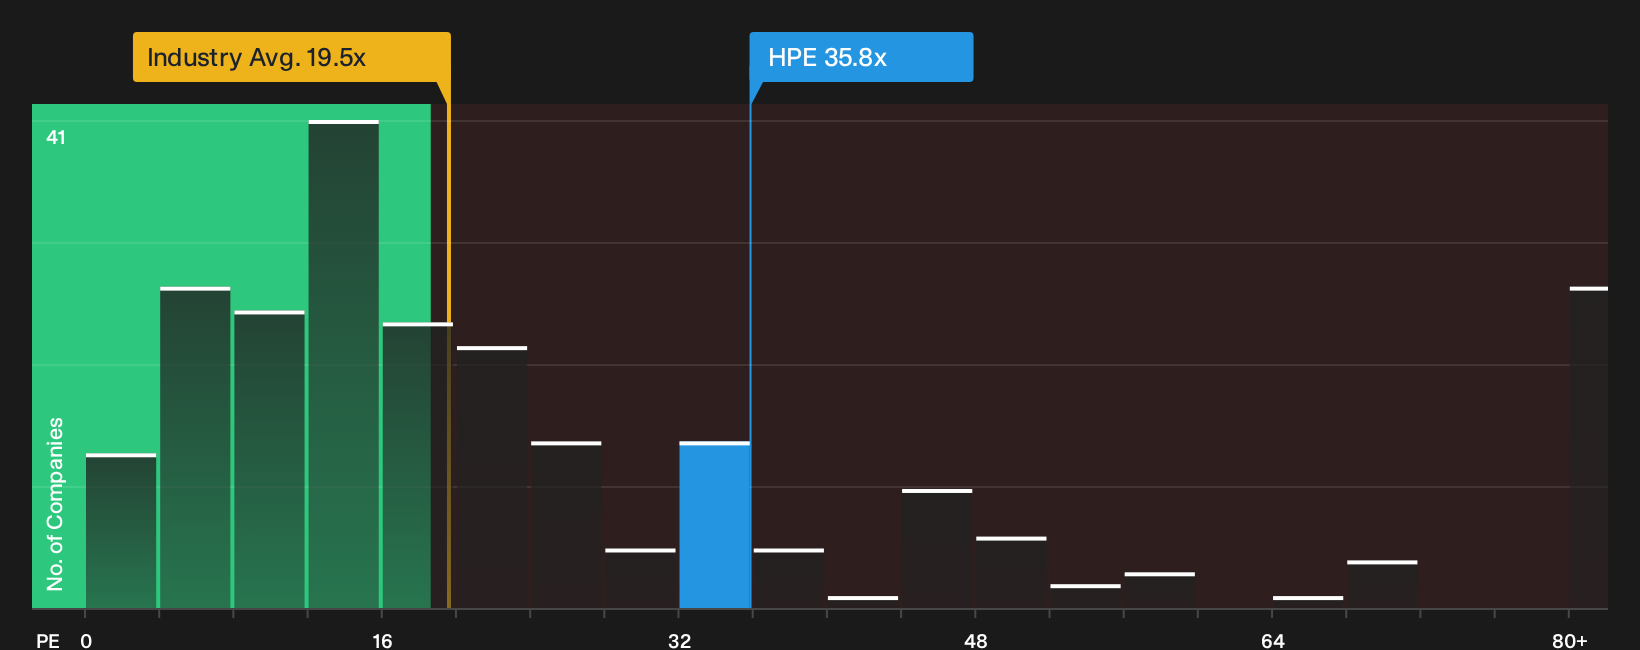
The most followed narrative calls Hewlett Packard Enterprise about 6% overvalued against a fair value of $68.08, yet the earnings multiple tells a different story. HPE trades on a P/E of 35.8x versus an estimated fair ratio of 39x and a peer average of 76.9x. This points to a valuation that prices in AI enthusiasm but still leaves less extreme multiple risk than some rivals. So is this a premium you are comfortable paying for, or a signal to demand a wider margin of safety?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Hewlett Packard Enterprise story seems divided between potential and risk, consider reviewing it now while the data is current by using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hewlett Packard Enterprise?
Do not stop with Hewlett Packard Enterprise. Broaden your watchlist now by scanning other opportunities that match your risk tolerance, income goals, and valuation preferences.
- Target steady compounding by focusing on financially robust businesses through a curated list of solid balance sheet and fundamentals (25 results) tailored to stronger balance sheets and fundamentals.
- Hunt for potential mispricings by using the 20 high quality undiscovered gems to spot quality companies that have not yet attracted broad market attention.
- Dial down volatility risk by filtering for 31 resilient stocks with low risk scores that emphasize resilient financial profiles and more measured return profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com