
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Main Street Capital (MAIN) Could Be 10% Undervalued Following Its Recent Pullback
Why Main Street Capital Is Back On Investors’ Radar
Main Street Capital (MAIN) has been drawing fresh attention after a period where the stock lagged the S&P 500, even as the broader market moved higher.
Investors are now weighing modest revenue growth against weaker earnings per share in recent years and slower tangible book value per share progress, trying to judge whether the current share price fairly reflects that mix.
At around US$54.18, Main Street Capital’s recent share price has drifted lower in the short term, with a 1 month share price return down 6.1% and year to date share price return down 12.3%, even though 3 year total shareholder return of about 71.7% and 5 year total shareholder return of about 89.5% still point to a strong longer run outcome. This softer near term move, including a 1 week share price return down 1.6%, suggests some investors are reassessing growth prospects and risk after weaker earnings per share and only modest revenue progress.
Compare Main Street Capital’s recent pullback with other income focused financials by scanning our hand picked 8 dividend fortresses that have held up better through similar pressure.
Recent weakness, softer earnings trends and only modest revenue progress leave Main Street Capital at an interesting crossroads. Does that combination now skew the risk reward toward buyers, or has the stock not reset enough yet?
Most Popular Narrative: 10.2% Undervalued
Main Street Capital’s most followed valuation storyline pegs fair value around $60.33 versus the recent $54.18 close. This frames the current pullback as a discount that still needs strong execution to hold up.
The main thing that has to go right is that new lower middle market platforms and the expanded private loan and external management businesses keep producing realized gains and fee income large enough to offset higher funding costs and lower dividend income from exited positions.
The current valuation implies the share price already reflects strong realized gains, a low-cost operating model and a conservative balance sheet. If these advantages fade or earnings weaken, Main Street Capital stock could trade below current levels.
See why 93 investors see Main Street Capital as 10% undervalued.
Result: Fair Value of $60.33 (UNDERVALUED)
Still, the story around Main Street Capital can shift quickly if higher funding costs keep pressuring margins or if dividend income from portfolio exits continues to fade.
Find out about the key risks to this Main Street Capital narrative.
Another View On Main Street Capital’s Valuation
A different lens gives a very different answer. Simply Wall St’s DCF model puts Main Street Capital’s value closer to $38.85 per share, below the recent $54.18 price, which points to an overvalued result rather than a 10.2% discount. Which version of fair value feels more realistic to you?
For investors who want to see how this cash flow based result is built step by step, Look into how the SWS DCF model arrives at its fair value.
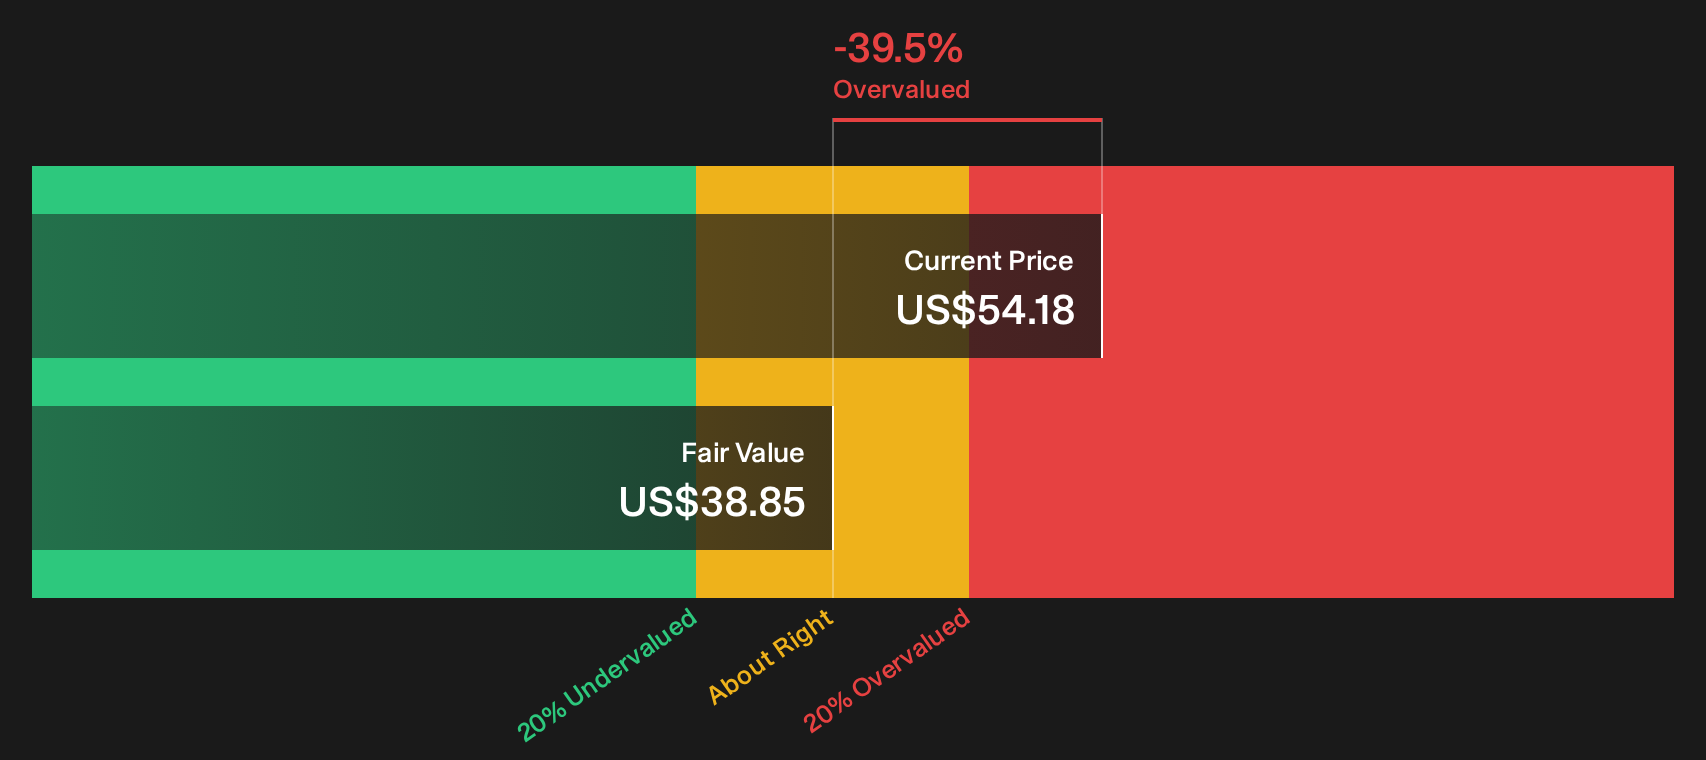
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Main Street Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With Main Street Capital drawing both concern and optimism, you may not want to remain undecided for long. Weigh the 1 key reward and 5 important warning signs.
Looking For More Ideas Beyond Main Street Capital?
If you stop with Main Street Capital, you risk missing other opportunities that match your goals, your risk comfort, and the kind of portfolio you actually want.
- Target resilient value by scanning a curated 29 high quality undervalued stocks that combines quality fundamentals with market pessimism that might have swung too far.
- Prioritise peace of mind by reviewing a focused 31 resilient stocks with low risk scores built around businesses with stronger balance sheets and more measured risk profiles.
- Hunt for earlier stage potential through a carefully filtered 12 elite penny stocks with strong financials where financial strength screens out the weakest prospects.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com