
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Lemonade (LMND) Cheap As Hawaii And Alaska Expansion Extends Its Growth Story?
Lemonade (LMND) just switched on renters insurance in Hawaii and Alaska, extending its app based model into two new states, where coverage starts at US$5 per month.
For shareholders, Lemonade’s launch in Alaska and Hawaii comes after a mixed run. The share price is up 1.14% over the past day and 3.74% across the week, yet down 12.32% over 30 days and 33.41% across 90 days. The 3 year total shareholder return of about 2.7x contrasts with a 15.62% decline over the last 12 months and a 28.91% drop across five years. Investors are weighing fresh product expansion and a US$46.83 share price against a history of sharp swings in sentiment.
Scan beyond Lemonade to see how other insurers with tech heavy models are priced and moving in our curated list of list of solid balance sheet and fundamentals (25 results).
Lemonade now trades about 25% below the average analyst price target, even after the Hawaii and Alaska rollout. Is that discount pricing in real risks, or leaning too hard on past volatility and losses?
Most Popular Narrative: 4% Undervalued
Lemonade’s most followed valuation story pegs fair value at $48.95 against a last close of $46.83, which points to a small gap that depends on how investors view risk and underwriting progress.
On rough arithmetic, justifying $52.36 needs roughly 28% growth with a 10% net margin and a multiple in the mid twenties. This means the current price is close to the base case rather than requiring a stretch. The uncomfortable part is that all three inputs are forecasts with no observed anchor.
See why 2 investors see Lemonade as 4% undervalued.
Result: Fair Value of $48.95 (UNDERVALUED)
Still, the Lemonade narrative can break quickly if the gross loss ratio drifts back toward 70% or if in force premium growth slows sharply from current levels.
Find out about the key risks to this Lemonade narrative.
Another View On Lemonade’s Valuation
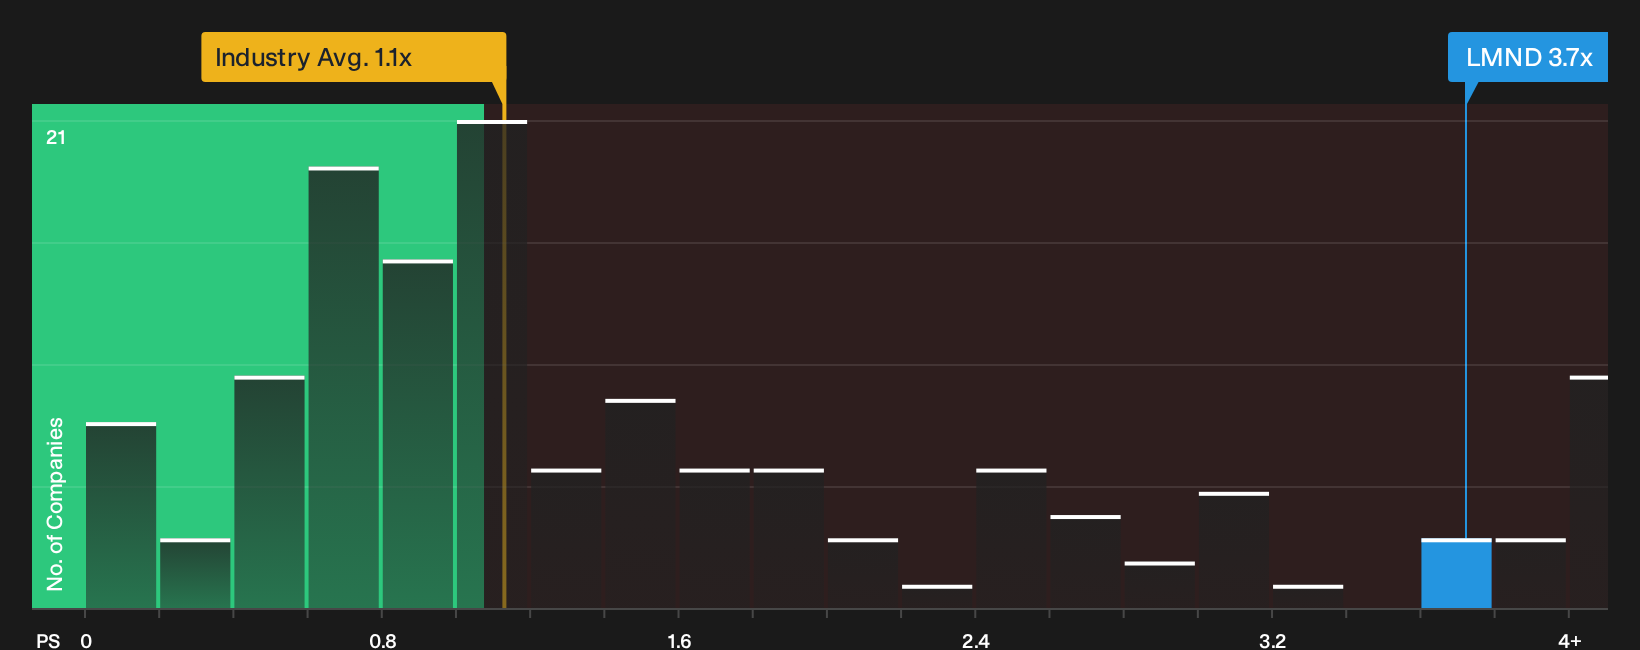
The first narrative presents Lemonade as about 4% below a $48.95 fair value, using long term growth, margins and a future multiple. A simpler lens tells a very different story. On P/S, the stock trades at 3.7x, while the US insurance industry sits near 1.1x and peers around 1.8x.
The fair ratio for Lemonade is estimated at 1.6x P/S, which is less than half the current level. That kind of premium can point to upside optionality if the growth story plays out, or to valuation risk if profitability keeps lagging. Which version of the story do you trust more today.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Lemonade can leave you torn between the upside story and the valuation concerns, so move quickly to review the full picture for yourself and then weigh the 2 key rewards and 1 important warning sign.
Looking for more Lemonade investment ideas beyond this stock
If you stop with Lemonade, you miss chances elsewhere. Use the Simply Wall St Screener to surface fresh ideas that match the risk and return profile you want.
- Chase quality at a discount by scanning a focused set of 29 high quality undervalued stocks that already pair strong fundamentals with appealing prices.
- Dial down stress and hunt for staying power across 31 resilient stocks with low risk scores that score well on resilience and financial strength.
- Spot future leaders early by trawling through 20 high quality undiscovered gems with robust balance sheets that have yet to attract broad attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com