
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Okeanis Eco Tankers (OB:OET) Shares Climbed, What Is Catching Investors' Attention?
Okeanis Eco Tankers (OB:OET) has drawn fresh attention as improved charter rates and tighter tanker supply linked to geopolitical events intersect with its earnings surprise record and dividend profile, sharpening investor focus on the stock.
The recent move to a NOK860.0 share price has come with strong momentum, with a 1 month share price return of 32.10% and a 90 day gain of 70.30%. The 1 year total shareholder return of 267.54% and very large 5 year total shareholder return suggest sustained interest as charter rates and geopolitical supply constraints reshape how investors are pricing Okeanis Eco Tankers.
Scan for other shipping and energy plays showing similar momentum and earnings surprise potential with our hand picked 619 high quality undiscovered gems list.
Okeanis Eco Tankers looks like a robust crude carrier business in a hot market, yet the share price has sprinted far ahead of analyst targets. Is the recent surge already baking in the good news?
Most Popular Narrative: 35% Overvalued
Okeanis Eco Tankers closed at NOK860, while the most followed narrative points to a fair value of about NOK638. The story now hinges on whether tanker fundamentals can keep justifying this premium and a much richer earnings multiple.
Structural vessel undersupply, driven by an aging global fleet (half of VLCCs/Suezmaxes to be over 15 years by 2028), limited newbuild activity, and a large portion of "shadow" or sanctioned tonnage being both aging and unlikely to return to mainstream trading, is expected to sustain or elevate charter rates and boost long-term revenue and EBITDA. Okeanis' modern, eco-friendly fleet (average age 5.9 years, youngest among listed peers) and widespread scrubber adoption positions the company to capture regulatory-driven competitive advantages (IMO/EU emissions), lower operating costs per vessel, and command premium charter rates, lifting net margins and overall earnings.
See why 15 investors see Okeanis Eco Tankers as 35% overvalued.
Result: Fair Value of NOK638 (OVERVALUED)
Still, the story can break if crude demand drifts lower over time or if Okeanis Eco Tankers faces pressure from its relatively high leverage.
Find out about the key risks to this Okeanis Eco Tankers narrative.
Another View: What OET’s Earnings Multiple Signals
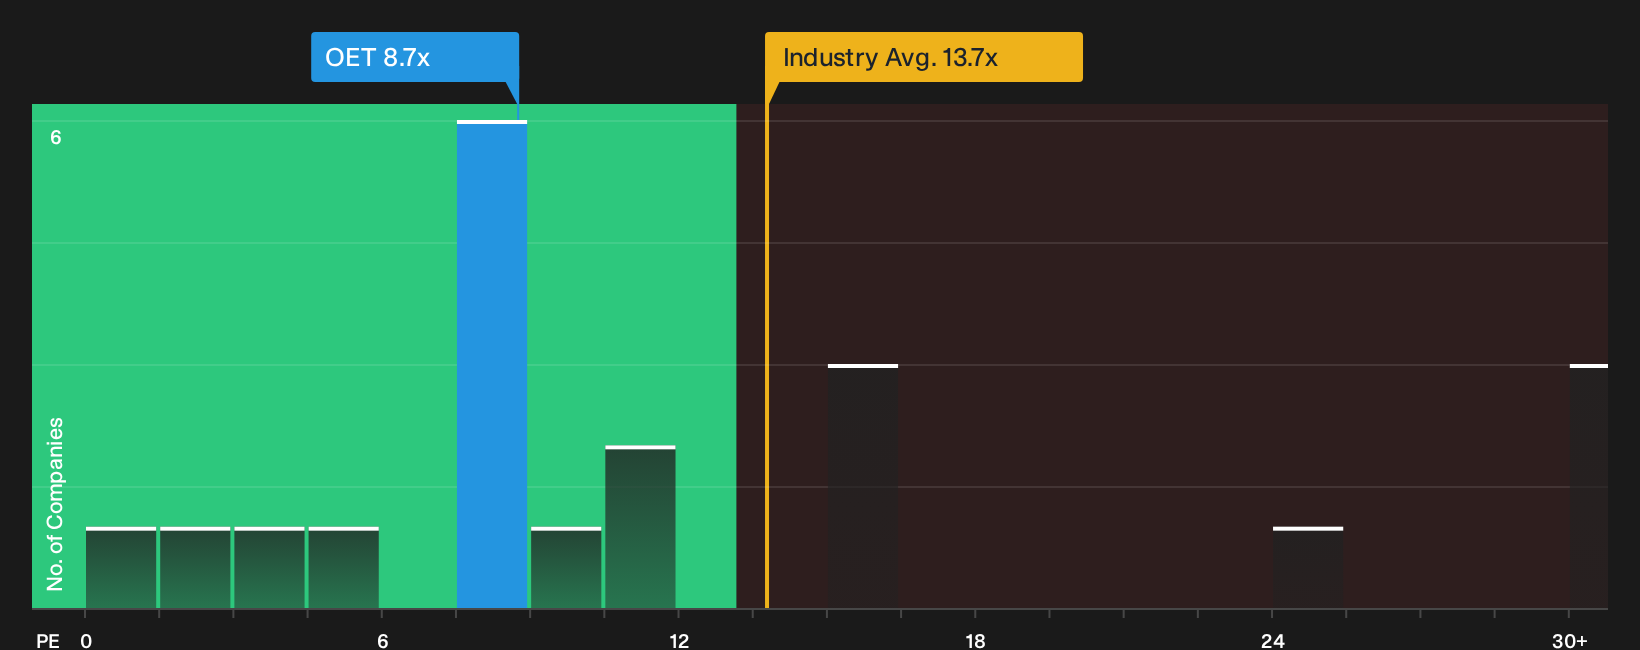
On simple P/E math, Okeanis Eco Tankers trades on about 8.7x earnings, which is cheaper than both the Norwegian market on 13.6x and the European oil and gas group on 13.9x. On that comparison, the stock looks restrained rather than euphoric.
The fair ratio tells a different story. It sits at 4.9x, well below the current 8.7x. If the market drifts closer to that fair ratio, today’s rich share price could leave less room for error than the headline discount to peers suggests. The question is which anchor you place more weight on.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big moves and split opinions around Okeanis Eco Tankers can be exciting, so do not wait too long to pressure test the thesis yourself. Round out your own view by weighing both the upside arguments and the 2 key rewards and 5 important warning signs.
Looking for more Okeanis Eco Tankers style ideas?
If Okeanis Eco Tankers has sharpened your appetite for opportunities, use the screener to quickly surface fresh ideas before other investors start paying attention.
- Target reliable income ideas by scanning companies built around durable payouts with the 224 dividend fortresses.
- Hunt for quality at a discount using the 184 high quality undervalued stocks and compare fundamentals before committing fresh capital.
- Lock onto financially resilient candidates that can handle tougher conditions through the 225 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com