
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Dominion Energy (D) A Bargain After NextEra’s Proposed $67b Takeover?
NextEra Energy’s proposed US$67b acquisition of Dominion Energy (D) has moved from a boardroom concept to a political flashpoint, with Virginia officials publicly questioning potential impacts on bills, jobs, and clean-energy plans.
At a share price of US$61.53, Dominion Energy is trading after a recent 7 day share price return of 1.67%, although the stock is still down 6.55% over 30 days and 11.40% over 90 days. The 1 year total shareholder return sits at 5.92% and the 3 year total shareholder return is 64.95%, which suggests longer term holders have seen momentum that the current deal headlines and regulatory back and forth may now be testing.
Scan hand picked 43 power grid technology and infrastructure stocks that could also be in the spotlight as regulators weigh how Dominion Energy and NextEra reshape the future of US electricity infrastructure.Bulls see Dominion Energy as a regulated utility caught in merger noise; bears see a politically exposed asset at risk of overhang. The valuation work now needs to show which story the current price supports.
Most Popular Narrative: 14% Undervalued
Dominion Energy’s most followed valuation narrative pegs fair value at $71.64, above the recent $61.53 close. This puts the merger drama against a backdrop of longer dated cash flow assumptions and regulated project buildouts.
The current valuation implies the market is still discounting Dominion Energy’s potential benefits from long-lived regulated investment in projects such as CVOW, large-load infrastructure and the planned merger synergies, despite the narrative that the stock is undervalued and bullish.
See why 54 investors see Dominion Energy as 14% undervalued.
Result: Fair Value of $71.64 (UNDERVALUED)
Still, that story can crack if regulators push back on the NextEra tie up, or if further delays and cost creep at Coastal Virginia Offshore Wind squeeze returns.
Find out about the key risks to this Dominion Energy narrative.
Another View: Dominion Energy On Earnings Multiples
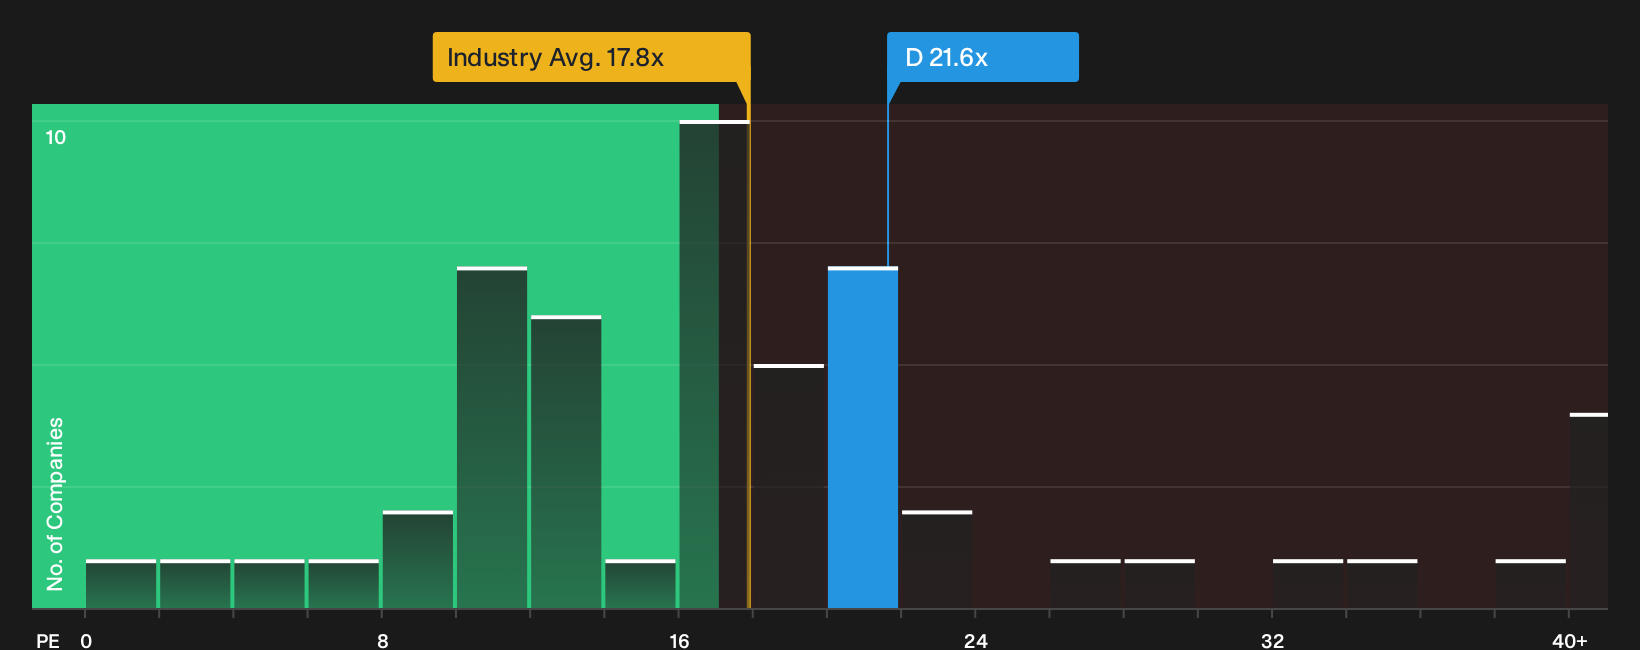
The DCF-based fair value paints Dominion Energy as undervalued, yet the market is not giving it away on earnings. The stock trades on a P/E of 21.6x, which is richer than both its peer group at 19.5x and the global integrated utilities average at 17.8x, and only slightly below a fair ratio of 22.5x. That gap points to limited valuation cushion if sentiment or forecasts shift. How comfortable are you paying a premium today for a story built on long dated projects and merger headlines?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on the story so far about Dominion Energy or feeling pulled in both directions by the merger and valuation angles? Dig into the data, move quickly, and weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Dominion Energy?
If Dominion Energy has your attention, do not stop here. Use the same structured approach on other opportunities and keep your watchlist working harder for you.
- Hunt for quality at a discount by running through our 29 high quality undervalued stocks, which lines up strong fundamentals with prices that may lag underlying business strength.
- Target resilience first and let upside follow with a focused pass through our 31 resilient stocks with low risk scores, which screens for sturdier balance sheets and steadier scorecards.
- Surface fresh opportunities early by combing through our 20 high quality undiscovered gems, which highlights under-the-radar companies with financial profiles too strong to ignore.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com