
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
GitLab (GTLB) Could Be 7% Undervalued Following Its AI Platform Expansion
GitLab (GTLB) just rolled out a broad upgrade to its governed software factory, integrating AI driven Duo Agent workflows, artifact management, and new security controls into a single, policy driven development platform.
These upgrades come as GitLab’s momentum has picked up, with a 90 day share price return of 53.54% and a year to date share price gain of 43.70% from a latest close of US$51.99. However, the 1 year total shareholder return of 9.82% and 3 year total shareholder return of 7.55% point to a more muted longer run record that investors are weighing against this recent acceleration.
Spot emerging AI infrastructure momentum plays alongside GitLab by scanning the hand picked 92 AI infrastructure stocks.GitLab now trades close to published analyst and intrinsic value estimates after a sharp run. Does that leave meaningful upside on the table, or suggest the price already reflects the story?
Most Popular Narrative: 6.7% Undervalued
Against a last close of $51.99, the most followed narrative pegs GitLab’s fair value closer to $55.71. This puts recent gains against a still modest implied discount that relies heavily on AI, Duo Agent, and Flex consumption playing out as expected.
GitLab's expansion of AI-driven capabilities across its DevSecOps platform, including the upcoming Duo Agent Platform with hybrid usage-based monetization, is expected to capture increased demand for automation and developer productivity tools, potentially accelerating revenue growth and expanding margins as high-value features command premium pricing and upsell opportunities.
See why 79 investors see GitLab as 7% undervalued.
The narrative leans on a discount rate of 8.59% and an assumed long run revenue growth rate of 15.39%, with profitability modeled at an 11.60% margin that supports a fair value estimate of $55.71 per share against GitLab’s current loss making status.
Those same forecasts imply a future P/E multiple of 61.19x on the modeled 2029 earnings, which is materially higher than the 29.7x industry context embedded in the narrative and helps explain why the implied undervaluation remains modest despite GitLab already trading only around 4.7% below that fair value line.
Result: Fair Value of $55.71 (UNDERVALUED)
Still, the GitLab story can break if competitive pressure from GitHub and AI native tools bites harder than expected, or if Flex consumption adds prolonged revenue volatility.
Find out about the key risks to this GitLab narrative.
Another View: GitLab Through The Sales Multiple Lens
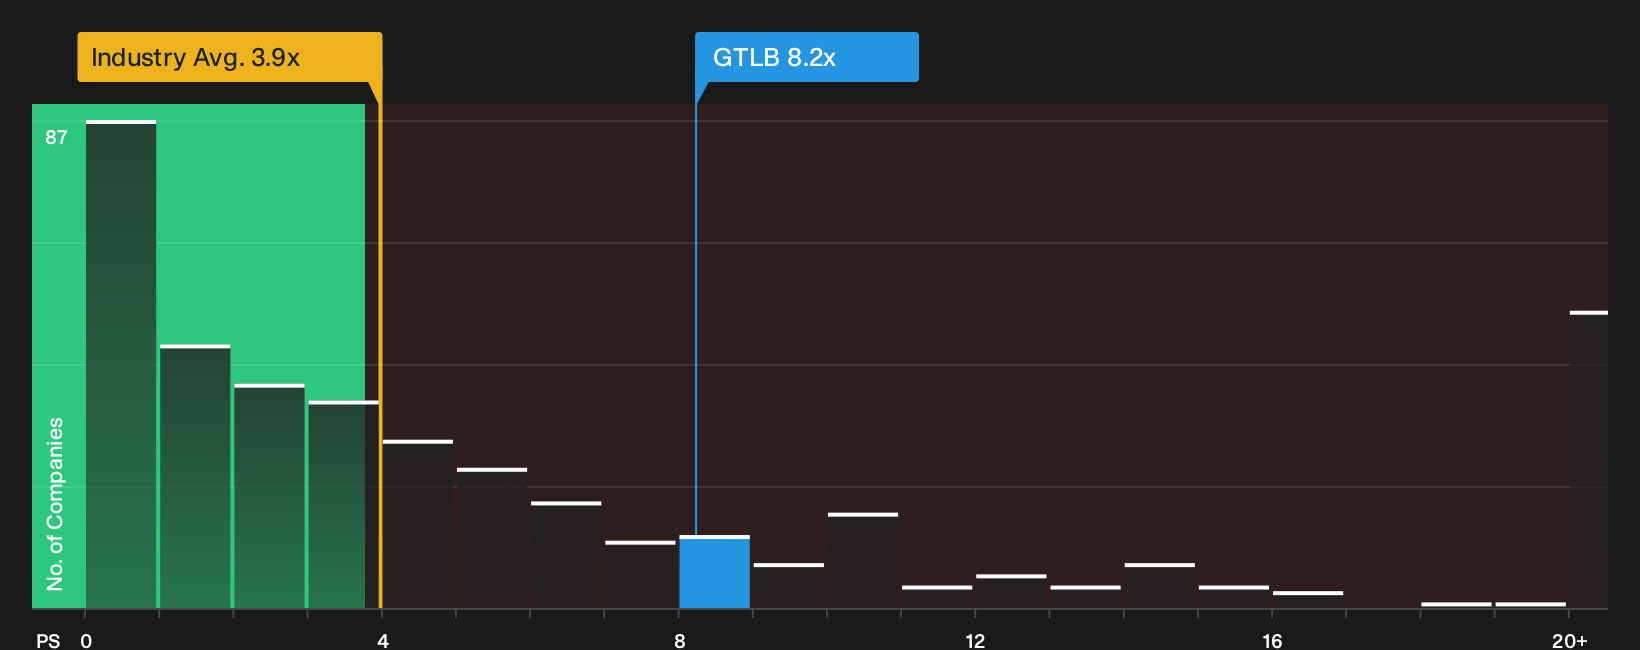
GitLab may screen as 6.7% undervalued against the $55.71 fair value narrative, yet its P/S ratio of 8.2x tells a tougher story. That is higher than the US Software industry at 3.9x and above a 7x fair ratio the market could move toward, even if it still sits below the 9.3x peer average. For investors, that mix points to real valuation risk if sentiment cools before fundamentals catch up, so how comfortable are you paying this premium for the AI and Flex roadmap?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong views are already forming around GitLab, but the real edge comes from testing those risk and reward signals yourself and then weighing the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond GitLab?
You have already done the hard work understanding GitLab. Do not stop there when a wider set of opportunities could sharpen your next decision.
- Target value first and see which companies combine quality fundamentals with a potential discount through the 29 high quality undervalued stocks.
- Prioritise resilience and scan for businesses with sturdier finances and lower risk profiles using the 31 resilient stocks with low risk scores.
- Hunt for under-the-radar opportunities by checking the 20 high quality undiscovered gems before the crowd moves in.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com